A property can face flood risk outside a high-risk flood zone. Check the address and the proposed coverage rather than using the flood-zone label alone to decide whether to request a quote.
Flood damage can occur outside mapped high-risk zones. If your basement has taken on water in heavy rain, identify how it entered: surface flooding, seepage, and drain backup need different coverage decisions.
North Shore Flood Risk: What You Need to Know
Skokie River Corridor
Properties along the Skokie River in Winnetka, Glencoe, Northfield, and parts of Wilmette face the highest flood risk on the North Shore. FEMA flood maps show clear high-risk zones along the river’s path, and homes here may be required to carry flood insurance if they have a federally backed mortgage.
Lake Michigan Proximity
Lakefront and near-lakefront properties in Wilmette, Kenilworth, and Winnetka face risk from lake-level fluctuations and storm surge. Lake Michigan reached record-high levels in 2020, causing significant erosion and property damage along the shore.
Storm Water and Drainage Issues
Even homes well away from waterways can flood. Older storm sewer systems in many North Shore communities can be overwhelmed during heavy rainfall events, pushing water into basements through floor drains and window wells. Water that comes up through floor drains is usually a water backup claim, which needs a water backup endorsement on the homeowners policy. Surface water pouring in through window wells during a widespread flood needs a flood policy.
NFIP vs. Private Flood Insurance
National Flood Insurance Program (NFIP)
The federal program offers coverage up to $250,000 for dwelling and $100,000 for contents. Premiums under the new Risk Rating 2.0 system are based on individual property risk rather than just flood zone designation. For many North Shore homes, NFIP premiums range from $500 to $3,000+ per year.
NFIP limitations: the $250,000 dwelling cap is far below the rebuild cost of most North Shore homes, and basement contents coverage is very limited.
Private Flood Insurance
Private flood carriers offer several advantages:
Higher dwelling limits (up to $5 million or more)
Better basement and contents coverage
Often competitive pricing, especially for lower-risk properties
Additional living expense coverage (NFIP doesn’t include this)
For high-value North Shore homes, a private flood policy is often the better choice due to the higher coverage limits alone.
What Flood Insurance Costs on the North Shore
Costs vary significantly based on your property’s specific risk:
Low-risk zone (Zone X): $400–$1,200/year
Moderate-risk zone: $800–$2,500/year
High-risk zone (Zone AE): $1,500–$5,000+/year
Private flood policies can often beat NFIP pricing for properties in moderate and low-risk zones.
CRS Discounts
Several North Shore communities participate in FEMA’s Community Rating System (CRS), which earns premium discounts for NFIP policyholders. Wilmette, for example, has historically participated in CRS, providing residents with a discount on their flood premiums. Check with your village for current CRS classification and discount levels.
Do You Need Flood Insurance?
You definitely need it if:
Your home is in a FEMA-designated high-risk flood zone
Your mortgage lender requires it
You’ve experienced basement flooding before
You’re near the Skokie River, Lake Michigan, or any drainage channel
You should seriously consider it if:
Your home has a finished basement (the most common flood damage scenario)
Your area has aging storm sewer infrastructure
You live in a low-lying area, even outside a flood zone
You would rather pay a modest premium than carry the risk yourself
Get a Flood Insurance Quote
Longmeadow Insurance quotes both NFIP and private flood policies. We’ll compare the two for your address and show you the price and limit differences. Request a free quote or call 847.242.1040.
Short answer: Sewer and sump backup generally need an endorsement on your homeowners policy. Choose the limit from the cost of cleanup, repairs, and replacing basement belongings. Surface flooding and groundwater seepage are separate issues; a backup endorsement does not cover every basement water loss.
Water in a basement is one of the most common and most frustrating insurance problems. Homeowners often describe any basement water as flooding, but insurance policies make important distinctions. Sewer backup, sump overflow, seepage, burst pipes, roof leaks, and flood can all be treated differently.
Sewer backup coverage, often sold as water backup coverage, is usually added by endorsement. It can be extremely valuable, but it is not unlimited and it does not cover every type of water loss.
Sewer backup coverage focuses on drains and systems
Sewer backup generally refers to water or sewage backing up through a sewer, drain, sump, or related system. Examples may include a floor drain backing up during heavy rain or a sump system overflowing.
The exact policy language matters, so homeowners should review how the endorsement defines covered water backup and what systems are included.
It is different from flood insurance
Flood insurance generally involves outside surface water affecting normally dry land and entering the home. A basement can have water from both sewer backup and flood-like conditions during the same storm, which can make claims complicated.
A homeowners policy with sewer backup coverage is not the same as a flood policy. If surface water enters through a window well, door, or foundation opening, sewer backup coverage may not solve the problem.
Limits can be too low for finished basements
Many policies offer choices such as $5,000, $10,000, $25,000, $50,000, or higher where available. A finished basement with drywall, flooring, furniture, mechanical systems, and electronics can exceed a low limit quickly.
Cleanup and mitigation alone can be expensive before repairs even begin.
Maintenance and prevention still matter
Backwater valves, sump pump maintenance, battery backups, generator planning, grading, gutters, downspouts, and sewer line maintenance can reduce risk. Insurance helps after a covered loss, but prevention can reduce the chance and severity of the claim.
Homeowners should also keep photos and documentation of basement finishes and major belongings.
Review the deductible and property covered
Some endorsements may have separate deductibles or special limits. Confirm whether both building damage and personal property are covered, and whether loss of use applies if the home becomes temporarily uninhabitable.
Do not assume every water-related cost is included.
How to Size the Limit
Most policies default to $5,000 or $10,000 of backup coverage, and most finished lower levels are worth several times that. Size it by adding up what is actually down there rather than accepting the default.
Count the finished flooring and the drywall up to the height water would reach. Add the mechanicals sitting on the floor (the furnace, water heater, and any laundry equipment) and the contents: furniture, a television, stored boxes, and anything in a closet at floor level. Then add cleanup and remediation, which on a sewage backup is a specialist job rather than a wet vacuum, and which frequently costs more than the drywall it dried out.
For most finished North Shore basements the honest number lands well above $10,000. Raising the limit is inexpensive relative to what it covers, which is why we ask about it on every home policy we write here.
Three Different Water Problems, Three Different Answers
The word people use is flooding. The policy distinguishes three separate causes and covers them three separate ways, which is where most claim disputes begin.
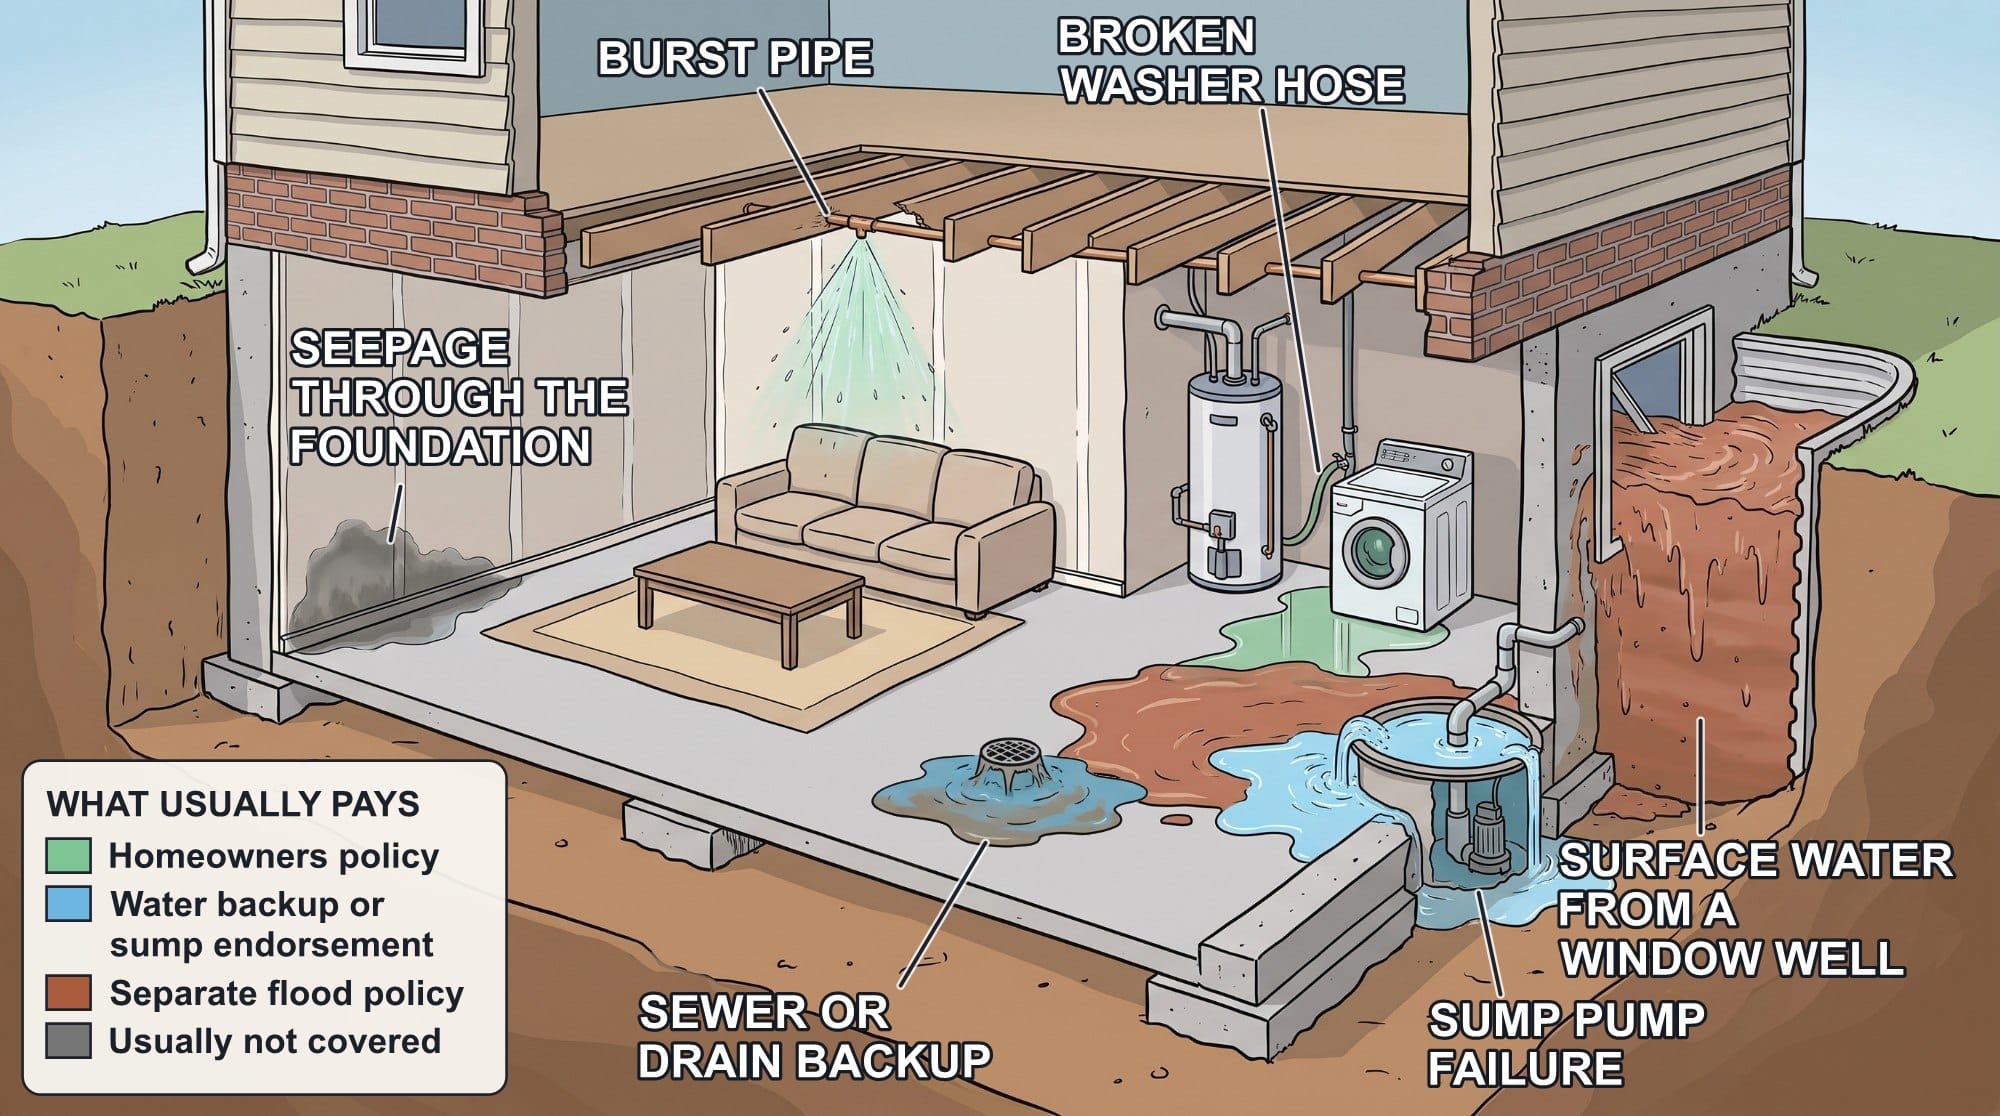
Six ways water gets into a basement. Which policy usually pays depends on the source: the homeowners policy for a sudden burst pipe or broken appliance hose, a water backup endorsement for drains and sump pumps, a separate flood policy for surface water, and usually nothing for slow seepage.
Water backing up through a drain or sewer. The endorsement discussed on this page. Excluded without it.
A sump pump that fails or is overwhelmed. Often included in the same endorsement, but not always, and some carriers price it separately. Confirm rather than assume.
Surface water entering at grade. That is flood, excluded from the homeowners policy entirely, and it needs an NFIP or private flood policy.
A single heavy rain can produce all three at once in the same basement, and the adjuster will apportion the loss between them. Carrying only one of the three is how a homeowner ends up paying for most of a claim they believed was covered.
Frequently asked questions
Is sewer backup automatically included?
Not always. It is often optional or limited, so review your declarations page.
Does sewer backup cover flood?
No. Flood needs a separate NFIP or private flood policy.
How much sewer backup coverage do I need?
It depends on basement finish, contents, mechanical systems, and cleanup exposure.
Talk with a local independent insurance agency
Longmeadow Insurance can help Illinois homeowners review sewer backup coverage, flood insurance, water backup limits, and basement exposure before the next heavy rain. To start a review, use our get a quote form or call 847.242.1040.
Water claims are among the most frustrating insurance problems because homeowners often learn the definitions only after the basement is wet. Many people use the word flood to describe any water in the house. Insurance policies do not work that way. A sewer backup claim and a flood claim can look similar from the homeowner’s perspective. Both can put water in a basement. Both can damage flooring, drywall, mechanical systems, furniture, and stored property. But they are usually covered by different policies or endorsements. The distinction matters across Chicago, the North Shore, Lake County, DuPage County, and the western suburbs, where heavy rain, older sewer systems, and finished basements make water losses expensive.
Three Different Kinds of Water, Three Different Answers
Most confusion here comes from treating basement water as one problem. Insurers treat it as three, and which one you had determines which policy responds.
What happened
What it is called
What pays
Sewer line or municipal main backs up through a floor drain or toilet
Sewer backup
Water backup endorsement on your homeowners policy
Sump pump fails, jams, or cannot keep up and the pit overflows
Sump overflow
The same water backup endorsement, if the wording includes sump overflow
Surface water enters from outside, over the foundation or through window wells
External flooding (overland flood)
A separate flood policy. Not the water backup endorsement
Two mistakes cause particular confusion: assuming a backup endorsement covers outside surface flooding, and assuming flood insurance pays for an isolated sump failure. A backup directly caused by a qualifying flood is a different situation. Have the cause and both policies reviewed when one storm creates several kinds of water damage.
What Sewer Backup Coverage Usually Means
Sewer backup coverage, often sold as water backup coverage, is typically added to a homeowners policy by endorsement. It is designed for water or sewage that backs up through a sewer, drain, sump, or similar system. Common examples include a floor drain backing up during heavy rain, a sump pump failing during a storm, or water entering through a drain in a finished basement. This coverage is not automatically unlimited. Policies often offer choices such as $5,000, $10,000, $25,000, $50,000, or higher limits depending on the insurer and the property. A finished basement with drywall, flooring, furniture, mechanical equipment, and electronics can exceed a small limit quickly. Homeowners should also check whether the endorsement covers both building damage and personal property, whether there is a separate deductible, and whether mechanical breakdown of a sump pump is treated differently from power failure or overwhelmed drainage.
What Flood Insurance Usually Means
Flood insurance generally applies when water comes from outside the home and affects normally dry land. Examples include overflowing rivers, storm surge, surface water runoff, and water that enters through windows, doors, window wells, or foundation openings because the surrounding ground is inundated. Standard homeowners policies exclude flood damage. That exclusion applies even if the homeowner is not in a lender-required flood zone. A property can be outside a mapped high-risk zone and still experience surface water flooding during a severe storm. Flood insurance may be available through the National Flood Insurance Program or through private flood markets. Each option has different limits, pricing, waiting periods, coverage terms, and claim handling characteristics.
Why Chicago Area Homeowners Confuse the Two
The confusion happens because the same storm can create multiple types of water damage. Heavy rain can overwhelm municipal systems, saturate soil around the foundation, push water toward window wells, and cause drains to back up. One basement loss may involve both surface water and sewer backup issues. From the homeowner’s point of view, it is all storm water. From the policy’s point of view, what matters is the path the water took into the home. Water through a drain may trigger one coverage. Water through a window well may require flood insurance. Water through a foundation crack may be treated differently again. This is why the coverage review needs to happen before the storm. Once water enters the basement, it is too late to restructure the policy. Water is only one of the ways a storm can leave a bill the policy does not cover; our guide to storm damage coverage gaps covers the others, from wind and hail deductibles to tree removal.
Finished Basements Need Higher Water Limits
Many Chicago and suburban homes have basements that are no longer storage space. They are family rooms, offices, gyms, guest suites, playrooms, and finished living areas. That increases the financial impact of a water claim. A small sewer backup limit may be reasonable for an unfinished utility area. It is usually not enough for a finished basement with flooring, trim, drywall, furniture, built-ins, and electronics. Homeowners should estimate the actual cost to remove damaged materials, dry the space, rebuild, replace contents, and address possible mold remediation. The right limit depends on the property. It should not be chosen casually from the default option on a quote.
Flood Zones Are Not the Whole Story
A mortgage lender may require flood insurance if a property is in a designated flood zone. That requirement is not the same as a complete risk analysis. Many homes outside those zones still have meaningful flood exposure from intense rainfall, poor drainage, nearby waterways, or grading that directs water toward the structure. Homeowners in Wilmette, Winnetka, Glencoe, Evanston, Oak Park, Elmhurst, Gurnee, and other communities should evaluate water risk based on the property, not only the map. Local drainage history, basement elevation, sump systems, neighborhood grading, and past water issues matter.
Common Water Claim Mistakes
The most common mistake is assuming every basement water claim is covered because the homeowner purchased insurance. Standard policies draw sharp distinctions between flood, sewer backup, seepage, groundwater, sump failure, and sudden plumbing discharge. Each category can be treated differently. A second mistake is choosing a low sewer backup limit because it reduces premium. That may be acceptable for an unfinished basement, but it is rarely enough for a finished lower level with flooring, drywall, furniture, and mechanical systems. A third mistake is waiting until after a neighborhood flood event to buy flood insurance. Flood policies often have waiting periods, and coverage cannot be added retroactively.
How to Think About the Right Limits
Start with the value of what is below grade. Include drywall, flooring, trim, furniture, mechanical equipment, appliances, electronics, storage, and cleanup costs. Then consider how much water remediation and rebuilding would cost if contractors are in high demand after a major storm. For flood insurance, consider the structure, basement limitations, personal property restrictions, and whether a private flood option offers broader terms than a standard federal policy.
Does Home Insurance Cover Sump Pump Failure?
Usually not on the base policy. Water that backs up through a sump, drain, or sewer is excluded from a standard homeowners form, and it is covered only if you carry the water backup and sump overflow endorsement. It is usually a separate purchase with its own limit, so look for it by name on your declarations page.
The endorsement generally responds when the pump fails mechanically, when it is overwhelmed by volume, or when it stops because the power went out, though power-outage wording varies by carrier and is worth confirming specifically. What it does not do is pay to replace the pump itself, which is maintenance.
Other Ways Water Gets Into a Basement
Six ways water gets into a basement. Which policy usually pays depends on the source: the homeowners policy for a sudden burst pipe or broken appliance hose, a water backup endorsement for drains and sump pumps, a separate flood policy for surface water, and usually nothing for slow seepage.
What happened
What it is called
What pays
Power goes out during a storm and the pump stops
Sump overflow, usually
Depends on carrier wording. Some require a battery backup to have been in place
Groundwater seeps through the foundation or slab
Seepage
Generally excluded by everything. Treated as maintenance
A pipe inside the wall bursts
Sudden and accidental discharge
Covered by the base homeowners policy
Does Homeowners Insurance Cover Basement Flooding?
It depends on where the water came from. A homeowners policy usually pays for sudden water from inside the house, such as a pipe that freezes and bursts or a water heater or washing machine hose that gives way. Water that comes in from outside needs a flood policy, and water that comes up through a drain or sump needs a water backup endorsement.
Even when the water itself is covered, a few things usually are not: the broken pipe, pump, or sewer line itself, since the policy pays for the damage it caused rather than the failed part; mold, which many policies cap at a low limit or exclude; slow seepage through the foundation; and damage from maintenance that was put off.
Rain can cause more than one kind of loss at once. Surface water needs flood coverage, while a drain or sump backup during the same storm falls under the backup endorsement, so the cause of each part of the damage matters more than where the water came in. If you are weighing whether a claim is worth filing, our guide on when to file a claim and when to pay it yourself walks through the deductible and premium questions.
The Battery Backup Question
Storms in this region knock out power and drop several inches of rain at the same time, which is exactly when a sump pump is needed and exactly when it has no electricity. A battery backup or water-powered secondary pump is the single most useful thing most Chicago-area basements are missing.
It matters for insurance in two directions. Some carriers offer a credit for having one. More importantly, some water backup wording is narrower about power-related failure, and a functioning secondary pump removes the argument entirely.
Sump Pump and Backup Questions
Does homeowners insurance cover a failed sump pump?
Only if you carry the water backup and sump overflow endorsement. A standard homeowners policy excludes water that backs up through a sump or drain. The endorsement covers the resulting damage to your basement and belongings, not the cost of replacing the pump.
Is sump pump failure covered by flood insurance?
An isolated sump failure is usually a water-backup or sump-overflow claim. If a qualifying flood directly causes the backup, flood coverage can come into play. Many households need both coverages because the causes differ.
What if the power went out and the pump stopped?
Most water backup endorsements respond, but the wording varies and a few carriers are narrower about power-related failure. If you do not have a battery backup pump, this is the specific sentence in your policy worth reading before storm season rather than after.
How much water backup coverage should I carry?
Size it against what is actually in the basement. A finished lower level with a bathroom, flooring, drywall, mechanicals, and stored belongings costs far more to restore than the default endorsement limit most policies carry. Unfinished storage space needs much less.
Will one water claim affect my rate?
Water claims carry more weight with carriers than most homeowners expect, and repeat water claims at the same address affect both price and availability. That is an argument for sizing the limit correctly and for prevention, not for going without the coverage.
Prevention Still Matters
Insurance is not a substitute for maintenance. Sump pumps, battery backups, drain cleaning, grading, downspouts, backflow valves, water sensors, and regular inspections all reduce the chance and severity of a claim. Good risk control can also make coverage easier to place.
Coverage Review Checklist
Confirm whether your policy includes sewer backup
Review the sewer backup limit against your finished basement value
Ask whether sump pump failure is included
Evaluate private flood and NFIP options
Do not rely only on lender flood-zone requirements
Document basement improvements and contents
Consider water sensors and backup power for sump pumps
Water Backup, Flood Insurance, or Both
Longmeadow Insurance can review your water-related coverage and help determine whether sewer backup, flood insurance, or both should be part of your plan.
How Longmeadow Insurance Can Help
Longmeadow Insurance is an independent agency based in Wilmette, Illinois. Send us your current declarations pages and we will tell you what they cover, and where the gaps are, before we quote anything. For a coverage review, call 847.242.1040 or request a consultation online.
Every spring, heavy rain, saturated ground, and overwhelmed storm sewers put water into basements across the communities north of Chicago. Many homeowners learn only after the cleanup starts that their policy does not cover it.
If you live in communities like Glenview, Northbrook, Vernon Hills, Libertyville, Deerfield, Winnetka or Highland Park, check your flood risk and the water exclusions in your homeowners policy before the spring storms.
Why the Northern Suburbs Are Especially Vulnerable
The geography and infrastructure of Chicago’s northern suburbs add up to real flood risk each spring:
Flat terrain and clay-heavy soil. Much of the northern suburban landscape is relatively flat, and the dense clay soils common to the region absorb water slowly. When spring rains arrive, especially after a wet winter, the ground simply has nowhere to send the water.
Aging storm sewer systems. Many suburban communities were developed decades ago with infrastructure that wasn’t designed for the volume of impervious surface (driveways, rooftops, parking lots) that exists today. When heavy rains hit, storm sewers can quickly back up.
Proximity to the Des Plaines River and its tributaries. Communities along the Des Plaines River corridor, including Libertyville, Mundelein, and portions of Vernon Hills, face regular flood events when the river overflows its banks after sustained rain.
Heavy spring storms. Spring storms can drop two to four inches of rain in a few hours, far more than aging drainage systems can handle.
FEMA maps identify Special Flood Hazard Areas, but homes outside those areas can also flood. Review the property’s elevation, drainage history, and basement use instead of relying on the zone alone.
What a Standard Homeowners Policy Leaves Out
Here is the critical fact that surprises many homeowners after a flood loss:
Standard homeowners insurance policies do NOT cover flood damage. Water that enters your home from the ground up (whether from overland flooding, a river overflow, or a backed-up storm sewer) is typically excluded entirely from a standard policy.
This exclusion applies regardless of the cause of the flooding. Here is how insurance typically treats common water damage scenarios.
Six ways water gets into a basement. Which policy usually pays depends on the source: the homeowners policy for a sudden burst pipe or broken appliance hose, a water backup endorsement for drains and sump pumps, a separate flood policy for surface water, and usually nothing for slow seepage.
Overland Flooding (Surface Water)
When rainwater flows across the ground and enters your home through doors, windows, or foundation cracks, that is a flood, and a standard homeowners policy does not cover it.
Sewer or Drain Backup
When municipal storm sewers become overloaded during heavy rain, water can back up through floor drains, toilets, and basement sinks. This is one of the most common causes of basement flooding in the northern suburbs, and it is also excluded from standard policies unless you have added a Sewer & Drain Backup endorsement, often called water backup coverage.
Sump Pump Failure
Many northern suburb homes rely on sump pumps to manage groundwater. If the pump fails (whether due to power outage, mechanical failure, or simply being overwhelmed) the resulting water damage is typically not covered unless you carry a Sump Pump Failure endorsement.
Coverage Options to Ask About
Coverage is available, but in most cases you must specifically request it. Here are the key options to discuss with your agent:
National Flood Insurance Program (NFIP). Backed by FEMA, NFIP policies provide up to $250,000 in structural coverage and $100,000 for contents. They are available to homeowners in participating communities regardless of flood zone designation. Note: there is typically a 30-day waiting period before coverage takes effect, so don’t wait until storm season is underway.
Private Flood Insurance. Private market flood policies have grown significantly in recent years and can offer higher coverage limits, broader definitions of flood, shorter waiting periods, and coverage for items (like finished basements) that NFIP may limit. They can be a strong alternative or supplement for higher-value homes.
Sewer & Drain Backup Endorsement. This is an add-on to your standard homeowners policy that specifically covers water damage from backed-up sewers, drains, and sometimes sump pumps. Given how frequently this happens in the northern suburbs, it is one of the most important endorsements a homeowner in this area can carry. Sump Pump Failure Coverage. Often packaged with the sewer backup endorsement, this coverage protects you specifically when your sump pump fails or is overwhelmed. Given that a single sump pump failure can cause $20,000-$50,000 in basement damage, this is typically inexpensive coverage relative to its value.
Before the First Spring Storm
Spring arrives quickly in northern Illinois, and flood season is rarely far behind. Before the first major storm of the season, take these steps:
Review your current homeowners policy and look for water and flood exclusions.
Check whether you carry a sewer backup or sump pump failure endorsement.
Look up your property on FEMA’s Flood Map Service Center (msc.fema.gov) to understand your designated flood zone.
Talk to your insurance agent about flood insurance options before the 30-day waiting period becomes a problem.
Add flood coverage well before storm season; with the waiting period, a policy bought after the forecast may not start in time. If you have questions about your current coverage or want to explore flood insurance options for your home in the northern Chicago suburbs, contact our office today for a complimentary policy review.
A Practical Water-Coverage Checklist for Northern Chicago Suburbs
Before spring storms arrive, homeowners in Wilmette, Evanston, Glenview, Northbrook, Northfield, Winnetka, Glencoe, Kenilworth, Skokie, and Highland Park should review five separate issues: roof and gutter condition, sump pump reliability, sewer backup exposure, finished-basement values, and whether the home has any separate flood exposure.
The policy question is not just whether “water damage” is covered. Insurance policies draw lines between sudden interior water, backup through drains, water entering from outside, groundwater, flood, and maintenance-related leaks. Those lines can determine whether a claim is covered, limited, or excluded.
Finished Basements Need Special Attention
A finished basement can turn a small water event into a major loss. Flooring, drywall, built-ins, furniture, electronics, exercise equipment, stored clothing, and mechanical systems can exceed a small water backup limit quickly. Homeowners should compare the limit to what is actually downstairs, not just accept a default amount.
If the basement has a sump system, also review backup power, battery condition, pump age, and whether the policy’s water backup endorsement addresses sump overflow or failure. The best time to find the gap is before the next storm, not while the cleanup crew is on the way.
Questions to Ask Your Insurance Agent
Ask: What water losses are covered by my homeowners policy? What is my water backup limit? Does my deductible differ by type of loss? Is flood insurance separate? Are finished-basement improvements and contents fully reflected? Are there maintenance or seepage exclusions I should understand?
Longmeadow Insurance helps homeowners translate those questions into plain English so they know which risks are insured, which risks are self-insured, and which risks may need a separate policy or endorsement.
Flood insurance in Chicago and on the North Shore is a separate policy from your homeowners coverage, so review it separately. Before choosing coverage, check the property address, how the lowest floor is used, and what the proposed policy covers for the building and belongings.
Why You Need Flood Insurance
Managing Your Risk
Standard homeowners insurance doesn’t cover flood damage. If heavy rainfall overwhelms storm sewers, if snowmelt causes the nearby creek to overflow its banks, or if water from Lake Michigan or the Skokie Lagoons reaches your basement, you have no coverage without flood insurance.
The North Shore has seen its share of significant rain events in recent years. Communities like Wilmette, Winnetka, and Highland Park have all dealt with flooding that’s left homeowners facing tens of thousands of dollars in damages. Your home is likely your largest financial asset, so it makes sense to protect it from flood.
Your Mortgage Lender Requires It
If your property is in a Special Flood Hazard Area (SFHA), which FEMA designates as a high-risk flood zone, and you have a federally backed mortgage, flood insurance is mandatory. Even if you’re not in a high-risk zone, your lender may still require coverage based on their own risk assessment. This requirement isn’t your bank being difficult. It’s protecting their investment in your property, which also happens to protect yours.
NFIP vs. Private Flood Insurance
For decades, the National Flood Insurance Program (NFIP) was essentially your only option. Backed by the federal government and administered through FEMA, the NFIP provides standardized flood coverage with premiums based on flood risk.
However, the private flood insurance market has grown significantly in recent years, and many homeowners now have choices.
NFIP Coverage offers policies up to $250,000 for your dwelling and $100,000 for contents. The program has standard terms, waiting periods (typically 30 days), and rates that are relatively consistent regardless of which insurance agent you work with. If you’re in a high-risk area with a mortgage requirement, NFIP coverage will satisfy your lender.
Private Flood Insurance can often provide higher coverage limits, more flexibility in terms, and potentially competitive pricing depending on your specific property and risk profile. Some homeowners find that private options offer better coverage for less money, particularly if their home has flood mitigation features or if they’re in a moderate-risk area. Not all private flood policies meet mortgage requirements, so confirm that before you switch.
The Homeowners Insurance Scenario: Coverage That Doesn’t Check All Boxes
Some insurers offer expanded water endorsements that go beyond ordinary sewer and sump backup. Compare the endorsement’s flood definition, basement limits, and deductible with a separate flood policy. If the lender requires flood insurance, confirm that it accepts the proposed coverage before relying on an endorsement.
The coverage is still worth having. It can work alongside a compliant flood policy, or as practical coverage for homeowners without a mortgage requirement who want protection against water damage.
Choosing Flood Coverage
The best approach depends on your specific circumstances. Start by determining whether you’re in a flood zone that triggers mandatory insurance requirements. We can help you check FEMA’s Flood Map Service Center online.
Then compare options. Get quotes for both NFIP and private flood policies. Ask specifically whether private policies will satisfy your mortgage requirements if that applies to you. And consider how add-ons like water backup coverage might work with your overall flood protection strategy.
The North Shore’s proximity to Lake Michigan, our network of creeks and drainage systems, and increasingly intense weather events all mean that flood risk is real here, even if it doesn’t feel like it until water is pooling in your finished basement.
Flood insurance is worth pricing even outside a mapped flood zone. If you have a mortgage, confirm that the policy you choose meets your lender’s requirement.
Why North Shore Flood Risk Is Different From Coastal Flood Risk
North Shore homeowners do not need to live on Lake Michigan to have meaningful flood exposure. In Wilmette, Evanston, Kenilworth, Winnetka, Glencoe, Northfield, Glenview, Northbrook, Skokie, and Highland Park, the more common problem is often inland water: heavy rain, overwhelmed storm sewers, blocked drains, window wells, grading problems, saturated soil, and water that enters at or below ground level.
That distinction matters because standard homeowners insurance generally treats “flood” differently from sudden interior water damage. A burst pipe, appliance leak, sewer backup, and stormwater entering through a foundation are not the same insurance problem. Homeowners who assume all water damage is handled by one policy are often surprised after a loss.
Flood Insurance vs. Water Backup vs. Seepage
Flood insurance is designed for certain rising surface-water events. Water backup coverage generally addresses water or sewage backing up through sewers, drains, or sump systems, subject to policy language and limits. Seepage, groundwater, maintenance problems, and long-term intrusion may be excluded or limited.
A good review separates these exposures instead of using one generic “water coverage” label. For many North Shore homes, the practical question is not simply “Do I need flood insurance?” but “What happens if rainwater enters the basement, the sump fails, the sewer backs up, or neighborhood drainage overwhelms the property?”
What to Review Before the Next Heavy-Rain Season
Homeowners should review flood zone information, basement finish level, sump pump setup, backup power, water backup limit, deductible, valuable property stored below grade, finished walls/flooring, mechanical systems in the basement, and whether flood insurance is available or advisable even when a lender does not require it.
Longmeadow Insurance can help compare the household’s current homeowners policy, available water backup options, and separate flood insurance possibilities so the homeowner understands where one form of coverage stops and another begins.
Short answer: Homeowners insurance generally covers sudden interior damage from an ice dam. Removal needed to stop covered damage can be treated differently from routine preventive removal. Photograph the damage, protect the affected area, and contact us about the next steps.
Ice dams can form when melted roof snow refreezes near the eaves and traps water behind it. This guide covers prevention, what to do when water gets inside, and the policy details to check before arranging repairs.
What Causes Ice Dams
An ice dam is a ridge of ice that forms at the edge of a roof and prevents melting snow from draining off properly. As snow continues to melt, the water backs up behind the dam and can seep underneath roof shingles, eventually leaking into your home’s interior.
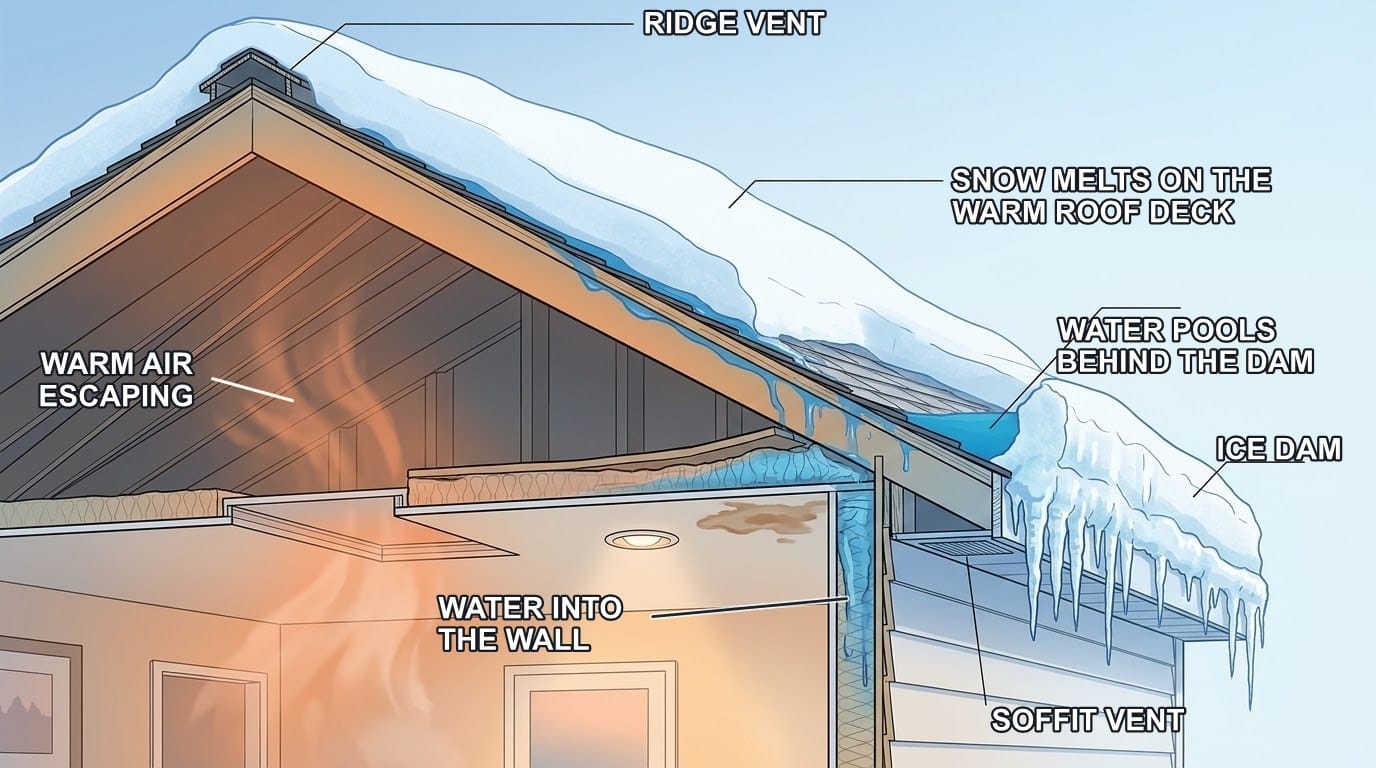
The formation process follows a predictable pattern. Heat from your home rises into the attic and warms the roof surface, even when outdoor temperatures remain below freezing. This heat causes snow on the upper portions of your roof to melt. As the meltwater flows down toward the colder eaves, which extend beyond the heated interior of your home, it refreezes, creating a growing dam of ice. With each freeze-thaw cycle, the dam grows larger, and the pool of water behind it deepens.
Warm air escaping into the attic melts the snow on the roof above. The meltwater refreezes where the roof passes beyond the heated wall, and the water trapped behind the dam finds its way into the wall and ceiling.
Several factors contribute to ice dam formation. Poor attic insulation allows excessive heat to escape through your roof. Inadequate attic ventilation traps warm air against the roof deck. Complex roof designs with multiple valleys and angles create areas where snow and ice accumulate. Even seemingly minor issues like recessed lighting fixtures or attic access hatches can create warm spots that trigger the melting process.
The Hidden Dangers of Ice Dams
The damage from ice dams extends far beyond what you can see from the ground. Water infiltration can saturate insulation, reducing its effectiveness and creating conditions for mold growth. Ceiling and wall damage manifests as staining, sagging drywall, and peeling paint. The constant freeze-thaw cycle can loosen or damage roof shingles, shortening your roof’s lifespan. Gutters filled with heavy ice can pull away from the fascia, causing structural damage. In severe cases, the weight of ice buildup can even compromise your roof’s structural integrity.
Perhaps most concerning is that much of this damage occurs hidden from view. By the time you notice water stains on your ceiling or walls, significant damage may have already occurred within your roof structure and insulation.
How to Prevent Ice Dams
Preventing ice dams comes down to keeping the roof cold and letting meltwater drain. The most effective strategies address the root cause: heat loss from your living space into the attic.
Start with your attic insulation. Current energy codes call for far more attic insulation than many older houses around Wilmette have. This thick blanket of insulation keeps heat where it belongs: in your living spaces. However, insulation alone isn’t enough. You need proper ventilation to maintain a cold attic space. A well-ventilated attic allows cold outdoor air to circulate, preventing the roof deck from warming above freezing.
Adequate ventilation typically requires both intake vents at the soffits and exhaust vents at or near the roof ridge. The general rule calls for one square foot of ventilation for every 150 square feet of attic space. Again, many of the older houses in our area do not have these modern designs. Ridge vents paired with soffit vents create natural airflow that keeps your attic temperature close to the outdoor temperature.
Sealing every potential air leak between your living space and attic helps. Common culprits include recessed lights, plumbing stacks, electrical wiring penetrations, and attic hatches. Even small gaps can allow significant heat loss. Use appropriate fire-rated sealants and weatherstripping to close these pathways.
Keeping your gutters clean throughout the fall and winter is another routine task. Clogged gutters contribute to ice dam formation by creating areas where water pools and freezes. While cleaning gutters in winter can be challenging, autumn maintenance pays dividends when cold weather arrives.
Consider installing heat cable along your roof’s edge. These electrical cables warm the roof enough to create channels for meltwater to drain safely. While they consume electricity and address the symptom rather than the cause, heat cables provide an additional layer of protection, especially for problem areas.
After heavy snowfalls, lower roof lines can benefit from a roof rake to remove snow from the lower three to four feet of the roof while standing safely on the ground. This eliminates the source material for ice dams. However, exercise caution to avoid damaging shingles or injuring yourself. Never attempt to climb on a snow-covered or icy roof.
What to Do If Ice Dams Form
Despite your best prevention efforts, ice dams can still develop during severe winter conditions. If you discover an ice dam forming on your roof, take action quickly to minimize damage.
First, address any active leaks inside your home. Place buckets to catch dripping water and move furniture and valuables away from affected areas. If water is actively flowing, this constitutes an emergency that may require professional intervention.
Without climbing onto the roof, you can create emergency channels for water drainage. Fill pantyhose or tube socks with calcium chloride ice melt and lay them vertically across the ice dam. This creates channels for water to escape without requiring you to climb onto your roof. Never use rock salt, which can damage your roof and landscaping.
Resist the temptation to chip away at ice dams with hammers, ice picks, or other sharp tools. This approach almost always causes more harm than good, damaging shingles and potentially creating more leak points. The risk of personal injury from falling ice or slipping is also significant.
For serious ice dam situations, contact a professional removal service. These specialists use low-pressure steam to safely melt ice without damaging your roof. While this service costs money, it’s far less expensive than repairing water damage to your home’s interior. If you can safely access your attic, consider using a box fan to blow cold air at the area where water is leaking through. This can freeze the water in place and temporarily stop the leak until you can arrange for proper ice dam removal.
Does Homeowners Insurance Cover Ice Dams?
Ice dam coverage under homeowners insurance policies can be complex, and many homeowners only learn the details after filing a claim. Understanding your coverage before problems arise helps you make informed decisions about prevention and response.
An ice dam can damage both the building and belongings. Dwelling coverage addresses covered repairs to walls, ceilings, and other building components; personal property coverage addresses damaged contents.
The key distinction involves sudden and accidental damage versus damage from neglect or lack of maintenance. If an ice dam forms during an unusually severe winter storm and causes water damage to your home, most policies will cover the resulting damage. However, if the ice dam formed because you failed to maintain your roof, gutters, or insulation, or if you ignored warning signs of developing problems, your insurer might deny the claim.
Covered interior water damage can include drywall, flooring, paint, and belongings under their respective coverages. Keep receipts for emergency work needed to stop further damage, including any ice removal. Routine preventive removal is a maintenance expense.
However, standard policies generally do not cover improvements or upgrades to prevent future ice dams. If your adjuster determines that inadequate insulation or ventilation caused your ice dam, the policy will cover repairing the immediate damage but won’t pay to upgrade your insulation to prevent future problems. Some insurers have started offering limited coverage for preventive improvements after a covered ice dam claim, recognizing this as a risk reduction measure.
Deductibles apply to ice dam claims just as they do to other types of claims. If your damage costs less than your deductible, you’ll pay out of pocket. Even when damage exceeds your deductible, you should consider whether filing a claim is worth a potential increase in your premiums.
Some insurance companies in our area have begun adding specific ice dam exclusions or limitations to policies. These might include seasonal coverage limitations, requiring proof of adequate insulation and ventilation, or imposing special deductibles for ice dam claims. Review your policy carefully and discuss any concerns with your insurance agent. Longmeadow Insurance can review your policy and show you alternatives.
Documenting Damage for Insurance Claims
If ice dams cause damage to your home, thorough documentation strengthens your insurance claim. Take photographs and videos of the ice dams on your roof, showing their location and size. Document any visible water damage inside your home, including stains on ceilings and walls, damaged flooring, and affected personal property. Keep receipts for any emergency repairs you make to prevent further damage. You can report the claim through us, and we will help you work out the next steps.
Note the dates when you discovered the ice dam and when the damage occurred. If possible, photograph or document weather conditions during the relevant period. Your insurance company may want to verify that the damage resulted from a specific weather event.
Contact your insurance company or agent as soon as you discover damage. Most policies require prompt notification of claims. Be honest and complete in describing the situation. Your adjuster will assess the damage and determine coverage, but providing thorough initial documentation helps the process move smoothly.
The Cost-Benefit Analysis of Prevention
Some homeowners hesitate to invest in prevention, viewing attic insulation and ventilation improvements as expensive. However, the math strongly favors prevention over repair.
Professional ice dam removal typically costs several hundred to several thousand dollars, depending on the severity. Water damage repairs often run into tens of thousands of dollars when you factor in drywall replacement, repainting, flooring repairs, and addressing any mold issues (which often have limited coverage). Insurance claims can lead to increased premiums that cost you money for years.
In contrast, improving attic insulation and ventilation might cost a few thousand dollars but provides benefits beyond ice dam prevention. Better insulation reduces heating and cooling costs, potentially saving hundreds of dollars annually. Nicor and ComEd often offer rebates for insulation upgrades and weatherproofing, reducing your out-of-pocket expense. The improvements increase your home’s value and reduce the likelihood of many types of weather-related damage.
Keep the Attic Cold and Read Your Policy Before Winter
Ice dams represent a significant threat to your home and your finances, but they’re largely preventable through proper maintenance and home improvements. Focus on keeping your attic cold through adequate insulation and ventilation, maintain your gutters, and address any heat loss pathways between your living space and attic.
If ice dams do form despite your best efforts, act quickly to minimize damage and contact professionals when needed.
Prevention costs less than repairs. Before winter, fix the attic insulation and ventilation, clean the gutters, and read the ice dam and water damage terms in your policy. If you want a second opinion on those terms, send us your declarations page.
Frequently Asked Questions
Does homeowners insurance cover ice dams?
Yes, most standard homeowners insurance policies cover the interior damage caused by ice dams, such as water leaking through the roof into walls, ceilings, and floors. However, the policy typically will not pay for the actual removal of the ice dam itself unless removal is necessary to prevent further covered damage.
Does homeowners insurance cover ice dam removal?
Generally, ice dam removal is only covered when an active ice dam is causing damage to the interior of your home and removal is needed to stop that damage. Preventive removal before any damage occurs is usually considered maintenance and is not covered.
Does homeowners insurance cover roof leaks from ice dams?
Yes, if an ice dam causes water to back up under your shingles and leak into your home, the resulting interior damage to drywall, insulation, paint, and flooring is typically covered. However, the cost to repair or replace the roof shingles themselves may not be covered if the insurer determines the roof was already in poor condition.
Does homeowners insurance cover water damage from ice dams?
Water damage from ice dams is generally covered under the dwelling and personal property sections of your homeowners policy. This includes damaged drywall, carpet, hardwood floors, furniture, and electronics. Mold remediation may have limited coverage depending on your policy.
Will filing an ice dam claim raise my insurance premiums?
It can. Filing a claim may lead to a premium increase at renewal, especially if you have had prior claims. For smaller amounts near your deductible, it may be more cost-effective to pay out of pocket. Talk to your agent before filing to weigh the long-term cost.
Are ice dam prevention improvements covered by insurance?
No. Standard homeowners policies do not pay for improvements like adding insulation, ventilation, or heat cables. These are considered home maintenance and upgrades. However, some insurers offer limited coverage for preventive improvements after a covered ice dam claim as a risk-reduction measure.
How do I document ice dam damage for an insurance claim?
Photograph the ice dam on your roof from the ground, document all interior damage with photos and video, keep receipts for emergency repairs, and note the dates when damage was discovered. Contact your insurance agent as soon as possible: most policies require prompt notification.
What should I do if I have an ice dam right now?
Move belongings away from active leaks and catch dripping water where it is safe to do so. Arrange professional roof and ice-dam help rather than climbing onto an icy roof or chipping at the ice. Photograph the damage and keep emergency-work receipts.
Why Ice Dams Create Both Prevention and Claim Questions
Ice dams are partly a home-maintenance issue and partly a weather-loss issue. Poor attic insulation, ventilation, clogged gutters, roof design, snow accumulation, and freeze-thaw cycles can all contribute. Insurance may respond to sudden covered damage, but it is not a substitute for correcting the conditions that caused recurring ice dams.
Homeowners should document the event, mitigate active leaks, photograph damage, keep receipts, and avoid permanent repairs until the claim process is clear. They should also review whether interior water damage, roof damage, mold, repeated seepage, and maintenance-related issues are treated differently by the policy.
North Shore Homes With Older Roofs and Finished Interiors Need Extra Care
Many homes in Wilmette, Winnetka, Glencoe, Kenilworth, Evanston, and nearby communities have older roofs, dormers, complicated rooflines, additions, and finished upper floors. Those features can make ice-dam prevention and repair more complicated.
After an ice-dam event, the insurance conversation should include the deductible, claim size, whether mitigation is needed, whether the roof or interior damage is covered, and whether preventive improvements are separate from the covered repair.