
High-Value Home Insurance on Chicago’s North Shore
Coverage at a Glance
Select a part of the property, a numbered marker, or a coverage name below the picture to see how each coverage fits into a coordinated plan.
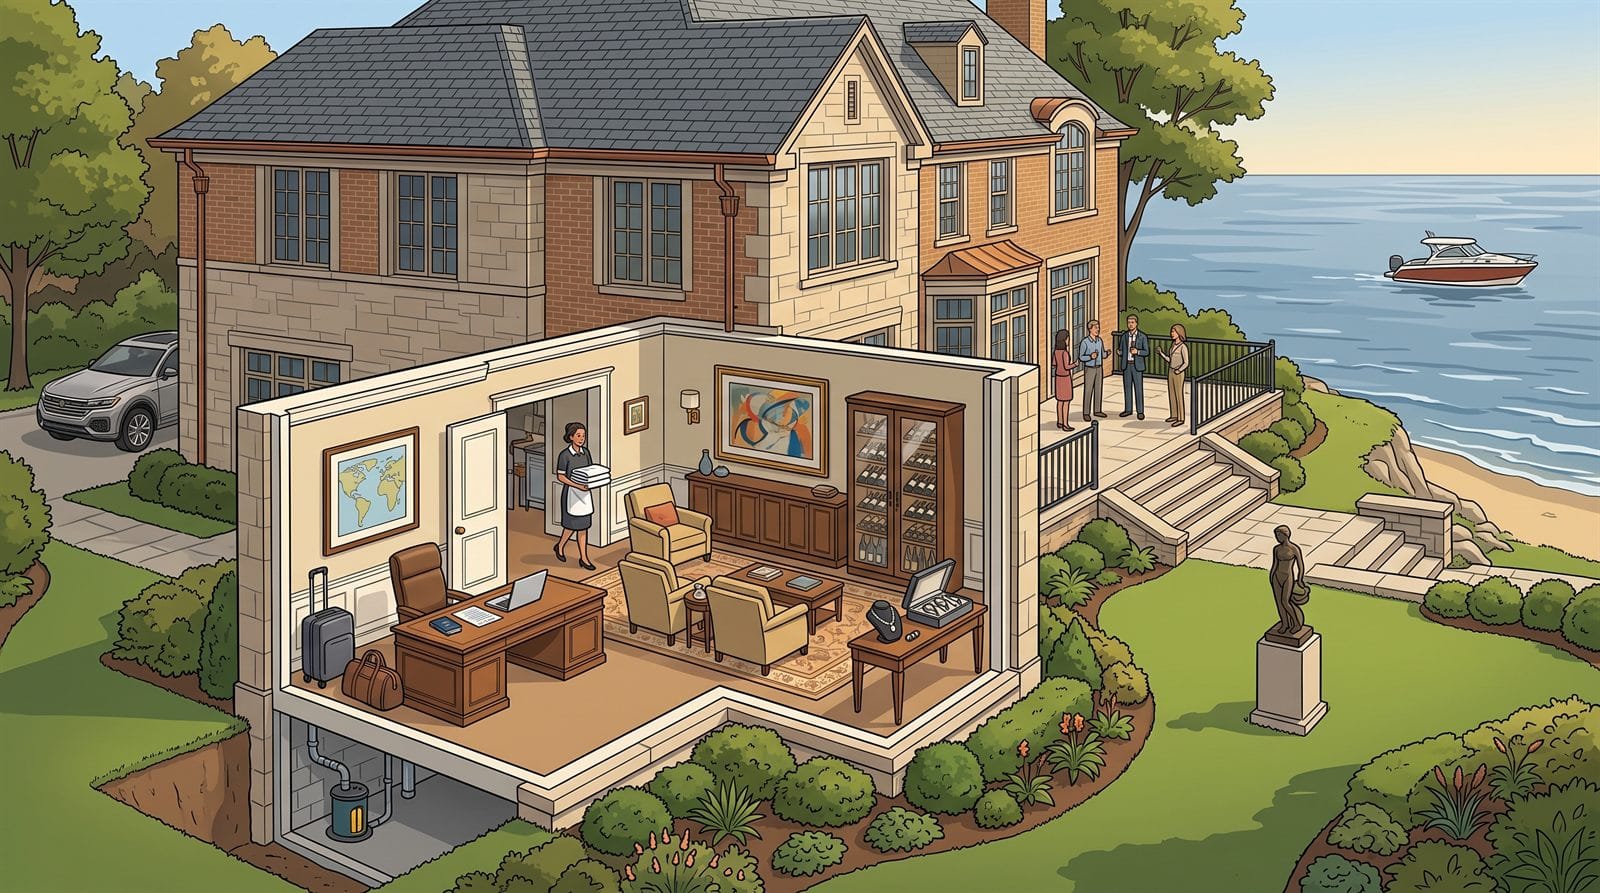
- High-value dwelling coverage
Could you rebuild the details that make this home yours?
Custom millwork, stonework, slate, and architectural details can make reconstruction more expensive than expected. High-value homeowners coverage can offer broader rebuilding protection and specialist support. Ask about replacement cost provisions, code upgrades, and how your home’s distinctive materials would be restored.
- Contents and furnishings
Your furnishings deserve more than a rough estimate.
Custom furniture, rugs, and household belongings can represent a significant investment. Review replacement cost coverage and your contents limit against what you actually own. Some pieces may be better protected as scheduled valuables, particularly antiques and collectible furnishings.
- Fine art coverage
Fine art needs its own valuation and coverage.
Specialized fine art coverage can address accidental damage, theft, transit, and other collection risks more broadly than ordinary contents insurance. Ask how the policy handles agreed values, restoration, and any loss in value after repair. Keep valuations current as your collection changes.
- Outdoor art and sculpture
Outdoor art has its own exposures.
An outdoor sculpture faces weather, falling branches, theft, and accidental damage. Make sure it is specifically considered in your collection coverage, including its location and installation. Ask about transit and handling protection when the piece is moved or loaned.
- Jewelry and watches
Wear your valuables with the right protection.
Specialized jewelry coverage can provide protection for theft, accidental damage, and accidental loss, including while traveling. Ask about worldwide coverage, valuation, newly purchased items, and deductibles. A standard homeowners jewelry limit may be far below the value of your collection.
- Travel and worldwide coverage
Does your protection travel with you?
Some personal liability and valuables policies provide worldwide protection, but overseas medical care, emergency evacuation, trip cancellation, and rental-car risks need separate review. Before you travel, let’s check your destinations, activities, and existing policies so ‘worldwide coverage’ means what you expect.
- Personal cyber and fraud
A convincing email can put family assets at risk.
Personal cyber and fraud coverage may help with qualifying identity theft, cyber extortion, account compromise, or fraudulent transfers. These protections vary significantly. Ask specifically about impersonation scams and payments you were tricked into authorizing, along with response services and coverage limits.
- Wine collection coverage
A failed cooling system can damage a collection.
Specialized wine coverage can protect against qualifying breakage, theft, and spoilage, including certain temperature-control failures. Ask about storage requirements, transit, valuation, and newly acquired bottles. Ordinary homeowners coverage may not address the full range of collection losses.
- Personal excess liability
A serious liability claim can reach beyond your home.
Personal excess liability coverage can add protection above specified home, auto, and watercraft policies. Review limits against your family’s assets and exposures, and confirm that homes, vehicles, boats, and relevant household members are properly included. Defense provisions and exclusions matter, too.
- Watercraft coverage
Your boat needs protection built for boating.
Dedicated watercraft coverage can address damage to the vessel and liability arising from its use. Review the insured value, navigation territory, operators, towing, salvage, and pollution provisions. Coordinate the boat policy with your excess liability coverage before taking guests aboard.
- Flood and shoreline coverage
Lakefront property needs a separate water-risk review.
Homeowners insurance generally excludes flood damage. Review private or excess flood options alongside coverage for shoreline structures. Erosion, bluff movement, seawalls, and beach stairs involve distinct exclusions and conditions. Neither home nor flood insurance automatically protects everything along the water.
- Water backup and interior water damage
A basement water loss can become a major restoration project.
Review sewer and drain backup, sump overflow, and interior water-damage coverage separately from flood insurance. Limits should reflect your finishes, equipment, and belongings. Ask about automatic water shutoff devices and leak detection to help reduce the chance of a major loss.
- Household employees
Employing household staff creates additional responsibilities.
A nanny, housekeeper, or other household employee can create exposures beyond ordinary homeowners liability. Review workers’ compensation and employment practices liability, including claims involving workplace injury, discrimination, or wrongful termination. Tell us who employs the staff and what duties they perform.
- Auto coverage coordination
Coordinate your vehicles with the rest of your protection.
Review auto liability limits alongside your excess policy, and ask about repair parts, vehicle valuation, and rental reimbursement. Tell us about household drivers and any vehicles titled to a trust or entity so we can check how ownership and use affect coverage.
- Additional living expense
Could you maintain your routine while your home is rebuilt?
After a covered loss makes your home unlivable, additional living expense coverage can help with suitable temporary housing and other eligible increases in spending. Review the coverage period and limits with the realities of restoring a custom home in mind.
Send us your homeowners, auto and umbrella declarations pages, and we will show you where they leave gaps between them.
Illustrative coverage options; multiple policies or endorsements may be required. Availability, limits, deductibles, and exclusions vary.
Custom construction, expensive finishes, and unusual restoration needs can make a specialized homeowners policy a better fit. We compare the rebuilding estimate and coverage features with the home itself; each insurer sets its own eligibility requirements.
Longmeadow Insurance places high-value homeowners coverage, also called high net worth or luxury home insurance, from our Wilmette office for households in Winnetka, Kenilworth, Glencoe, Highland Park, Northfield, and along the Wilmette lakefront. We work with the carriers built for this market rather than stretching a standard form to fit.
What Changes at This Level
The differences show up in five places.
- Extended or guaranteed replacement cost. Extended coverage adds a stated cushion above the dwelling limit. Guaranteed coverage pays eligible rebuilding costs beyond it when the policy’s rebuilding requirements are met.
- No depreciation on the house. Covered losses settle at replacement cost, and scheduled collections can carry agreed values, so there is no argument about actual cash value at the worst possible moment.
- Valuables coverage. Standard policies often limit jewelry theft and certain other losses. High-value programs can offer blanket collection coverage or individual schedules, with the limits and settlement method chosen for what you own.
- Cash settlement options. If you decide not to rebuild, some high-value carriers will pay the claim in cash rather than requiring reconstruction.
- Claims handling built for complexity. Adjusters who have handled slate roofs, plaster restoration, and custom millwork before, rather than learning on your house.
Why Rebuild Cost Is Understated Here
A high-value home deserves a rebuilding estimate that accounts for its actual materials, finishes, and skilled labor. We review those details and recent renovations instead of relying on square footage alone.
A 1920s North Shore colonial with plaster walls, quarter-sawn oak trim, leaded glass, a slate or tile roof, and custom cabinetry cannot be rebuilt with builder-grade materials. Neither can a lakefront property with architectural detail that no longer has a mass-market equivalent. Material costs, skilled trade labor, and building code requirements have all moved substantially since 2020, and dwelling limits generally have not moved with them.
A formal replacement cost appraisal settles this properly. We arrange or facilitate one as part of the review rather than accepting a generic estimate.
Liability Is the Larger Exposure
A household with a home in this range typically carries $300,000 to $500,000 of personal liability, which is the number a standard policy defaults to. Set against the assets, retirement accounts, and future earnings of a North Shore family, that limit is not a serious figure.
The specific factors that raise this exposure are predictable: teenage drivers, a swimming pool, dogs, household staff, frequent entertaining, rental property, and service on association or nonprofit boards. Each one is a path to a claim that reaches past the underlying limit. An umbrella policy is the correction, and at $150 to $350 a year for the first million it is usually one of the least expensive parts of the program.
Board service needs its own look. Umbrella policies treat it differently: some cover unpaid work on a nonprofit board, some limit it, and some exclude it. If you sit on a school foundation, church, club, or charity board, compare your umbrella’s wording with the organization’s directors and officers policy. We read both when you send them.
Adding a Teenage Driver
For New Trier and Loyola Academy families, adding a young driver is usually the single largest near-term change to the insurance program. It raises auto premium sharply, and more importantly it raises the ceiling on what a liability claim can cost.
The structural answer is rarely to buy the highest possible auto liability limit, which gets expensive quickly. It is to hold sensible auto limits and put an umbrella above them, then work the available discounts: driver education completion, good student status, vehicle selection, and telematics programs where the household is comfortable with them. See our auto insurance page for how we structure this.
What a High-Value Household Review Covers
Above a certain level of assets, the risks stop being a list of separate policies and start being one connected picture. A teenage driver, a lake house, a household employee, and a jewelry collection look like four separate purchases, but the first three all add to the same family’s liability, and all four should be underwritten together.
This is what we work through on a household review, in roughly this order.
1. Rebuild cost, properly estimated
Guaranteed or extended replacement cost rather than a flat dwelling limit, with the estimate built from the actual construction: plaster, millwork, stone, custom cabinetry, and slate or tile roofing. Formula-driven estimates calibrated to average construction systematically understate North Shore homes.
2. Valuables and collections
Jewelry, watches, fine art, wine, silver, and firearms deserve an item-by-item coverage review. Scheduling gives a listed item its own limit and can add accidental-loss protection. Compare the deductible and agreed-value or replacement-cost terms, and keep appraisals current. See our guide to documenting what you own.
3. Household employees
A nanny, housekeeper, or caregiver you schedule and direct is your employee, and Illinois generally requires workers compensation. Homeowners liability commonly excludes injury to a residence employee where comp is required, so the policy families assume covers it specifically does not. Some carriers can endorse it; others require a separate policy.
4. Entity and trust ownership
Homes held in a revocable trust are routine and usually just need the trust named. Irrevocable trusts and LLCs change the risk profile and can restrict carrier availability or trigger a commercial form. The failure mode is titling the property and never telling the insurer.
5. Second homes, watercraft, and collector vehicles
A Wisconsin lake house, a boat that moves between states, and a car driven a few thousand miles a year each need their own treatment, and each needs the umbrella above them checked. See boat and watercraft insurance and classic car insurance.
6. Personal cyber and fraud
Available by endorsement on most high-value programs and rarely asked about. Depending on the form, it can cover wire fraud on a real estate closing, ransomware on home systems, identity restoration, and cyberbullying or extortion. The wire fraud piece alone justifies the conversation for anyone buying or selling property.
7. Excess liability sized to the balance sheet
Set umbrella limits using the household’s assets, income exposure, drivers, and properties. Keep home, auto, boat, and rental liability at the levels required by the umbrella; falling short can leave an out-of-pocket gap. Review the whole arrangement when a teen starts driving.
What You Get at the End
A written summary of where your current program sits against each of those seven, what a claim would actually pay in the two or three scenarios most likely for your household, and pricing from the carriers that write this class of business rather than a single company’s answer.
Send your current homeowners, auto, and umbrella declarations pages along with any appraisals. Call or text 847.242.1040 or start online.
When to Revisit the Program
We review a high-value program on a regular cadence, because a household’s exposures and the insurance market both change. Some changes should not wait for the next review:
- A renovation or addition, before work starts
- Buying a second home, a boat, or a collector car
- A major jewelry or art purchase, or inheriting either
- A new driver in the household
- Hiring a nanny, housekeeper, or caregiver
- Moving a home or car into a trust or LLC
- Joining a nonprofit or association board
Working With Your Advisors
Your insurance should match your estate plan, your tax planning, and the way your assets are held. When a home is deeded to a trust, a business is sold, or an estate plan is rewritten, the policies usually need to change at the same time. With your permission, we work directly with your financial advisor, estate attorney, and CPA so the coverage matches the plan. Advisors can see how we work with them.
If You Have a Claim
Call us before you file. Talking a loss through with us is free, and we do not report the call to the carrier unless you decide to file.
If you do file, we help you report it, read the adjuster’s letters against the policy language, and raise it with the carrier when an answer does not match the policy. The insurance company decides the claim, not us, but you will not be reading the policy alone.
Common Questions
At what value does a high-value policy make sense?
Rebuild cost matters more than market value. Custom materials, historic details, and specialist labor can make high-value coverage useful even when the sale price is lower than a carrier’s usual target market.
Is high-value coverage more expensive?
Not always. These carriers underwrite a lower-loss population and price accordingly, so the broader coverage can come in close to a standard premium. We quote both so the comparison is explicit rather than theoretical.
Do I need to schedule my jewelry and art individually?
Often not. Many high-value forms cover collections on a blanket basis up to a limit, which avoids appraising every piece. Individual items above a threshold still benefit from scheduling, which usually also removes the deductible for that item.
What about a home held in a trust or LLC?
Common at this level and entirely workable, provided the titling is reflected correctly on the policy. A home deeded to a trust with the policy still in an individual name creates an avoidable coverage argument at claim time.
I’m already with a high-net-worth carrier. Is a review still worth it?
Usually. Being with a carrier built for this market does not mean the dwelling limit, the valuables schedule, or the umbrella were set correctly for your household. We read the declarations pages either way and tell you what we find.
Related Coverage
- Home insurance, the standard-market overview
- Umbrella insurance for liability above the underlying limits
- Auto insurance, including households adding a young driver
- Classic car insurance for collector and antique vehicles
- Condo insurance for high-value units and lakefront buildings
- Life insurance for estate liquidity and wealth transfer
Where We Write High-Value Coverage
We place this coverage from our main office in Wilmette, serving Winnetka, Kenilworth, Glencoe, Highland Park, Northfield, Northbrook, and Glenview.
Request a Coverage Review
Send us your current declarations page. We will tell you how much of the house your dwelling limit would rebuild, where the valuables sublimits sit, and whether your liability structure matches what the household has at stake. Call 847.242.1040 or request a quote online.