
Older homes in Evanston, Wilmette, Winnetka, Kenilworth, Glencoe, Northfield, and nearby communities often have plaster walls, hardwood floors, custom trim, masonry, slate roofs, additions, and finished basements. Those features cost more to rebuild than standard construction, which makes the insurance review more important.
A policy for an older home should not be built from a rough online estimate alone. It should consider rebuilding cost, updates, roof age, ordinance requirements, water exposure, and the real cost to repair unique features after a covered loss.
On this page
- Replacement cost is not the purchase price
- Document updates before underwriting asks
- Roof age and roof material deserve attention
- Basements and water backup are a major North Shore issue
- Ordinance or law coverage can be critical
Replacement cost is not the purchase price
The dwelling limit should reflect the cost to rebuild, not what the home would sell for. Older homes may include materials and craftsmanship that are expensive to reproduce. An insurance limit above the market value can still be correct.
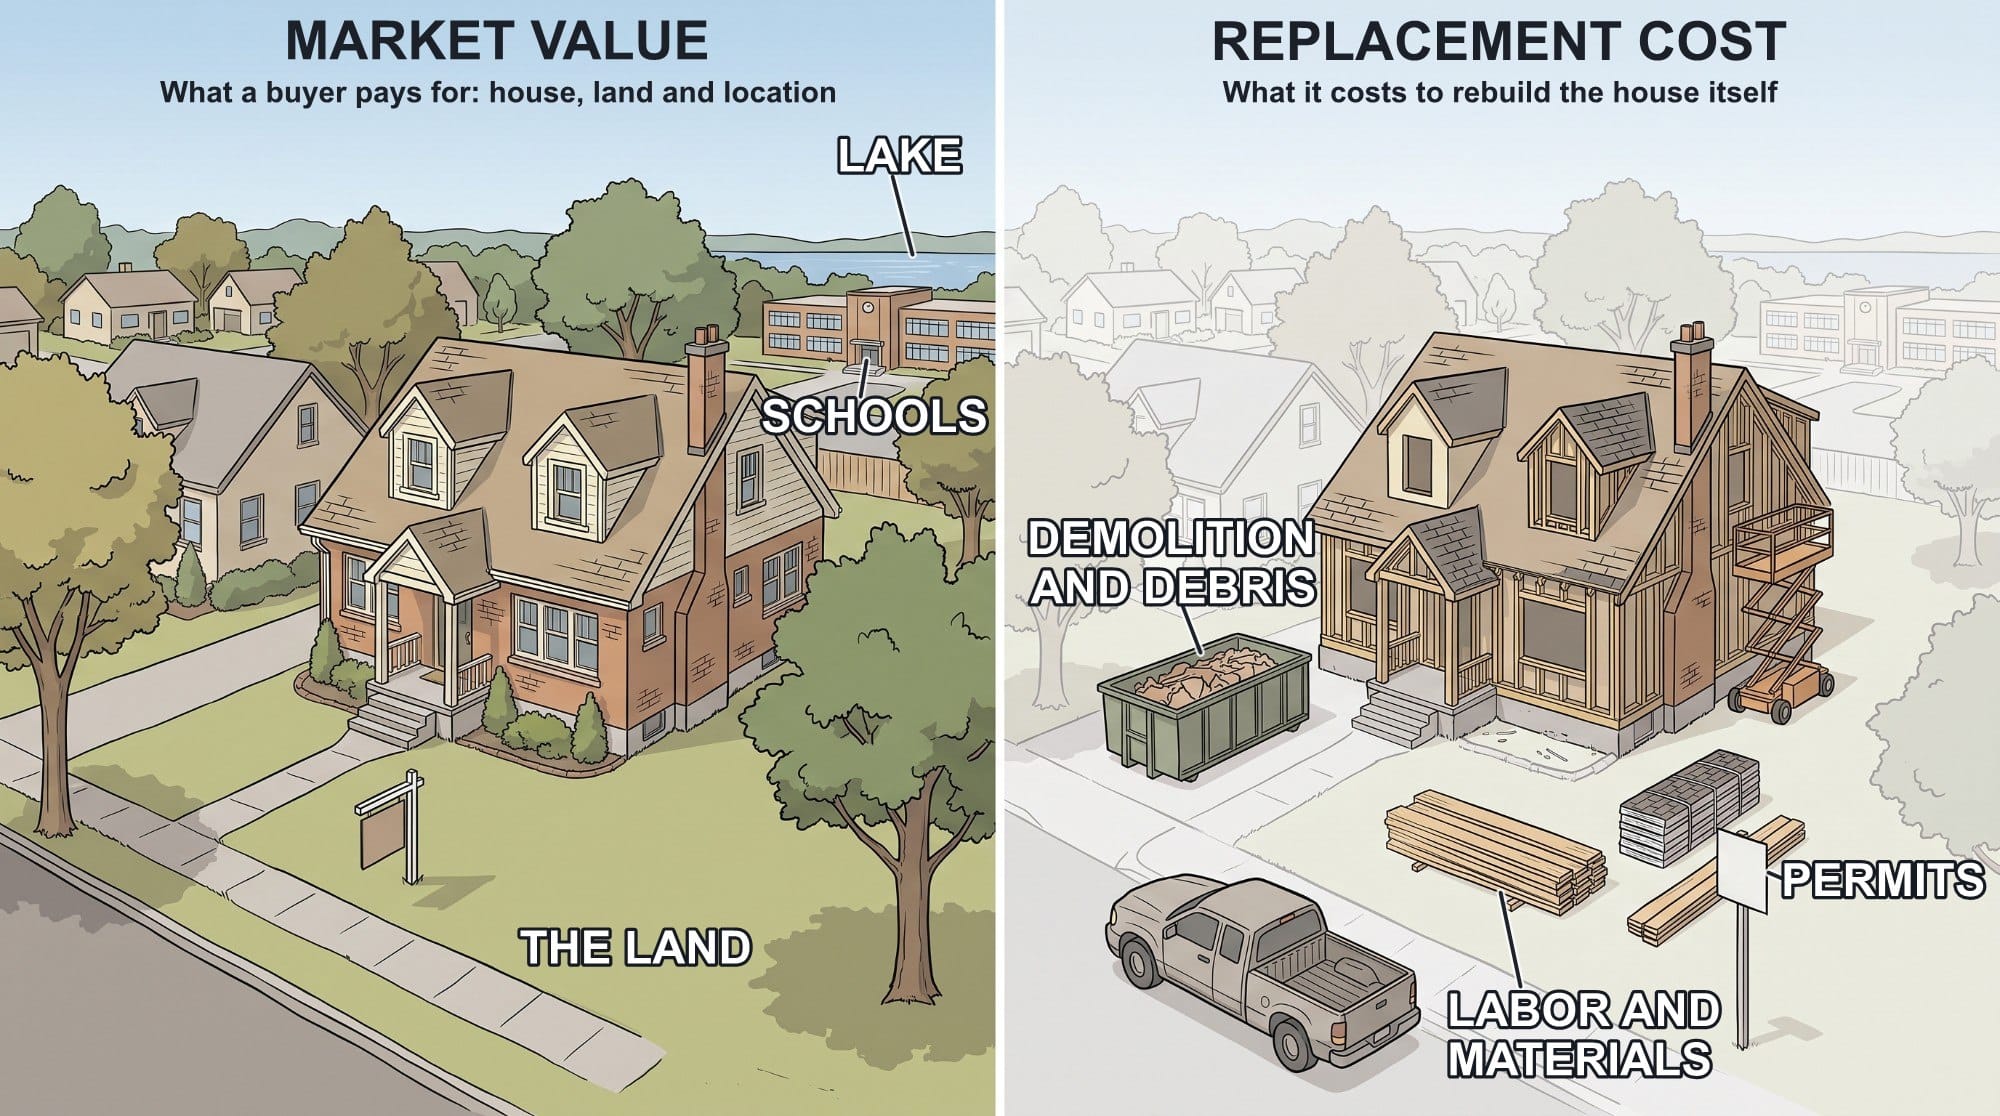
Review extended replacement cost, inflation protection, debris removal, and ordinance or law coverage. These details matter after a major fire, storm, or water loss.
Document updates before underwriting asks
Carriers often ask about roofs, wiring, plumbing, heating, and renovations. If the home has been updated, keep invoices, permits, inspection reports, and photos. Documentation can help show that an older home has been maintained and modernized.
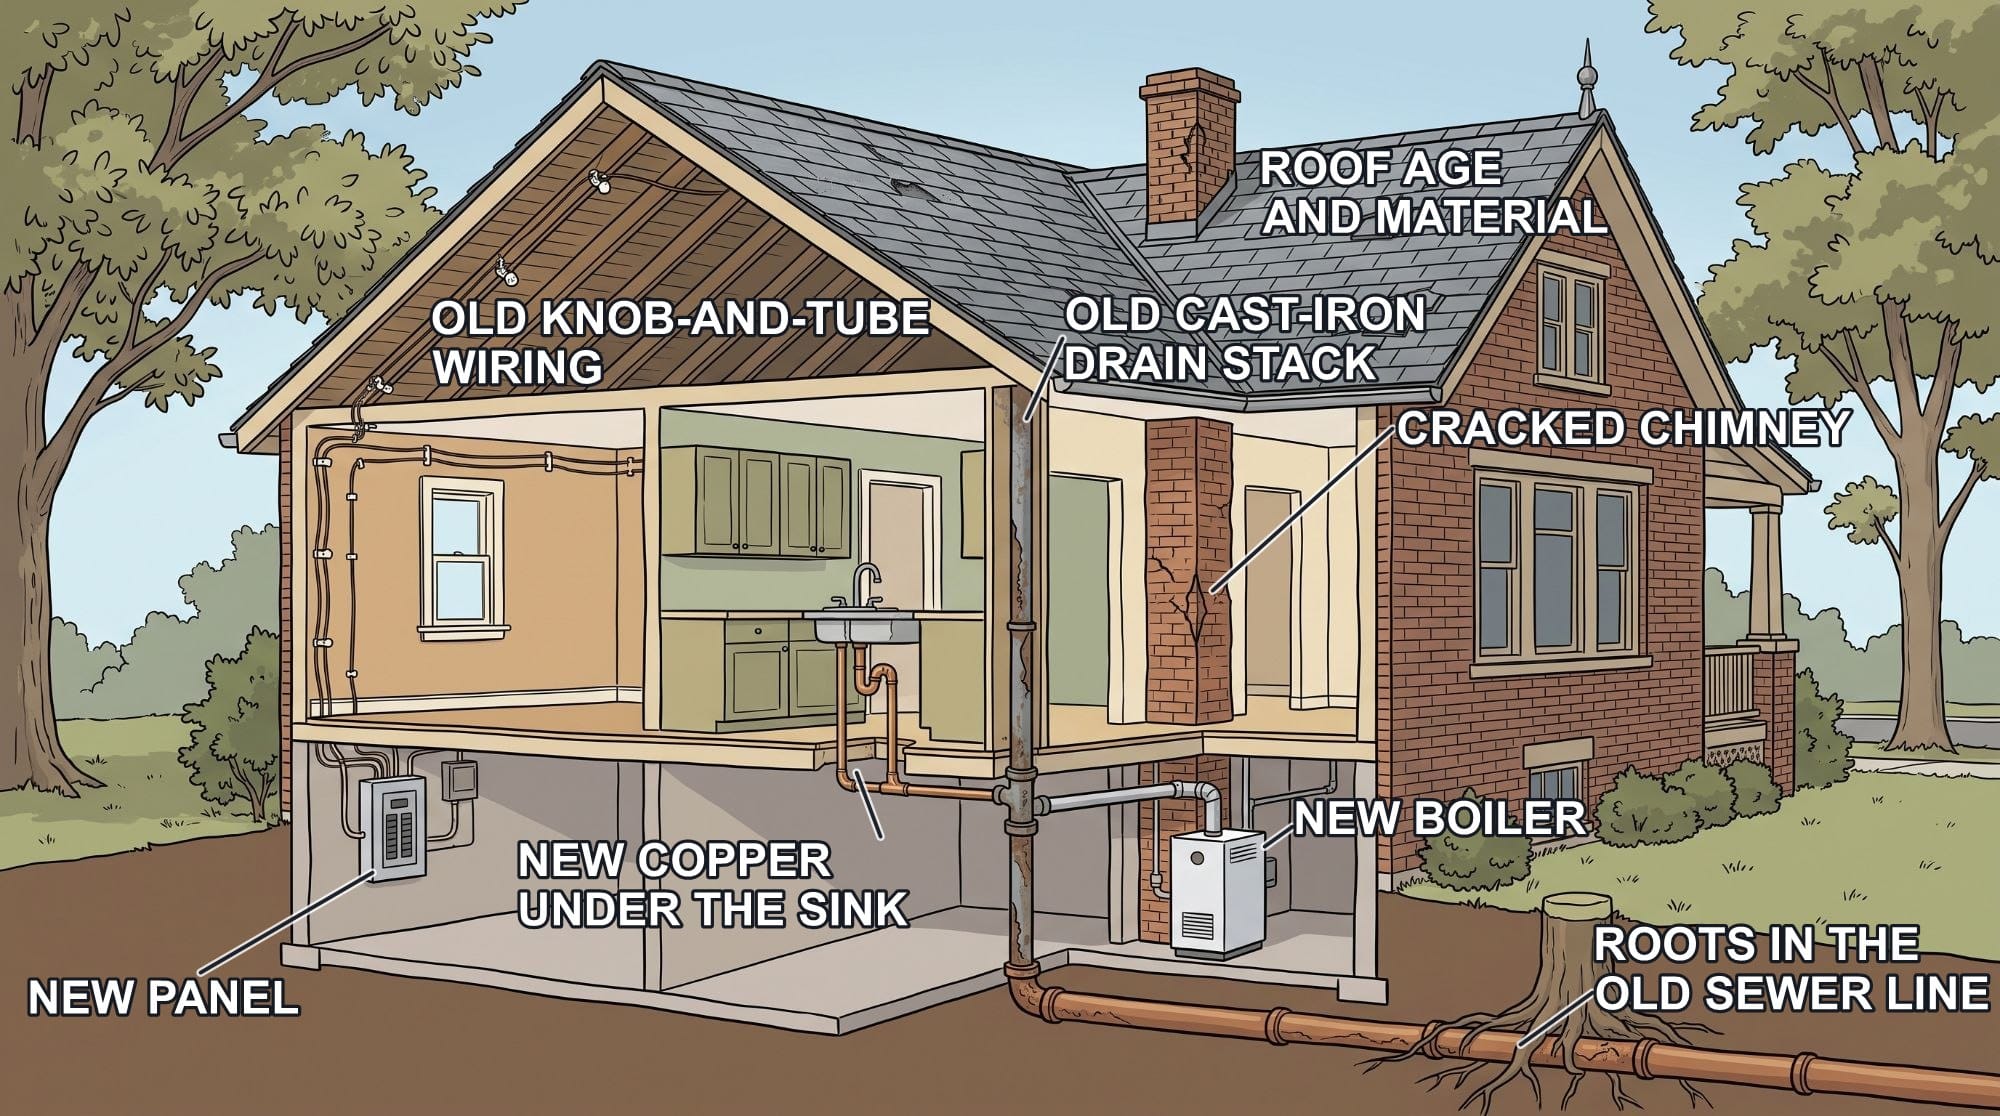
Without documentation, underwriting may assume the worst or ask for additional inspection information.
Roof age and roof material deserve attention
Roof questions are common for older homes. Asphalt, slate, tile, flat, and specialty roofs can all be treated differently. A beautiful roof may still create underwriting questions if age, condition, or repair history is unclear.
Ask how the policy would settle a covered roof claim and whether age affects replacement cost eligibility.
Basements and water backup are a major North Shore issue
Many older homes have basements that are used as living space, offices, playrooms, gyms, or storage. Sewer backup, sump failure, seepage, and flood are not the same coverage issue.
Review water backup limits and flood options before heavy rain exposes a gap. A finished basement can exceed a small endorsement limit quickly.
Ordinance or law coverage can be critical
If a covered loss requires reconstruction, current building codes may require upgrades that were not part of the original home. Ordinance or law coverage can help with some of those increased costs depending on the policy.
This can matter for electrical, plumbing, structural, energy, and safety requirements.
What Underwriting Will Ask About a Pre-War House
Carriers do not price an older home on its age. They price it on four systems, and they want dates rather than adjectives. Having the answers ready is the difference between a clean quote and a file that sits in referral for a week.
- Electrical. Year of the last service upgrade and the panel’s amperage. Knob and tube wiring, cloth-insulated wiring, and fuse boxes each narrow the carrier list sharply, and a few will decline outright.
- Plumbing. What the supply lines are made of and when they were replaced. Galvanized steel and any remaining lead service line matter more than the fixtures.
- Heating. Age and type. An original gravity furnace or an oil tank, buried or not, changes both eligibility and price.
- Roof. Year of the last full tear-off, not the year of the last repair. Layers matter too, since a second layer over the first limits your options.
Gather permits, invoices, or even dated photographs before you shop. On a house built before 1940, an undocumented update is treated by most underwriters as an update that did not happen.
Where Older North Shore Homes Are Underinsured
The recurring gap is not the dwelling limit alone. It is everything the dwelling limit does not reach: plaster restoration priced as drywall, original millwork and leaded glass valued as stock trim, slate or tile roofing replaced in the estimate with asphalt, and detached garages carried at a default ten percent of the dwelling figure that has not been checked in years.
Ask your agent to show you how the replacement cost estimate was built rather than what number it produced. If the inputs describe average construction, the output will too, and the shortfall only becomes visible after a loss.
Frequently asked questions
Is an older home harder to insure?
Not always, but carriers may ask more questions. Updates, maintenance, and documentation help.
Should I insure my home for market value?
No. Home insurance should focus on rebuilding cost, not land value or purchase price.
Do older homes need water backup coverage?
Many do, especially if there is a basement, sump pump, floor drain, or older sewer connection.
Talk with a local independent insurance agency
Longmeadow Insurance can help Evanston, Wilmette, and North Shore homeowners review coverage for older homes, renovations, roof terms, water backup, and replacement cost concerns. To start a review, use our get a quote form or call 847.242.1040.
Coverage We Write
- Home insurance on the North Shore
- Flood and water backup coverage
- Umbrella insurance
- Personal insurance overview
Call 847.242.1040 or request a quote online.