
If an inspection image is cited in a non-renewal notice, ask for the image, the specific concern, and the response deadline. Current photographs, repair records, and an inspection may help you address inaccurate or outdated information.
The Shift from Clipboards to Satellites
Insurance underwriting has always involved assessing the physical condition of a home. For decades, that meant sending someone out to look at the property, take a few photos, and file a report. It was slow, expensive, and inconsistent. Two different inspectors looking at the same house might come to very different conclusions. Starting around 2018, carriers began experimenting with aerial and satellite imagery as a supplement to traditional inspections. By 2023, the practice had become mainstream. Today, most major carriers and many regional ones use some combination of satellite photos, drone imagery, and AI-driven image analysis to evaluate properties during the underwriting and renewal process. The technology behind this shift is surprisingly sophisticated. High-resolution optical satellites capture detailed images of rooftops, yards, and surrounding areas. Multispectral sensors can detect things invisible to the naked eye, like the moisture content of roofing materials or the health of surrounding vegetation. Synthetic Aperture Radar (SAR) technology works through cloud cover and at night, providing continuous monitoring capability regardless of weather conditions. When you layer AI and machine learning on top of all that imagery, carriers can analyze thousands of properties in the time it once took to inspect a single home.
What Exactly Are Insurers Looking For?
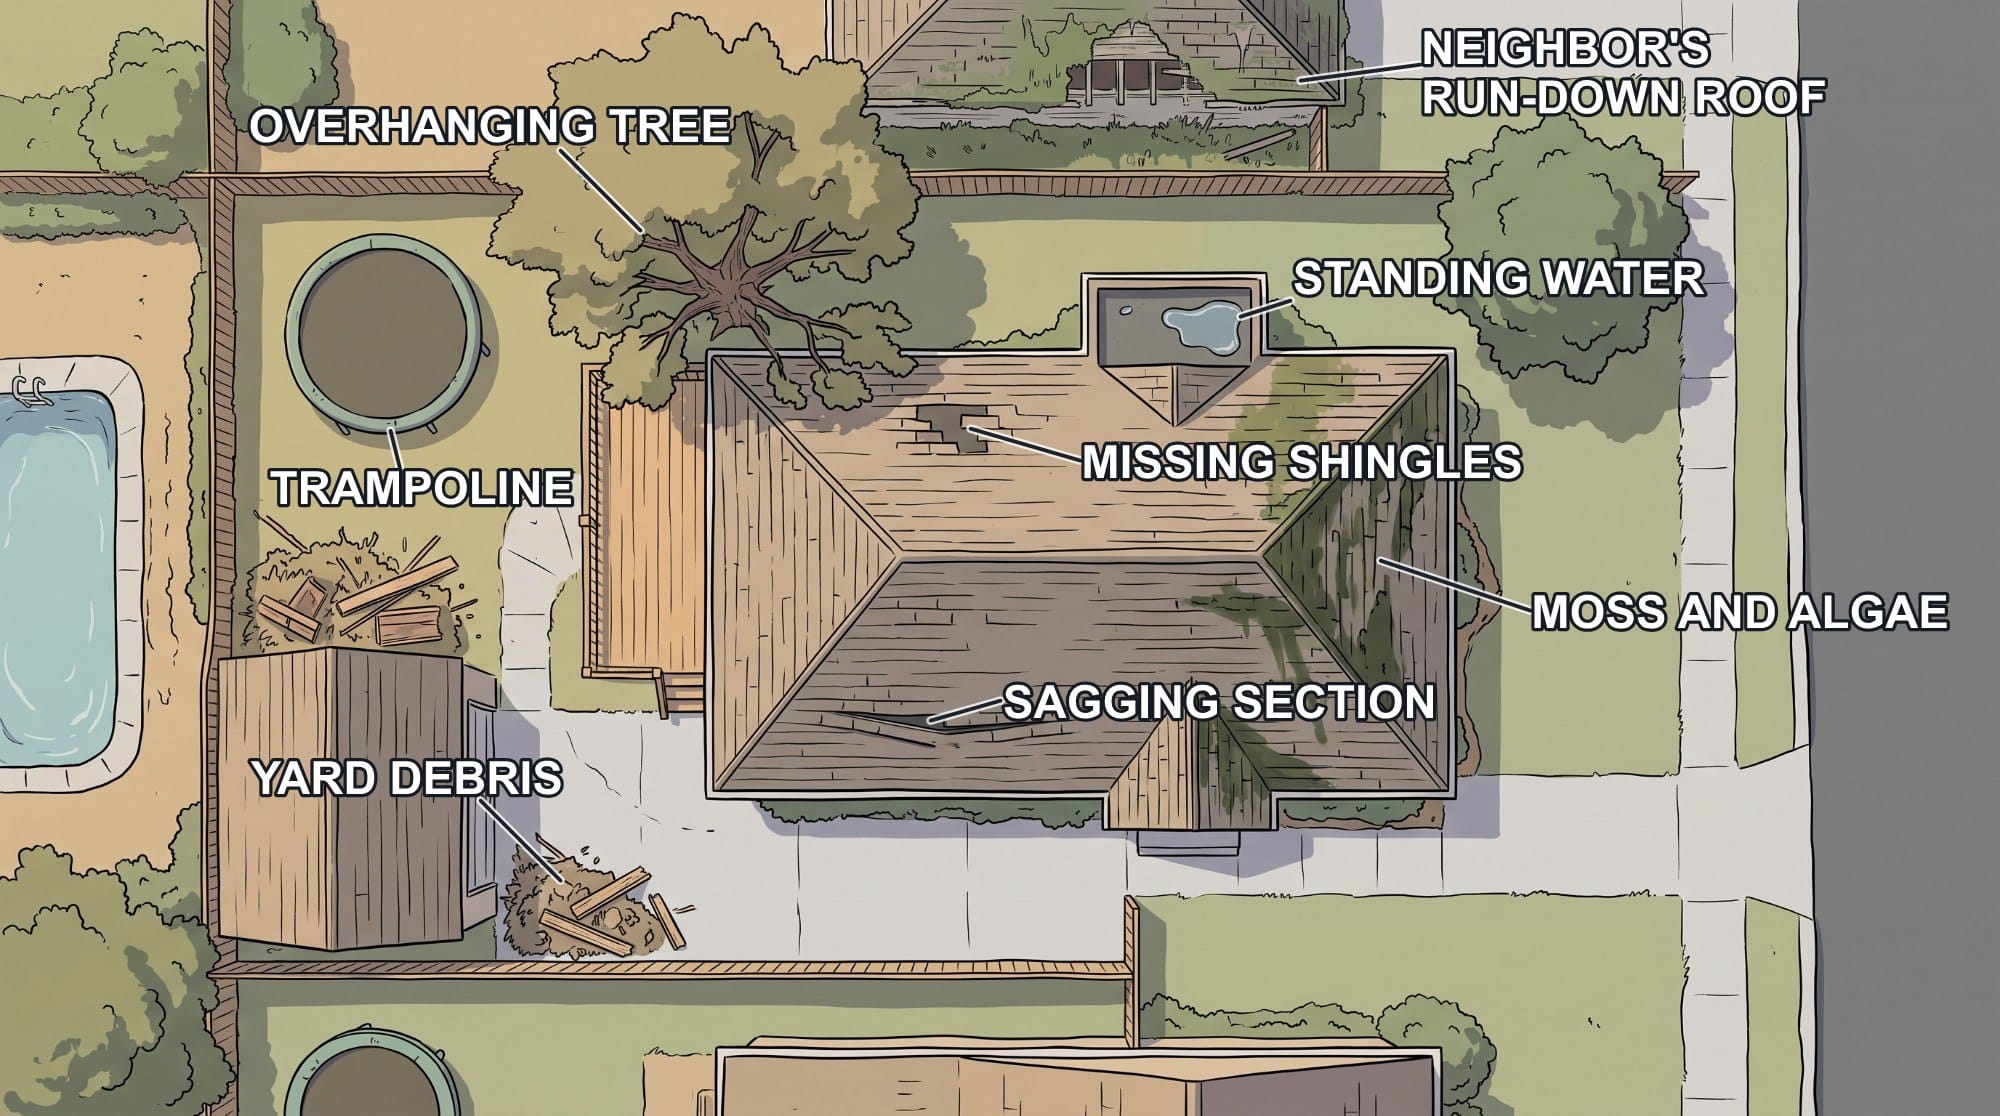
When a satellite or drone captures an image of your home, the AI systems reviewing that image are trained to flag a specific set of risk indicators. Understanding what they look for is the first step toward staying ahead of the process. Roof condition is far and away the biggest factor. Carriers are scanning for missing or damaged shingles, moss or algae growth, sagging sections, ponding water, and visible wear patterns that suggest a roof is nearing the end of its useful life. According to industry data, U.S. roof claims costs reached nearly $31 billion in 2024, roughly a 30% increase since 2022. That kind of loss trend makes carriers very motivated to identify roofs that are likely to generate claims before the next hailstorm or windstorm rolls through. Beyond the roof, satellite and aerial imagery can pick up on tree proximity and overhanging branches, yard debris and clutter, the presence of trampolines, pools, or large decks that increase liability exposure, structural issues visible from above like foundation cracks or leaning walls, and even the condition of neighboring properties that might increase your risk profile. In wildfire-prone regions, carriers are also evaluating defensible space, which refers to how much cleared area surrounds a structure. While this is less of a concern on the North Shore than it is in California or Colorado, the underlying principle applies everywhere: insurers want to see that a homeowner is actively managing risk around the property.
How This Affects Your Renewal
Here is where things get personal. The growing use of satellite data means that your carrier may be evaluating your property condition between renewal cycles without you knowing about it. In most states, including Illinois, insurers can legally use aerial imagery visible from public airspace without providing advance notice to the homeowner. The consequences can be significant. If the imagery flags a concern, you might receive a non-renewal notice 30 to 60 days before your policy expires. You might see a substantial premium increase at renewal. You might receive a letter requesting that you make specific repairs within a set timeframe, or risk cancellation. In some cases, you might simply find that your carrier is no longer willing to quote you at all when you go to shop for a new policy. The frustrating part for many homeowners is that these decisions can be based on outdated or inaccurate imagery. Satellite photos may have been taken months before the review, and a roof you replaced last spring might still show up as damaged in the insurer’s system. Trees you trimmed in the fall might still appear as overhanging hazards. This gap between reality and the data is one of the biggest sources of complaints from homeowners who feel they have been treated unfairly. Since 2023, homeowners in states like Texas have increasingly filed complaints with their state departments of insurance over decisions made on the basis of aerial imagery. Consumer advocates have raised concerns about the loss of human judgment in the process, with some arguing that the technology creates a system where algorithms make coverage decisions about homes that no human has actually visited.
Your Roof Drives the Renewal Decision
If there is one takeaway from the satellite data trend, it is this: your roof matters more to your insurance cost and availability than almost anything else about your home. Industry data shows that the premium gap between newer roofs and aging ones has widened dramatically in recent years. And that gap continues to grow as carriers lean more heavily into property-specific underwriting driven by aerial imagery. Many carriers have also moved away from offering full replacement cost coverage on older roofs, instead shifting to actual cash value schedules that factor in depreciation. The practical effect is that even if your older roof is in good shape, you may be paying more for less coverage than your neighbor with a newer roof. For homeowners approaching a roof that is 15 to 20 years old, the math on a proactive replacement increasingly favors action. Lower premiums, better coverage terms, and a lower chance of non-renewal can make an earlier replacement worth pricing out, on top of fewer leaks and less storm damage.
What Homeowners Can Do Before Renewal
The good news in all of this is that the satellite data trend actually gives homeowners more agency over their insurance outcomes than the old system did. When decisions are made based on visible, physical characteristics of your property, you can take concrete steps to influence those decisions. Here is what homeowners can do.
Keep Your Roof in Top Shape
This is the single most useful thing you can do. Have your roof inspected by a qualified contractor at least once a year, ideally in the spring after winter weather has had its way with things. Address minor issues like missing shingles, flashing problems, or moss growth immediately. Keep a file of dated photos and contractor invoices showing work that has been done. If your roof is approaching the 15-year mark and showing signs of wear, start planning and budgeting for a replacement rather than waiting for a problem.
Manage Your Trees and Landscaping
Overhanging branches are a major red flag in aerial imagery analysis. Carriers see them as a direct threat to your roof and siding, and they are right. Keep branches trimmed back at least six feet from the roof line, and consider removing dead or dying trees entirely. Beyond reducing your insurance risk, this also reduces the chance of actual storm damage, which is a win on both sides of the equation.
Clean Up Your Yard
It might seem trivial, but visible clutter, debris, and deferred maintenance in your yard can and do affect underwriting decisions. Satellite and aerial images capture everything that is visible from above. A clean, well-maintained property signals to the algorithm (and to any human reviewer) that the homeowner is actively caring for the property. Remove old tarps, broken equipment, unused structures, and anything else that suggests neglect.
Document Your Improvements
This is critical and often overlooked. If you have made improvements to your home, particularly a new roof, updated siding, tree removal, or other work that changes the exterior appearance of the property, keep thorough documentation. Save contractor invoices, before-and-after photos with dates, permit records, and any inspection reports. If a carrier flags your property based on outdated imagery, this documentation is your best tool for getting the decision reversed.
Share Your Documentation Proactively
Do not wait for a non-renewal notice to share proof of improvements with your carrier. If you have replaced your roof or made other significant upgrades, let your agent know. A good independent agent can make sure that updated information gets into the underwriting file before the renewal review happens. That is one practical advantage of working through an agent rather than buying direct: we can send your roof invoices and photos to the underwriter before the renewal decision is made.
Review Your Policy Well Before Renewal
At least 60 to 90 days before your policy renewal date, take a hard look at your coverage and start gathering competitive quotes. If your current carrier is planning a non-renewal or a significant rate increase, you want to know about it with enough lead time to find alternatives. The homeowners who get caught off guard are the ones who wait until 30 days out and then scramble.
Consider a Pre-Renewal Inspection
Some homeowners are now hiring independent inspectors to do a roof and property assessment before their renewal date, specifically to identify anything that might show up as a concern in aerial imagery. Think of it like getting a home inspection before selling. You want to know what the buyer (in this case, the insurance company) is going to see, and you want to fix anything fixable before they see it.
Invest in Impact-Resistant Materials
When you do replace a roof or make other exterior upgrades, choose materials that carry impact resistance ratings. Many carriers offer discounts for Class 4 impact-resistant shingles, and some will not even write a policy on a home without them in hail-prone areas. On the North Shore, where severe convective storms are an increasing concern, this is an investment that pays dividends on both the insurance side and the damage prevention side.
Work with an Independent Agent
When an algorithm is reading photos of your roof, it helps to have someone who knows how different carriers use aerial imagery and which ones are more flexible on older roofs. An agent can move the policy to a carrier that fits the house, or answer a flagged image with evidence before the renewal decision.
The Regulatory Picture
State regulators are paying attention to this trend, though the regulatory response has been uneven. Some states have begun introducing legislation that would require carriers to notify homeowners before taking aerial images of their property or to disclose when automated imaging data is used in underwriting decisions. California introduced a bill in 2025 that would require 30 days advance notice before aerial imaging of a property. In Illinois, the regulatory framework is still evolving. The Illinois Department of Insurance has the authority to investigate complaints related to unfair underwriting practices, and homeowners who believe they have been treated unfairly based on inaccurate aerial imagery should absolutely file a complaint. The more complaints regulators receive, the more attention the issue gets, and the more likely we are to see meaningful consumer protections put in place.
Looking Ahead
The use of satellite and aerial data in home insurance is not going away. If anything, it is accelerating. The satellite constellation orbiting Earth is expected to grow from roughly 10,000 satellites to as many as 70,000 in the coming years, and the cost of satellite manufacturing and launch has dropped to roughly one-third of what it was in the 1990s. That means more frequent imagery, higher resolution, and even more data feeding into carrier underwriting models. For homeowners, the practical implication is clear: the physical condition and appearance of your property is now continuously visible to your insurance carrier in a way it never was before. That can feel intrusive, and the privacy concerns are legitimate. But it also means that the homeowners who take the best care of their properties are increasingly being rewarded with better rates, better coverage terms, and better access to the most competitive carriers. The old model of insurance underwriting relied heavily on broad averages and zip-code-level risk assessments. The new model is far more granular and property-specific. If your home is well maintained and your roof is in good shape, that specificity works in your favor. If it is not, the gap between what you are paying and what your well-maintained neighbor is paying is only going to get wider.
Maintain the Roof and Keep the Paperwork
Satellite data and aerial imagery have fundamentally changed the home insurance renewal and underwriting process. Carriers can now evaluate your property remotely, in detail, and at any time. The decisions that come out of that process affect your premiums, your coverage availability, and your options. The homeowners who come out ahead in this new environment are the ones who treat property maintenance as an ongoing insurance strategy, not just a home improvement project. Keep your roof in excellent condition. Manage your trees. Clean up your yard. Document everything. And work with an independent agent who understands how the system works and can make sure your property is presented accurately to the carriers who are looking at it from above. If a renewal notice cites aerial imagery, or you have received a non-renewal, send it to us with your roof invoices and dated photos. Longmeadow Insurance is an independent agency in Wilmette that works with multiple carriers across the North Shore; we can compare the imagery with your records and tell you which carriers may view the house differently.
Related Insurance Guides
Coverage We Write
- Home insurance on the North Shore
- Flood and water backup coverage
- Umbrella insurance
- Personal insurance overview
Call 847.242.1040 or request a quote online.