
Your Insurance Changes the Moment Construction Starts
Older homes in Wilmette, Winnetka, and the rest of the North Shore get renovated all the time. The day contractors start work, your insurance exposure changes, whether or not your policy does.
Notify Your Insurance Agent Before Work Begins
This is the most important step. Your agent needs to know about significant renovations because:
- The value of your home is changing, which affects your dwelling coverage
- Construction activity increases the risk of fire, water damage, and theft
- Workers on your property create liability exposure
- Some renovations can take the home outside what a homeowners policy covers and call for a builder’s risk policy instead
Verify Your Contractor’s Insurance
Before any contractor starts work on your property, require proof of:
- General liability: minimum $1 million per occurrence
- Workers compensation: required in Illinois for most employers
- Commercial auto: if they’re driving to your property
Request a Certificate of Insurance (COI), and ask the contractor to add you as an additional insured by endorsement. The certificate only shows that the policy exists; the endorsement is what extends their liability coverage to you if their work leads to a claim.
If a contractor doesn’t carry insurance (or can’t prove it), don’t hire them. An uninsured worker who falls off your roof becomes your liability claim.
When You Need a Builder’s Risk Policy
For major renovations, gut rehabs, additions, or projects where the home is temporarily unoccupied, you may need a builder’s risk policy. This covers the structure and materials during construction against fire, wind, theft, and vandalism.
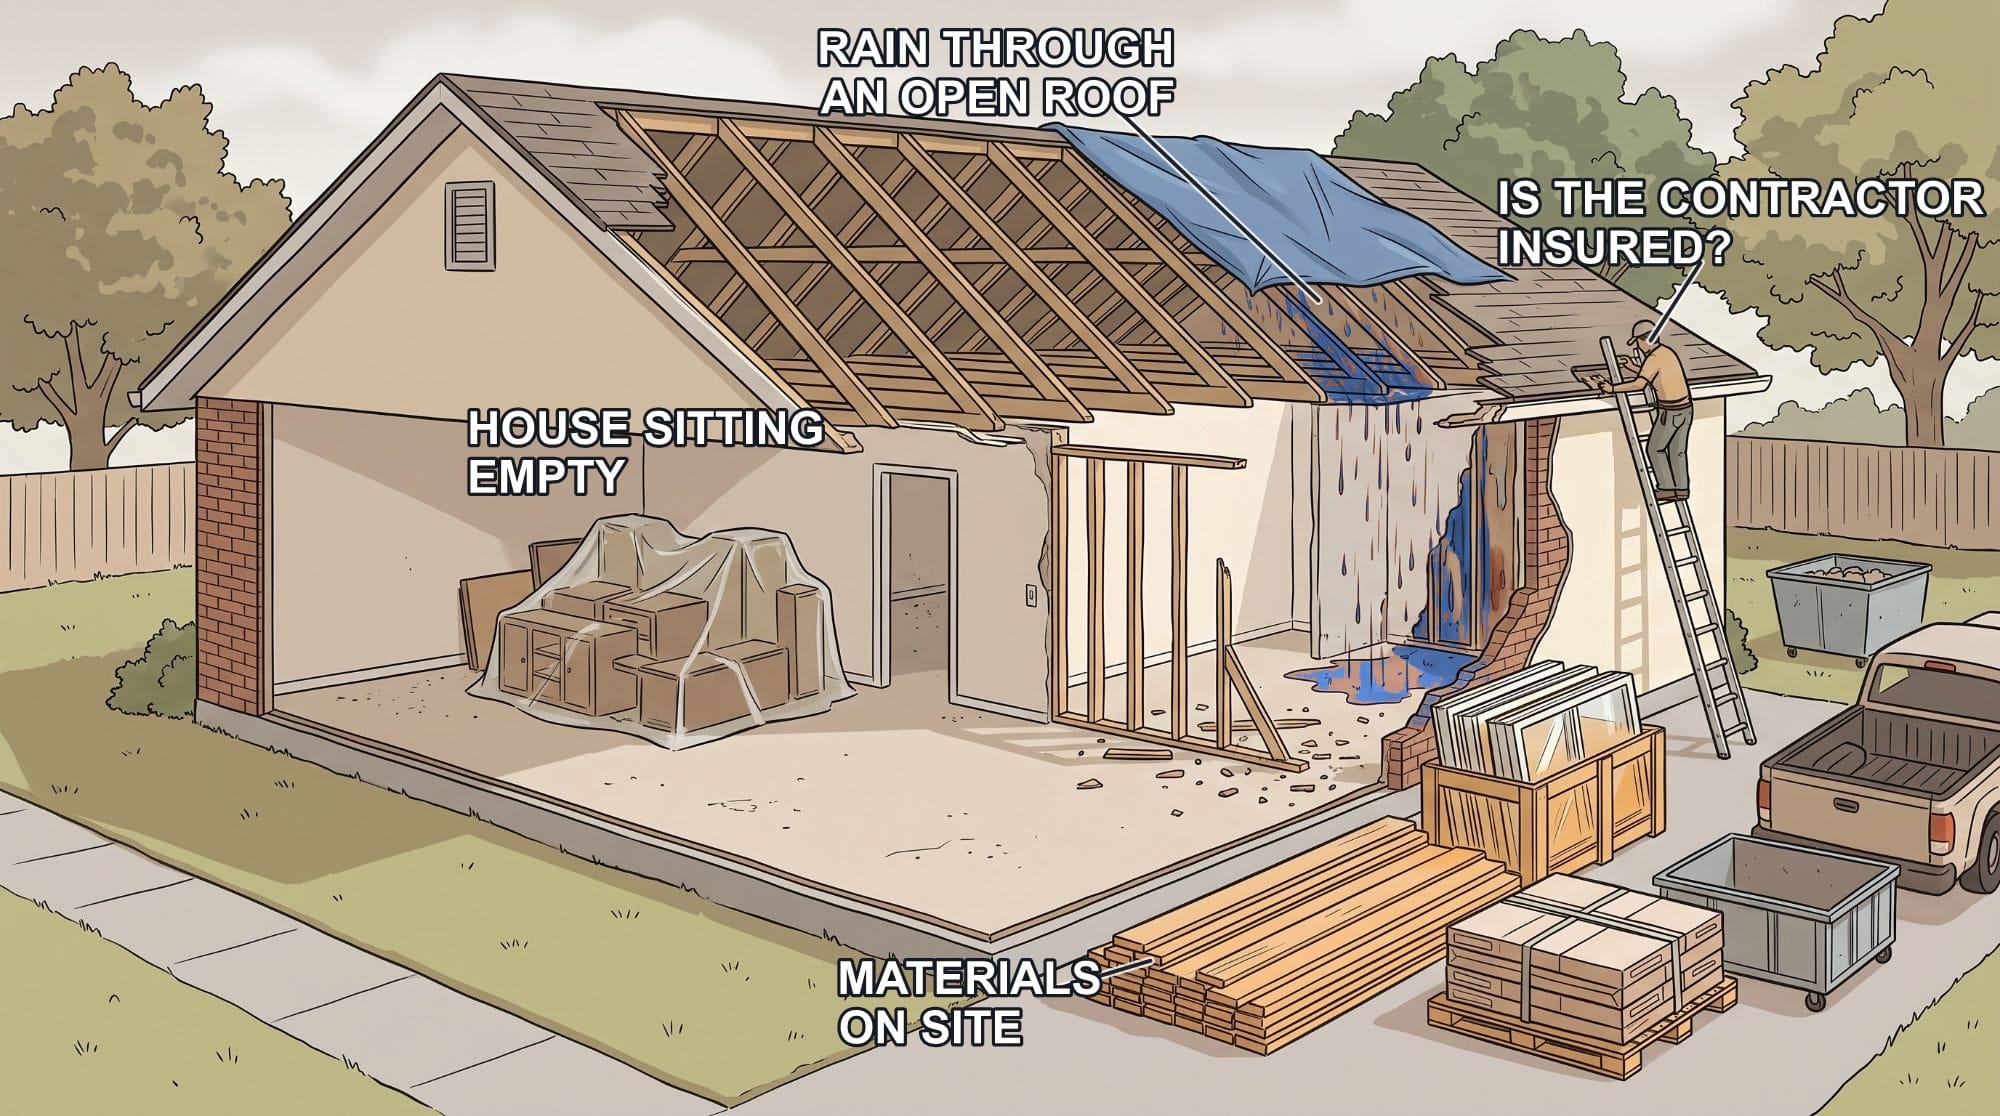
Your standard homeowners policy may have exclusions for homes under major construction. A builder’s risk policy fills that gap.
The Permit Question
If your renovation requires a building permit (and in most North Shore communities, anything beyond cosmetic changes does), make sure it’s pulled before work begins. Insurance claims can be denied if the damage is related to unpermitted work.
Also ask about ordinance or law coverage, sometimes called code upgrade coverage. After a covered loss, it helps pay the extra cost of rebuilding to current building codes. It does not pay for code work that your renovation itself requires.
Update Your Coverage During and After Renovation
During Construction
- Increase your dwelling coverage to reflect the mid-construction value plus materials on site
- Consider additional theft coverage for materials and fixtures stored at the property
- Review your liability limits: more people on your property means more risk
After Completion
- Update your dwelling coverage to reflect the new, improved value of the home
- Update your personal property coverage for new furniture and electronics; built-in fixtures and systems count toward the dwelling limit
- Document the renovation with photos for your home inventory
A $100,000 kitchen renovation that isn’t reflected in your dwelling limit can leave you up to $100,000 underinsured.
Common Renovation Insurance Mistakes
- Not telling your agent about the project: You can end up underinsured, or in a dispute over any claim tied to the work
- Not verifying contractor insurance: One injury can become your claim
- Not updating coverage after completion: You’re underinsured on day one
- Assuming your contractor’s policy covers everything: It responds when the contractor is legally responsible for damage, and it won’t pay to redo their own faulty work
Get Your Renovation Coverage Reviewed
Before work starts, send us your declarations page and a short description of the project. We will tell you what your policy covers during construction and what should change when the work is done. Request a review or call 847.242.1040.
Related Articles
- What Homeowners Need to Know About Insurance and Renovations
- How Subcontractors Affect Your Insurance
- Roof Coverage Insurance in Chicago
Coverage We Write
Longmeadow Insurance is an independent agency in Wilmette with offices across Chicago and the suburbs. If any of this applies to your situation, we can review your current policy and tell you what it actually covers.
- Home insurance on the North Shore
- Flood and water backup coverage
- Umbrella insurance
- Personal insurance overview
Call 847.242.1040 or request a quote online.