
Lessor’s Risk Insurance for Commercial Landlords
Coverage at a Glance
Select a numbered marker on the illustration, or a coverage name below it, to see where each coverage applies. Dashed markers are coverage-planning topics rather than individual policies.
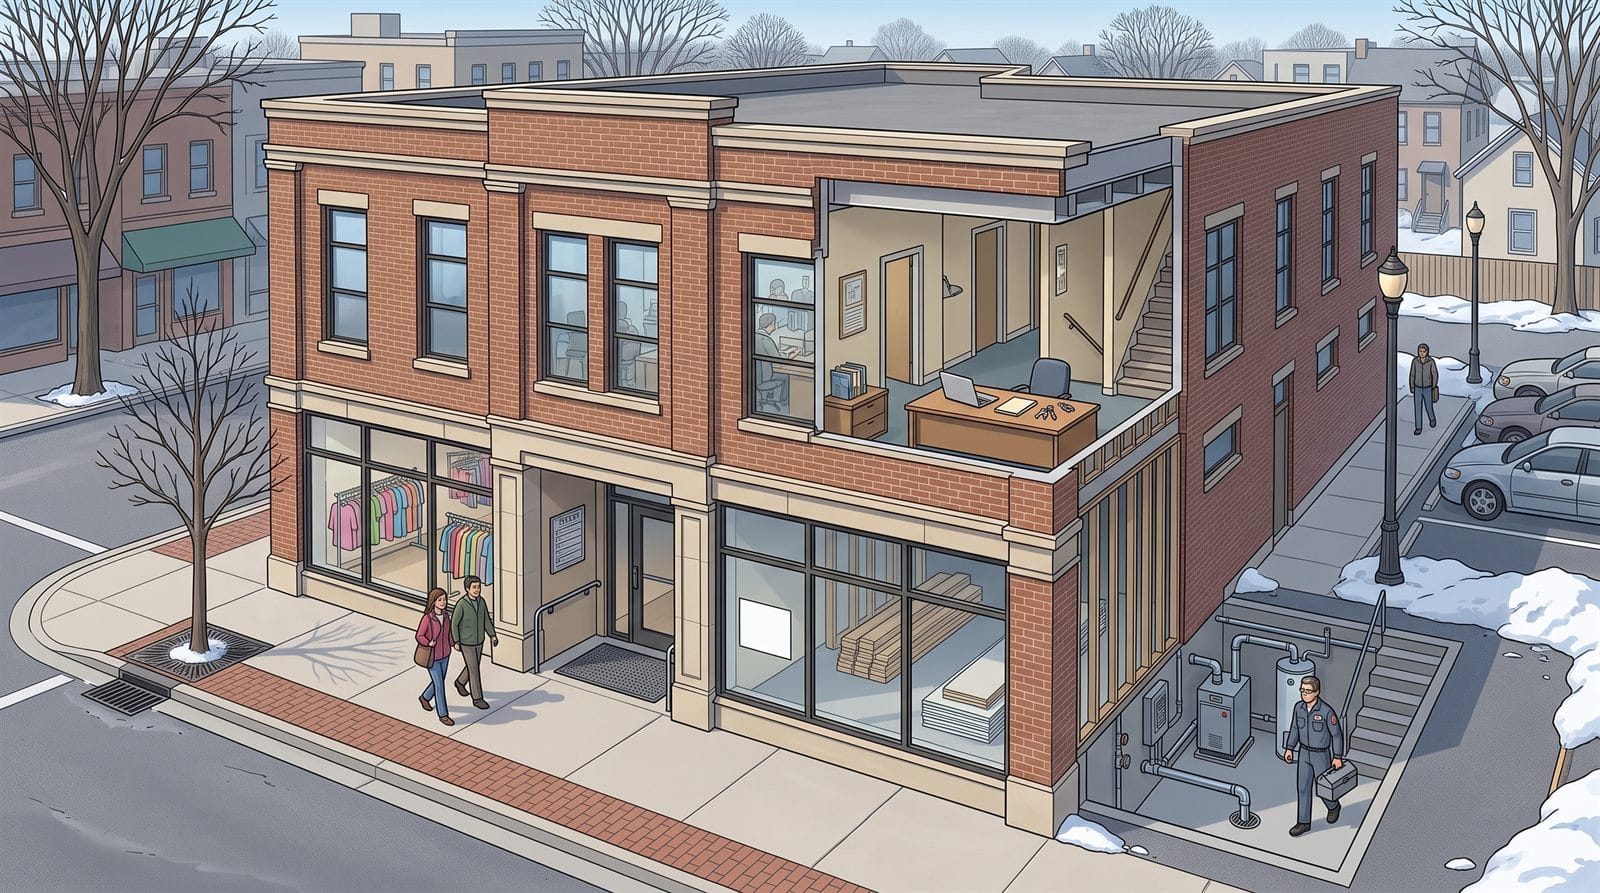
Building coverage
Your building is the core of your investment. Commercial property insurance can help repair covered damage to the structure and insured building systems after events such as fire or wind. Review replacement costs, deductibles, and responsibility for tenant improvements when setting coverage.
Lessor’s liability
A visitor trips at the entrance and claims you failed to maintain the property. Landlord liability coverage can help with legal defense and covered damages when you’re held responsible for bodily injury or damage to someone else’s property.
Loss of rental income
A covered fire makes leased space unusable and interrupts rent payments. Rental-value coverage can help replace covered lost rental income and pay eligible continuing expenses during restoration. Select limits and a restoration period that reflect how long your building could take to reopen.
Equipment breakdown
A sudden mechanical or electrical breakdown can leave tenants without heat or essential building services. Equipment breakdown coverage can help repair or replace covered equipment. Ordinary wear, aging, and routine maintenance are not covered breakdowns.
Water damage review
A burst pipe can damage several tenant spaces before anyone discovers it. Review how your building policy handles sudden water damage, leak-related exclusions, and damage to owner-installed finishes. Tenant belongings and business losses need their own coverage review.
Sewer and drain backup
Water backing up through a drain can damage basement systems and finished space. Ask whether sewer and drain backup coverage is included or needs to be added, and check its limit and deductible. Review sump overflow separately where applicable.
Flood insurance
Heavy rain can send surface water into lower-level spaces. Standard commercial property insurance generally excludes flood. Separate commercial flood coverage can help protect insured building property against qualifying flooding; review basement restrictions and available limits.
Ordinance or law
Repairing an older building after covered damage may trigger current building-code requirements. Ordinance or law coverage can help with specified demolition costs, loss to undamaged portions, and increased rebuilding costs. Review which components and limits your policy includes.
Vacancy and renovations
An empty suite or renovation changes the questions your insurance needs to answer. Tell your agent about occupancy changes and planned work. Review vacancy provisions and whether builders risk or renovation coverage is appropriate before construction begins.
- Coverage-planning topic
Tenant insurance requirements
A tenant’s activities can create claims involving the building owner. Review lease insurance requirements, tenant certificates, and any required additional-insured endorsements. A certificate documents insurance information; it does not itself add coverage or make you an additional insured.
- Coverage-planning topic
Tenant property and improvements
Who insures the merchandise, counters, and improvements inside a rented suite? Your building policy does not automatically insure everything your tenants own. Coordinate the lease and both parties’ policies so responsibility for inventory, fixtures, and buildouts is clear.
Commercial umbrella
A serious injury claim on the property can exceed your primary liability limits. A commercial umbrella can provide additional limits above specified underlying policies for covered claims. Review the insured ownership entities, properties, and underlying coverage requirements.
Cyber coverage
Managing leases and rent payments means handling sensitive information. Cyber insurance can help address covered data breaches and related response costs. Review your exposure to compromised tenant information, ransomware, and payment fraud, including which protections require separate coverage.
Send us your current policy and a recent lease, and we will check both against the coverages above.
Lessor’s Risk Insurance for Commercial Landlords in Illinois
Owning a commercial building is not the same as operating the business inside it. A retail tenant, restaurant, contractor, medical office, warehouse user, or professional firm may create daily liability exposure, but the building owner still has a separate risk: the property itself, the lease obligations, premises liability, loss of rental income, and the chance that a tenant’s operations cause damage to the building.
Lessor’s risk insurance, also written lessors risk and often called lessor’s risk only or LRO insurance, is built for commercial landlords who lease non-habitational space to business tenants. Longmeadow Insurance helps building owners in Wilmette, Chicago, the North Shore, and throughout Illinois structure coverage around the actual property, the tenant mix, the lease language, and the owner’s financial exposure.
What Is Lessor’s Risk Insurance?
Lessor’s risk is the insurance term for what a building owner still carries after leasing the space to someone else: the building itself, and liability for the parts of the property the owner controls. Lessor’s risk insurance is the commercial policy written for that owner. It typically combines commercial property coverage for the building with general liability coverage for the landlord’s premises exposure. The goal is to protect the owner from covered damage to the building and liability claims tied to ownership, maintenance, or common areas.
This page focuses on non-habitational landlords: owners of commercial buildings, retail centers, office buildings, warehouses, mixed-use commercial spaces without residential rental exposure, and similar properties. Apartment buildings, two-flats, three-flats, and residential rental properties need a different insurance review.
Who Needs Lessor’s Risk Coverage?
- Owners of retail strip centers and storefront buildings
- Office building owners leasing to professional tenants
- Warehouse and light industrial landlords
- Medical, dental, and professional office building owners
- Commercial condo unit owners who lease space to a tenant
- Owners of single-tenant commercial buildings
- Mixed-use building owners with commercial tenant exposure that needs a separate review
- Real estate investors with multiple commercial properties
Key Coverages for Commercial Building Owners
- Commercial Property Coverage: Covers the building against covered losses such as fire, wind, hail, vandalism, and certain water losses. The limit should be based on replacement cost, not the market value of the building or the loan balance.
- General Liability: Protects the landlord against bodily injury and property damage claims tied to ownership or maintenance of the premises, including common-area slip-and-fall claims, sidewalk issues, parking lot hazards, and allegations of negligent maintenance.
- Loss of Rents and Business Income: Replaces rental income when a covered loss makes the building or leased space unusable. Without it, the mortgage, taxes, and insurance on the building still come due after the rent stops.
- Ordinance or Law Coverage: Helps pay for the increased cost of rebuilding to current code after a covered loss. This matters for older commercial buildings, where code upgrades can be expensive.
- Equipment Breakdown: Covers mechanical or electrical breakdown of building systems such as HVAC, boilers, electrical panels, elevator equipment, and other systems the landlord is responsible for maintaining.
- Water Backup and Utility Service Interruption: Helps address losses that standard property language may limit or exclude. These coverages should be reviewed carefully for buildings with basements, lower-level tenants, or utility-dependent operations.
- Tenant Improvements and Betterments: Clarifies which improvements belong to the landlord, which belong to the tenant, and how they should be insured after a covered loss.
- Umbrella or Excess Liability: Provides additional liability limits above the underlying general liability policy. This is often appropriate for property owners with meaningful assets, multiple buildings, public foot traffic, or higher-risk tenants.
Lease Requirements Matter
The lease is one of the most important insurance documents a commercial landlord has. It should clearly address tenant insurance requirements, additional insured status, waivers of subrogation, maintenance responsibilities, indemnification, and who insures improvements, signs, glass, HVAC units, and other property connected to the building.
We review the insurance side of the lease structure so the landlord’s policy and the tenant’s policy work together instead of leaving gaps. A tenant certificate alone is not enough if the certificate does not match the lease or if the lease pushes exposure back onto the owner.
Tenant Mix Changes the Risk
A building leased to a quiet accounting office is not the same risk as a building leased to a restaurant, auto repair shop, contractor, fitness studio, medical practice, or manufacturer. The tenant’s operations affect fire exposure, liability frequency, utility dependence, maintenance demands, and the likelihood of property damage.
That is why we do not treat lessor’s risk insurance as a generic property policy. We look at tenant operations, building age, roof condition, plumbing and electrical systems, common areas, parking lots, life safety systems, lease terms, replacement cost, and the owner’s income dependency before recommending coverage.
Common Coverage Gaps for Commercial Landlords
- Building limits based on purchase price instead of replacement cost
- No loss of rents coverage or a rental income limit that is too low
- Weak ordinance or law coverage on older buildings
- Unclear responsibility for tenant improvements, HVAC units, glass, signs, and exterior property
- Certificates collected from tenants but never reviewed against lease requirements
- Tenant operations that changed over time without an insurance review
- Vacant or partially vacant space that changes underwriting eligibility
- Low liability limits relative to the owner’s assets and public foot traffic
Commercial Landlord Insurance on the North Shore and in Chicago
Commercial landlords in Chicago and the North Shore often own older buildings with expensive replacement cost, high property taxes, public sidewalks, shared parking, roof and water exposure, and tenants whose operations can change quickly.
Longmeadow Insurance is an independent agency based in Wilmette, Illinois. We read the leases and tenant certificates along with the policy, because that is where most landlord gaps turn up.
To request a commercial landlord insurance review, send us the current policy, your tenant list, and the leases, or call 847.242.1040.
Serving commercial landlords and building owners in Wilmette, Northfield, Winnetka, Glencoe, Kenilworth, Evanston, Northbrook, Highland Park, Glenview, Skokie, Chicago, and throughout Illinois.
Common Questions
What does lessor’s risk insurance cover?
Lessor’s risk insurance usually combines commercial property coverage for the building with general liability coverage for the landlord’s premises exposure. It can also include loss of rents, ordinance or law coverage, equipment breakdown, water backup, and umbrella liability depending on the building and policy structure.
Is lessor’s risk insurance the same as landlord insurance?
It is a type of landlord insurance, but the phrase lessor’s risk is usually used for commercial landlords who lease non-habitational space to business tenants. Residential rental properties, apartment buildings, and short-term rentals require a different coverage review.
Do my tenants need their own insurance?
Yes. Commercial tenants should carry their own general liability, business personal property, workers compensation when applicable, and any coverage required by the lease. The landlord should be named as an additional insured where appropriate, and certificates should be reviewed against the lease requirements.
Does lessor’s risk insurance cover lost rent?
It can, but only if loss of rents or business income coverage is included and the loss is caused by a covered event. The limit should be reviewed against rental income, lease terms, debt service, taxes, insurance, and the likely time needed to repair or rebuild the property.
Can Longmeadow review my commercial landlord policy and lease requirements?
Yes. Longmeadow Insurance can review your current lessor’s risk policy, tenant certificates, and insurance requirements in the lease so you can see where the coverage is strong and where gaps may exist.
Business Insurance Resources
- Business Insurance for Chicago and the North Shore
- Insurance Requirements for Illinois Small Businesses
- Professional Office Insurance
- Retail Store Insurance
Office Buildings and Multi-Tenant Properties
An office building is underwritten differently from a retail strip or a single-tenant industrial box, and the differences show up in places owners rarely check until a claim.
- Common area liability. Lobbies, elevators, stairwells, parking, and walkways stay your responsibility no matter how the suites are leased. Slip and fall in a shared corridor is the most frequent liability claim on these properties.
- Elevator and equipment breakdown. Standard commercial property forms exclude mechanical and electrical breakdown. For a building with elevators, boilers, chillers, or rooftop HVAC, an equipment breakdown endorsement is the difference between a covered loss and a capital expense.
- Tenant improvements and betterments. Build-out paid for by the tenant is generally theirs to insure, but build-out you funded as a leasing concession is yours. Leases are frequently silent or contradictory on this, and the policy needs to match whatever the lease actually says.
- Ordinance or law coverage. Older office and mixed-use buildings rarely meet current code. After a significant loss, the rebuild has to, and the added cost is only covered if this endorsement is present at an adequate limit.
- Vacancy provisions. Most commercial property forms cut coverage sharply once a building passes a vacancy threshold, commonly sixty days. A partially leased building working through turnover can drift into that condition without the owner realizing it.
Certificate Tracking Is the Practical Job
Your lease almost certainly requires each tenant to carry general liability, name you as an additional insured, and provide a certificate. The weak point is usually the follow-through.
Track tenant renewals and the endorsements required by the lease. A lapse leaves required protection missing; it does not automatically transfer the tenant’s liability to the landlord’s policy. We compare the lease requirements with the documents on file and identify what needs updating.
Residential Rental Property
Lessor’s risk is built for leasing space to business tenants. If your rental property is residential, generally up to four units, the right form is a landlord policy instead. Owners holding both a commercial building and residential rentals need each on the appropriate form, and we structure them together so the liability limits and umbrella coordinate rather than leaving a gap between them.
Erie and Other Lessor’s Risk Markets
Commercial property owned for lease is a class Erie Insurance writes, and we quote it as an appointed Erie agent for building owners across Chicago and the suburbs.
Tenant mix is what decides the market here. A building leased to professional offices is underwritten very differently from one with a restaurant, an auto shop, or light industrial tenants, and appetite tightens quickly as the tenant risk rises. We place lessor’s risk across several carriers and compare Erie against them on the specific tenant roster.