Condo Association and HOA Insurance in Illinois
Coverage at a Glance
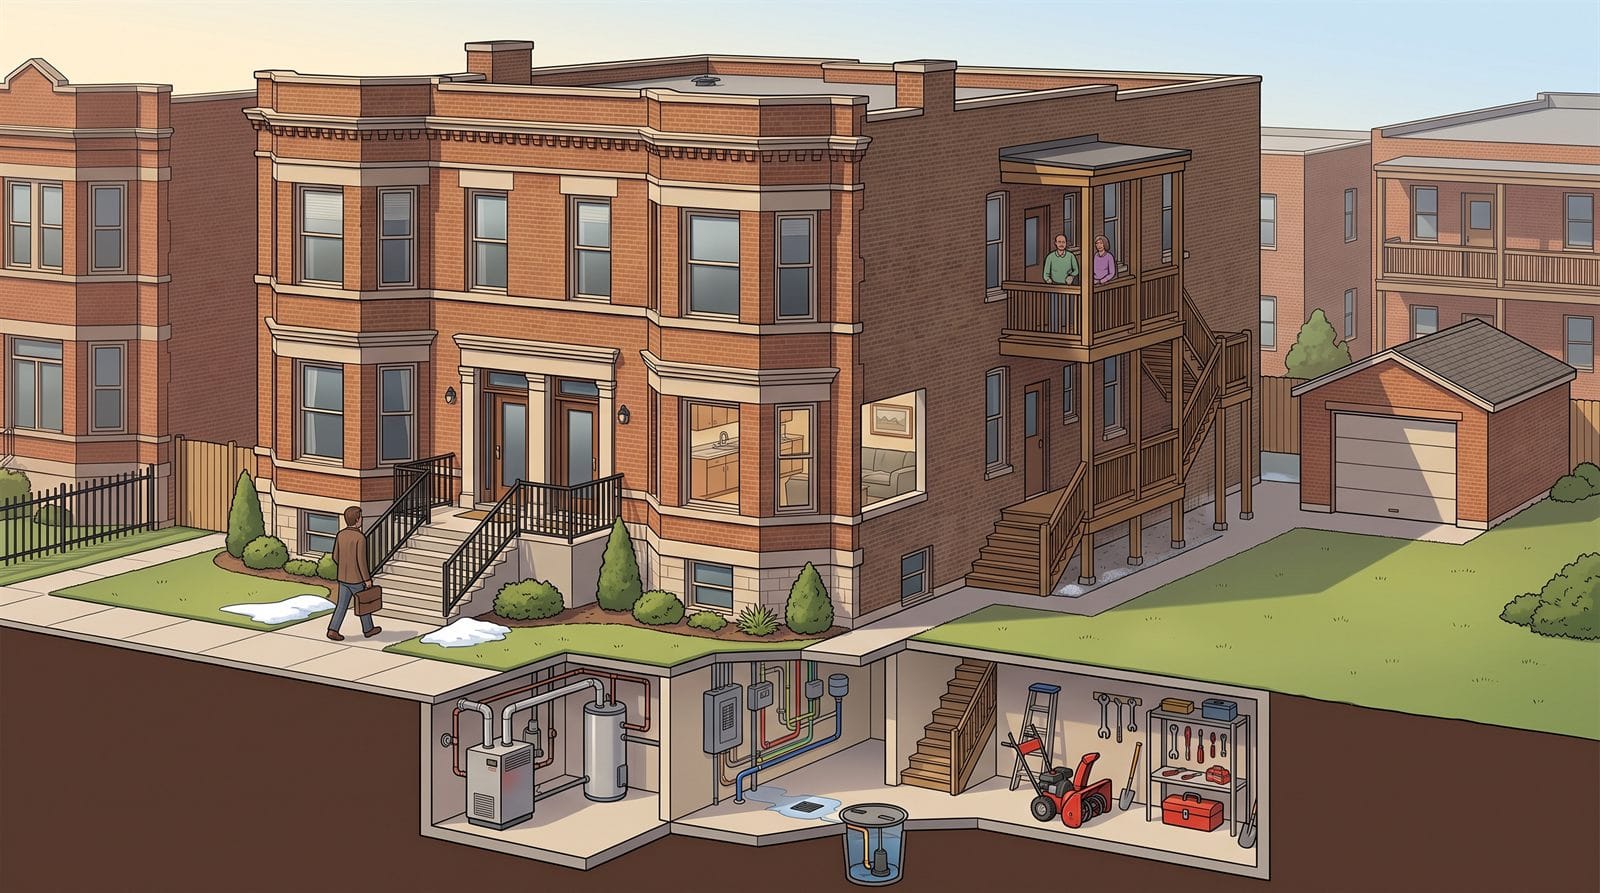
Select a part of the building, a numbered marker, or a coverage name below the picture to see where each coverage applies.
- Building property coverage
Could your association afford to rebuild?
Building property coverage helps repair or replace insured property after a covered loss, such as fire. The insurance amount should reflect reconstruction costs, not the building’s sale price or owners’ combined equity. Ask how your policy handles replacement cost, coverage limits, and underinsurance.
- Roof coverage and deductibles
A roof claim can come with a large deductible.
Wind or hail damage may be covered, but roof coverage can have separate deductibles, payment limitations, or exclusions. Aging roofing and routine maintenance generally aren’t insured losses. We’ll check the roof settlement terms before a storm reveals an expensive gap.
- Ordinance or law coverage
Repairs may have to meet today’s building codes.
After a covered loss, required code upgrades can increase rebuilding costs. Ordinance or law coverage can help with qualifying upgrades, demolition, and loss to undamaged portions of the building. It isn’t a fund for correcting existing code violations or routine modernization.
- Equipment breakdown
What happens when the building’s heat fails?
Equipment breakdown coverage can help with covered sudden mechanical or electrical breakdowns of insured building equipment. Ask about repair costs and related extra expenses. Ordinary wear, corrosion, and routine maintenance are generally excluded; an old boiler needing replacement isn’t automatically a covered claim.
- Water damage from building plumbing
One broken pipe can affect several units.
Sudden, accidental water damage from building plumbing may be covered. The damaged property, cause of loss, and association responsibilities determine how the master policy and unit-owner policies respond. Ask about water-damage deductibles and restrictions on repeated leakage or seepage.
- Sewer backup and sump overflow
Water coming up is a different coverage question.
Sewer backup and sump overflow can damage shared equipment and building interiors. Don’t assume they’re included in ordinary water-damage coverage. Ask for specific protection and adequate limits. Also review flood coverage separately. Surface flooding and drain backup can trigger different policy terms.
- General liability
A visitor slips on the shared entrance.
General liability coverage can help defend the association and pay covered damages when it is legally responsible for someone’s injury or property damage. Shared stairs, walkways, and entrances deserve particular attention. Insurance works alongside regular inspections, repairs, and snow removal.
- Commercial umbrella
Could a serious injury exceed your liability limit?
A major accident involving shared stairs or a porch could produce a substantial liability claim. Commercial umbrella or excess liability coverage can add protection above specified underlying policies. Check which policies it follows; coverage for board-related claims isn’t automatically included.
- Directors & officers, crime, and social engineering
The board’s decisions and the association’s money
Volunteer board members can still be sued. Disputes over assessments, rule enforcement, or board decisions can lead to claims against the association and its directors. Directors and officers liability insurance can help with covered allegations of wrongful acts. Ask about defense costs, nonmonetary claims, and coverage for the property manager.
Protect the association’s operating and reserve funds. Crime or fidelity coverage can help protect association funds against covered theft or dishonesty. Make sure the policy addresses the people who handle your money, including board members and any management company. Review the limit against the funds the association holds.
What if a contractor’s payment instructions are fake? A convincing email can trick a board member into transferring association funds to a criminal. Ask specifically about social engineering and fraudulent payment coverage; ordinary crime or cyber insurance may leave gaps. Independently verify changes to payment instructions before sending money.
- Business personal property
The association owns more than the building.
Shared maintenance equipment, tools, and other association-owned belongings also need protection. Business personal property coverage can help after a covered loss. Include their replacement value when reviewing insurance, and distinguish association property from residents’ belongings kept in the basement.
- Other structures
Are all association structures included?
A detached garage or other shared structure can be overlooked when coverage is arranged. Confirm that the policy includes every structure the association is responsible for, with appropriate values. Building coverage does not automatically insure residents’ cars or everything they store inside.
- Master policy versus unit-owner policies
Where does the association’s coverage end?
The master policy and each owner’s condo policy should work together. Interior building components, owner improvements, personal belongings, and liability can fall under different coverages. We’ll review the governing documents and insurance terms to help clarify responsibilities and identify gaps.
Send Longmeadow your master policy and condo declaration for an association coverage review.
Illustrative coverage examples. Coverage depends on policy terms, endorsements, deductibles, exclusions, and applicable association responsibilities.
An association buys a different product than its unit owners do. The board is insuring a building, a set of common elements, and its own decisions. A unit owner is insuring what sits inside their walls. Confusing the two is how associations end up underinsured and how owners end up with assessments they did not expect.
We work with self-managed boards and professionally managed associations across Chicago and the North Shore, from six-unit vintage conversions to larger developments with amenities and staff.
The Master Policy and What It Covers
The master policy covers the building and common elements. How far into the individual unit it reaches is set by the declaration, and it is the single most important thing a board should be able to answer about its own coverage. There are three common structures.
| Structure | Where the master policy stops | What the owner insures |
|---|---|---|
| Bare walls | At the unfinished studs, subfloor, and ceiling | Drywall, flooring, cabinets, fixtures, appliances, and all finishes |
| Single entity | Includes original fixtures and finishes as built | Upgrades and improvements made after construction, plus personal property |
| All-in | Includes fixtures, finishes, and improvements | Personal property, liability, and loss assessment |
Most Illinois associations we review are single entity or bare walls, and most owners in those buildings assume they are all-in. That gap surfaces after a pipe break, when the association’s adjuster stops at the studs and the owner’s HO-6 turns out to carry a token building property limit. Our guide to condo insurance for unit owners covers the other side of that line.
Boards can help here at almost no cost. Sending owners a short annual notice stating which structure the declaration uses, and what that means they need to insure, prevents most of these disputes and is worth more than any coverage change.
What Illinois Requires of Associations
The Illinois Condominium Property Act sets baseline insurance obligations for condominium associations, including property coverage on the common elements at replacement cost and liability coverage for the association. Your declaration and bylaws frequently require more than the statute does, and lenders add their own requirements on top.
In practice, three documents govern what the association has to buy: the statute, the declaration, and whatever Fannie Mae or a unit owner’s lender demands before financing a sale in the building. When a board discovers a coverage shortfall, it is usually because a buyer’s lender flagged it, not because anyone reviewed the policy.
Boards should also read the declaration on deductible responsibility. Many Illinois declarations allow the association to assess a unit owner for the master policy deductible when a loss originates in that unit, and owners are rarely told this until it happens.
Directors and Officers Liability
Board members are volunteers making decisions about other people’s money and property, and they get sued for it. Denied architectural requests, selective rule enforcement, special assessments, election disputes, and discrimination claims are the recurring categories.
Two things separate a usable D and O policy from a nominal one. The first is whether defense costs sit inside the limit or outside it, because association D and O claims are defense-heavy and a limit that erodes with legal fees runs out fast. The second is whether the policy covers non-monetary claims, since a large share of association suits ask a court to order the board to do something rather than to pay damages.
Coverage for the property manager, for prior board members, and for volunteers working on committees is also worth confirming rather than assuming.
Fidelity and Crime Coverage
Associations hold reserve funds and hand day-to-day control of them to a treasurer or a management company. Fidelity coverage, sometimes written as a crime policy, responds to theft of association funds by board members, employees, or the manager.
Two details matter. Limits should be set against the reserve balance plus a few months of assessments rather than a round number chosen years ago, and the policy should be endorsed to cover the management company’s employees, which is not automatic. Fannie Mae has its own fidelity requirements for buildings above a certain unit count, and falling short can complicate sales in the building.
The Rest of the Program
- General liability. Injuries in common areas, on walkways, and at amenities. See general liability insurance.
- Umbrella. Excess limits above the liability and any auto exposure. Lenders often require a specific amount for larger buildings.
- Workers compensation. Required once the association has employees, and worth reviewing even where it does not, since uninsured contractors can be treated as employees at audit. See workers compensation in Illinois.
- Equipment breakdown. Boilers, elevators, chillers, and building systems. Frequently the difference between a covered loss and an assessment.
- Water and sewer backup. Standard property forms handle this narrowly, and Chicago-area buildings need it addressed directly. See sewer backup coverage in Illinois.
- Ordinance or law. Vintage buildings rebuilt after a loss must meet current code, and this coverage pays the difference. Under-bought almost everywhere.
- Cyber. Associations hold owner banking details and get targeted for wire fraud on assessments and reserve transfers. See cyber liability insurance.
Insuring the Building for the Right Number
Association property limits drift out of date faster than any other line we see. Construction costs moved sharply over the last several years, and a building limit set before that and increased by a small annual inflation factor is very likely short.
Being short does not just reduce a total loss payment. Most property forms carry a coinsurance requirement, and a building insured below the required percentage takes a proportional reduction on partial losses too, which is where the great majority of association claims land. A current replacement cost valuation, refreshed every few years, is the fix.
Getting the Association Reviewed
Send the declaration, the current declarations pages for every policy, the reserve study if you have one, and the unit count. We come back with where the master policy stops against what the declaration actually requires, whether the building limit holds up, and pricing from the carriers that write Illinois associations rather than one company’s answer.
Call or text 847.242.1040 or start online.
Association Insurance Questions
What is the difference between association insurance and condo insurance?
The association buys a master policy covering the building, common elements, and the board’s own liability. A unit owner buys an HO-6 covering personal property, liability, loss assessment, and whatever portion of the unit the master policy does not reach. They are different policies bought by different parties, and both are necessary.
Does the master policy cover the inside of my unit?
It depends entirely on the declaration. A bare walls policy stops at the studs and leaves drywall, flooring, cabinets, and fixtures to the owner. A single entity policy includes original finishes but not later upgrades. An all-in policy reaches furthest. Ask the board which one your declaration uses before you assume.
Does a condo association need directors and officers coverage?
Yes, and it is often the reason people are willing to serve on the board at all. Volunteers making decisions about assessments, rules, and architectural requests are exposed to suits from the owners they serve. Check whether defense costs erode the limit and whether non-monetary claims are covered, because those two terms decide how useful the policy is.
Who pays the master policy deductible?
Frequently the unit owner where the loss originated, if the declaration allows the association to assess it. Deductibles on Illinois association policies are often substantial, which is why loss assessment coverage on the owner’s HO-6 matters and why it should be bought at a meaningful limit rather than the default.
How much fidelity coverage should an association carry?
A common starting point is the reserve balance plus a few months of assessments, then checked against what your lenders and the secondary mortgage market require for a building your size. Confirm the policy is endorsed to cover the management company’s employees, since that is a separate grant and not included by default.
Our building limit has not changed in years. Is that a problem?
Very likely. Construction costs rose sharply and small annual inflation adjustments did not keep pace. Beyond the total loss risk, coinsurance means an underinsured building takes a proportional cut on partial claims as well, and partial claims are most of what associations file. A fresh replacement cost valuation is inexpensive relative to that exposure.