
Umbrella Insurance for North Shore Households
Coverage at a Glance
Select a person, pet, or object in the scene, a numbered marker, or a scenario below the picture to see how an umbrella policy adds protection above your other coverage.
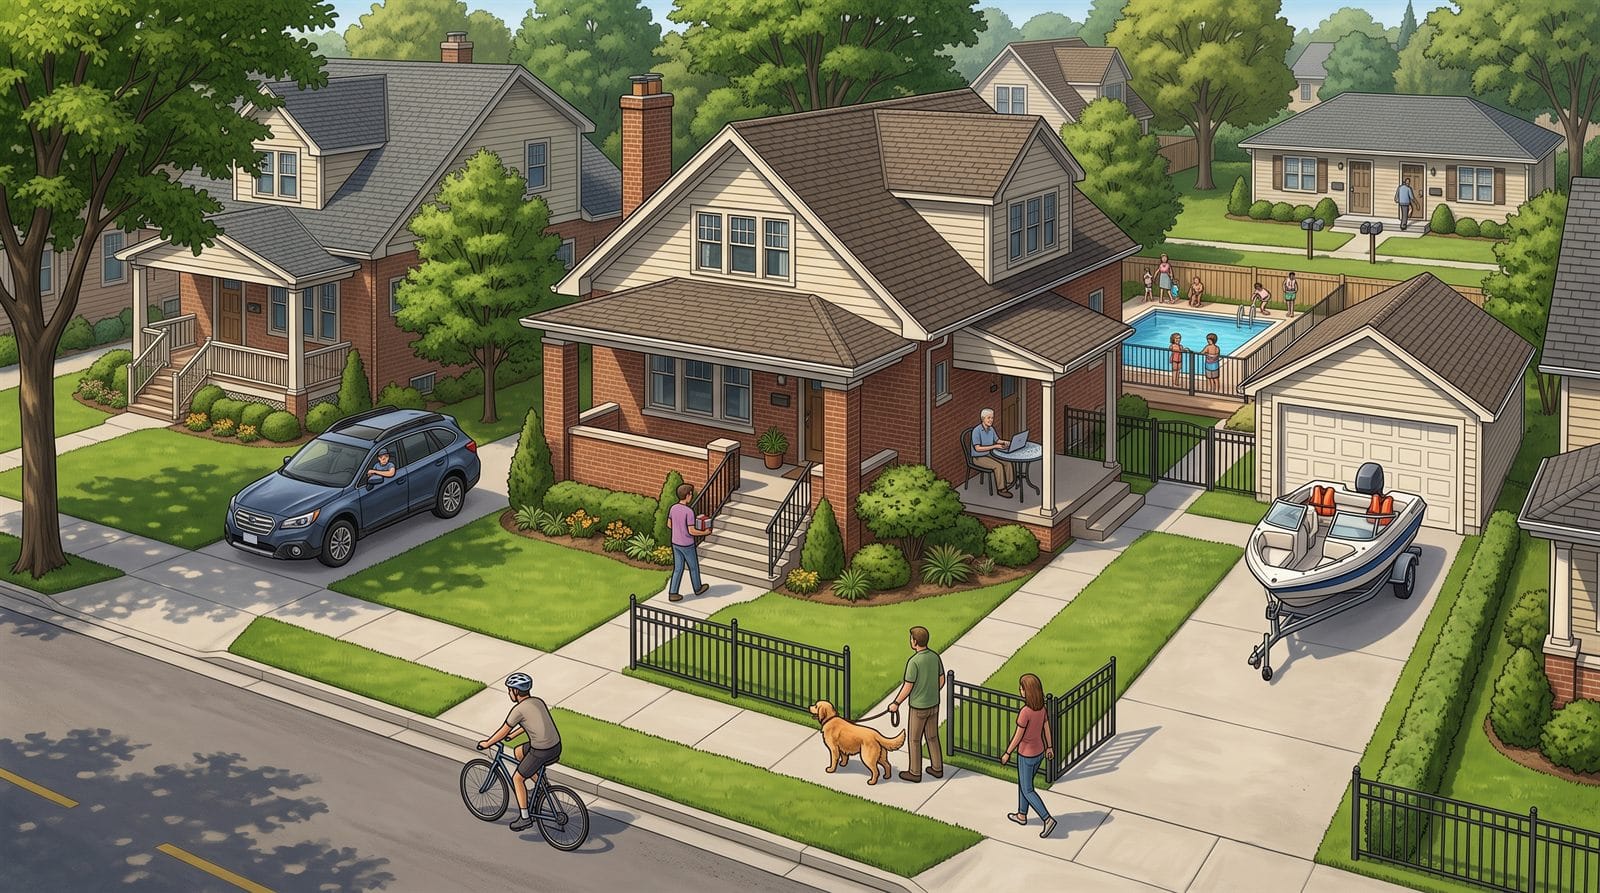
- Umbrella above auto liability
A serious accident can exceed your auto limits.
An accident involving several injured people can create substantial medical bills and liability claims. An umbrella can provide additional coverage above your auto liability limits for a covered accident. Make sure household drivers and vehicles are properly disclosed and the required underlying limits are maintained.
Coverage to coordinateAuto liability - Umbrella above auto liability
One injury can have lasting consequences.
If an insured family member causes a collision that seriously injures a cyclist, the claim may involve rehabilitation, lost income, and long-term care. Umbrella insurance can help with covered liability beyond the applicable underlying limit.
Coverage to coordinateAuto liability - Umbrella above homeowners liability
Even a familiar dog can cause an unexpected injury.
A bite or knockdown can lead to a significant injury claim. An umbrella may provide additional protection above your homeowners liability coverage. Review animal exclusions and disclose bite history; an umbrella should not be assumed to fill a dog-related exclusion.
Coverage to coordinateHomeowners liability - Umbrella above homeowners liability
Welcoming guests comes with liability exposure.
A visitor seriously injured on your property may claim that unsafe conditions caused the accident. If you’re legally responsible, an umbrella can help address covered damages beyond your homeowners liability limit. Legal defense is subject to the policy’s terms.
Coverage to coordinateHomeowners liability - Umbrella personal-injury coverage
An online comment can become a lawsuit.
A post, review, or shared statement can lead to allegations of libel, slander, or invasion of privacy. Some umbrella policies cover these personal-injury claims. Review the wording carefully, including exclusions for knowingly false statements, intentional harm, and business activities.
Coverage to coordinatePersonal-injury coverage - Umbrella above homeowners liability
A pool accident can create a major claim.
A severe swimming injury can result in a lawsuit far beyond an ordinary household claim. Umbrella insurance can add liability protection above the underlying homeowners policy. Confirm the pool is disclosed and review requirements involving fencing, diving boards, and slides.
Coverage to coordinateHomeowners liability - Umbrella above watercraft liability
Your liability exposure goes out on the water.
A boating collision or passenger injury can lead to substantial liability. An umbrella may extend protection above your watercraft liability policy. Confirm the boat is eligible and included, and that its underlying coverage meets the umbrella’s requirements.
Coverage to coordinateWatercraft liability - Umbrella above landlord liability
A rental property adds another place for claims.
If your family also owns this duplex, a tenant or visitor injury can create landlord liability. Some personal umbrellas cover eligible rental properties. Review the number of units, ownership structure, and required landlord liability coverage; rental properties are not automatically included.
Coverage to coordinateLandlord liability
Send us your home and auto declarations pages and we will check whether the underlying limits qualify.
Illustrative scenarios. Coverage depends on policy terms, exclusions, insured people and activities, and required underlying insurance.
An umbrella policy sits above the liability limits on your home and auto policies and pays when a judgment exceeds them. For most North Shore households it adds a million dollars or more of liability protection for a few hundred dollars a year, and it is the coverage we most often find missing.
Why Underlying Limits Run Out
A typical auto policy carries $250,000 or $500,000 of bodily injury liability per person. A homeowners policy carries $300,000 to $500,000 of personal liability. Those limits are well above the Illinois minimum and still short of what a serious injury claim can cost.
A multi-vehicle accident with injuries, a permanent disability, or a wrongful death claim moves past those limits quickly. Once the policy limit is paid, the remaining judgment attaches to you: savings, investments, rental property, business interests, and in Illinois, future wages.
How Much You Need
Use net worth as one input, alongside income exposure, household drivers, properties, and activities. Compare several umbrella limits and the premium difference. Asset protections vary, so a balance-sheet total is not a universal minimum limit.
We look at net worth, income and years to retirement, and specific risk factors: teenage drivers, a swimming pool, a trampoline, dogs, rental property, frequent entertaining, coaching or board service, and any public profile. A household with two teenage drivers carries meaningfully more exposure than the same household did three years earlier.
What It Costs
A $1 million umbrella typically runs $150 to $350 a year for a household with clean driving records. The second and third million cost considerably less than the first, because the probability of a claim reaching those layers drops sharply.
Carriers require minimum underlying limits, commonly $250,000 per person and $500,000 per accident on auto and $300,000 on home. Confirm the thresholds for the umbrella you choose. Falling below them can leave you paying a gap or affect coverage, so coordinate the limits before the policy starts.
Coverage Beyond Higher Limits
Many umbrella policies also cover some exposures the underlying policies leave out, including personal injury claims such as libel, slander, and false arrest, and in some forms liability arising from volunteer board service. For anyone who serves on an association board or a nonprofit board, that provision is worth reading.
Umbrella policies also pay legal defense costs, generally outside the policy limit. Defending a serious liability claim is expensive even when you prevail.
What a Covered Loss Looks Like
Umbrella coverage is easier to understand through arithmetic than through description. The following is an illustration built on assumed numbers, not a quote and not a promise about any particular claim, since every loss turns on its own facts and the wording of the policies involved.
Assume a household carries 250,000 per person of auto liability and a 1,000,000 personal umbrella. A driver in the household causes a serious multi-car accident and is found at fault. Two people are injured, one seriously, and the combined claim for medical costs, lost income and pain and suffering settles at 700,000.
- The auto policy pays first, up to its limit for the injured parties.
- The umbrella responds above that, covering the remainder of the settlement within its own limit.
- Defense costs are generally handled outside the limit on an umbrella, which matters because litigation on a claim this size is expensive on its own.
Without the umbrella, the amount above the auto limit is the household’s to pay, and a plaintiff can pursue savings, home equity and future wages to collect it. That gap, rather than the monthly cost, is the reason to carry one.
What an Umbrella Does Not Do
An umbrella raises liability limits. It does not repair gaps in the policies underneath it, and it is not a general-purpose safety net.
- Your own property and injuries. It is liability coverage for harm to other people. It does not pay to repair your house or your car, and it is not health coverage for your household.
- Anything the underlying policy excludes for the same reason. If a loss is excluded below because of the type of activity, the umbrella generally follows that exclusion rather than overriding it.
- Business activity, unless the policy is specifically endorsed for it. A home business, rental activity at scale, or board service may each need to be scheduled or covered elsewhere.
- Intentional acts, and in most forms criminal conduct.
- Unscheduled exposures. A boat, a rental property or a recreational vehicle acquired mid-term has to be added. The umbrella does not silently pick it up.
Whether your umbrella includes personal injury coverage, and on what terms, is worth confirming rather than assuming.
Common Questions
How much umbrella insurance do I really need?
Review the assets and income you want to protect, then consider drivers, rental property, boats, pools, and other activities. Compare several limits against their added cost and confirm the underlying policy requirements.
Does an umbrella cover my rental property?
It can, if the rental is scheduled on the policy and the underlying landlord policy meets the carrier’s limit requirement. Unscheduled rentals are a frequent gap.
Does it cover my business?
No. Personal umbrella policies exclude business activity. Business liability sits above a commercial general liability policy through a commercial umbrella instead.
Do all my policies have to be with one carrier?
Not always, though many carriers prefer it and price better when home and auto sit underneath their own umbrella. As an independent agency we can structure it either way.
Related Coverage
- Home insurance, one of the underlying policies
- Auto insurance, the other underlying policy
- Condo insurance for unit owners
- Our full guide to sizing an umbrella policy
Where We Write Umbrella Coverage
We write personal umbrella policies from our offices in Wilmette, Evanston, Elmhurst, Elk Grove Village, Antioch, Lakeview, Wicker Park, and North Center, and across Winnetka, Glencoe, Kenilworth, and Northbrook.
Get an Umbrella Insurance Quote
Send us your current home and auto declarations pages. We will tell you if your underlying limits qualify and what an umbrella costs on top. Call 847.242.1040 or request a quote online.
Erie Umbrella Coverage
As an appointed Erie Insurance agent we can place a personal umbrella with Erie where the underlying home and auto limits qualify, which is usually the simplest structure since everything sits with one carrier.
Where your home and auto are with different companies, or where the underlying limits fall short of Erie’s requirement, we look at standalone umbrella markets instead. Either way the review starts with your existing declarations pages.