
Technology Business Insurance
Coverage at a Glance
Select a numbered marker on the illustration, or a coverage name below it, to see where each coverage applies.
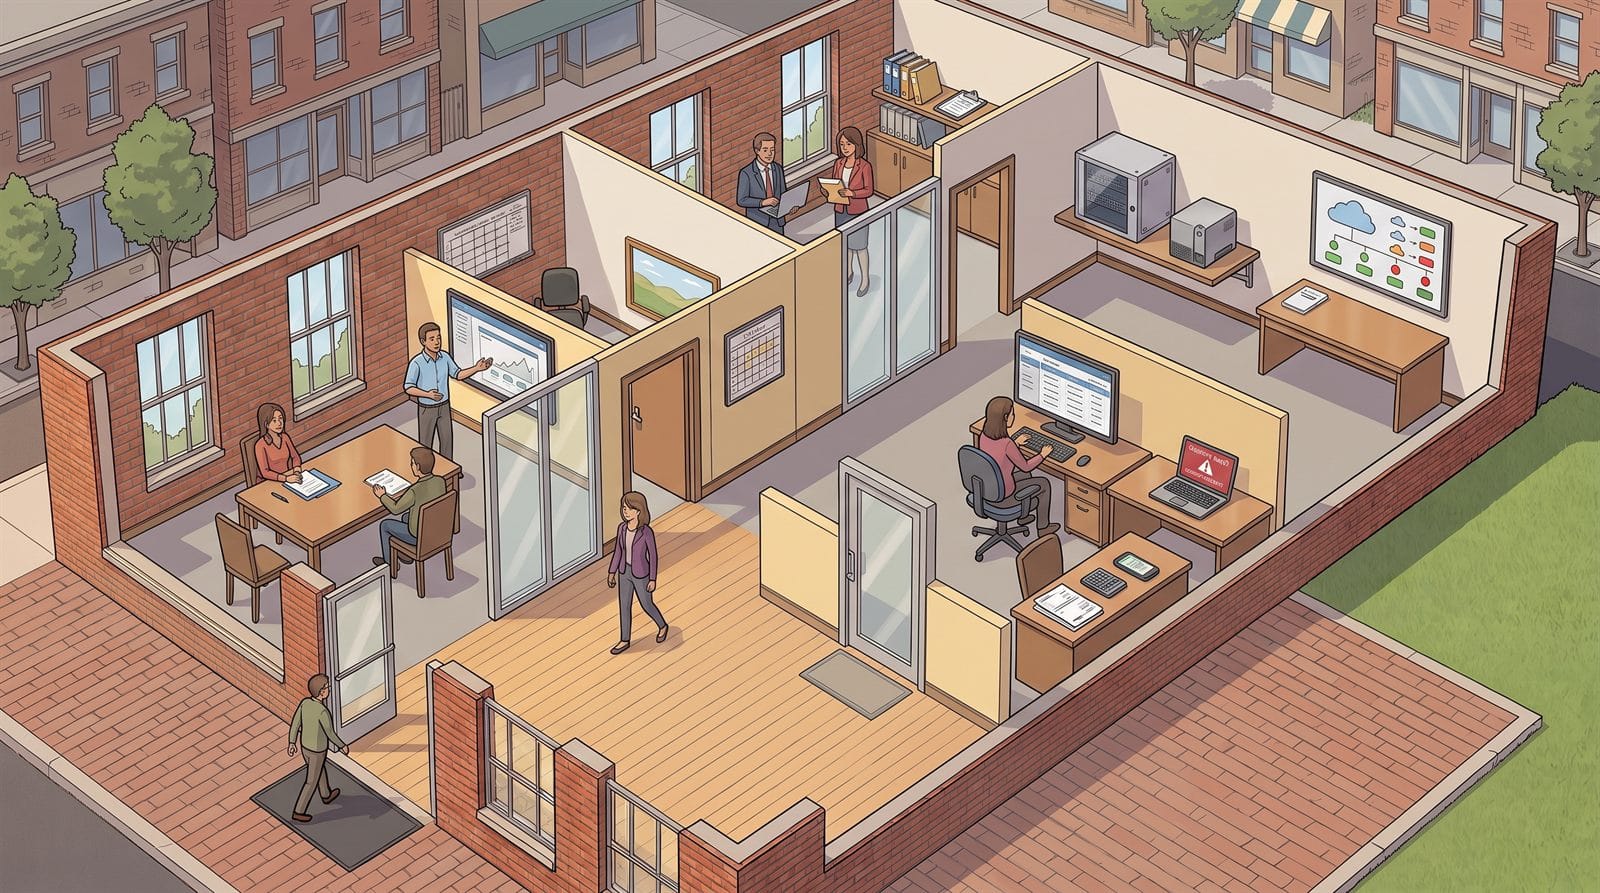
- Technology E&O
What if a software error costs your customer money?
Technology E&O can help with covered claims alleging that your software, product, or technology services caused a customer financial loss. Review your actual services, including development, implementation, hosting, and support. It isn’t a guarantee that every bug fix, refund, or performance promise is insured.
Testing and automation: Tell us about AI-enabled features, automated decisions, and any hardware your software controls.
- Tech E&O for implementations
An implementation can fail even without a cyberattack.
A failed integration, configuration mistake, or negligent recommendation can disrupt a client’s operations. Technology E&O may respond to qualifying claims. Tell us about client-system access, migrations, subcontractors, and managed services so the policy reflects your responsibilities.
- Coverage-planning topic: contracts
Does your coverage match the contract?
Review service-level commitments, indemnity provisions, and insurance requirements before signing. Tech E&O and cyber policies may not cover every obligation you voluntarily accept. Contractual penalties, service credits, and guarantees need specific attention.
- Coverage-planning topic: claims-made timing
Coverage timing matters when a claim arrives later.
Many tech E&O policies use claims-made or claims-made-and-reported terms. Review retroactive dates, reporting deadlines, and continuity when changing insurers or closing the business. An extended reporting period can provide additional reporting time for qualifying earlier work; it doesn’t insure new work.
- Privacy and security liability
What if client information is exposed?
Privacy and security liability coverage can help with covered claims arising from a data breach or security failure. Review the information you hold, systems you access, and responsibilities you accept for clients. Regulatory defense and penalties depend on policy terms and legal insurability.
- Cyber incident response
Who helps you respond to a cyber incident?
Cyber coverage may help fund forensic investigation, breach counsel, notification, data recovery, and other covered response costs. Ask about extortion coverage and incident-response services. Contact the insurer promptly; consent and approved-provider requirements can affect reimbursement.
- Cyber business interruption
What if your own systems stop working?
Cyber business interruption coverage can help with qualifying income loss and extra expenses after a covered security incident or system failure. Review waiting periods, restoration limits, and data-recovery protection. A nonmalicious outage may require broader coverage than an attack-only trigger.
- Dependent business interruption
Your provider’s outage can become your business interruption.
Dependent business interruption coverage may help when a covered event at a cloud or other qualifying provider disrupts your operations. Review covered providers, outage causes, waiting periods, and sublimits. Don’t assume every internet, hosting, or software-service failure qualifies.
- IP and media liability
Could your code or content trigger an infringement claim?
Some technology E&O or media liability coverage can address specified allegations involving copyright, content, or other intellectual property. Review licensed assets, third-party code, and the work you create for clients. Patent claims and other IP disputes may require separate protection or be excluded.
- Social engineering and crime
What if a payment request is fraudulent?
Impersonation scams can redirect vendor payments or trick employees into transferring funds. Ask specifically about social engineering, funds-transfer fraud, and employee dishonesty. Ordinary cyber coverage may not cover money voluntarily sent because of a convincing fake message.
- Directors and officers liability
Leadership decisions can create personal exposure.
Directors and officers liability insurance can help with covered claims alleging wrongful acts in managing the company. Consider ownership disputes, investor allegations, and fundraising activities. Review protection for individuals and the company, along with financing or transaction-related exclusions.
- Employment practices liability
Growing the team introduces employment risks.
Employment practices liability insurance can help with covered discrimination, harassment, and wrongful-termination claims. Review applicants, employees, contractors, and remote teams. Unpaid wages, overtime, and other wage-and-hour disputes often have exclusions or limited protection.
- General liability
Ordinary office accidents still matter.
General liability insurance can help with covered claims involving a visitor’s injury or damage to someone else’s property. This is separate from financial harm caused by your technology services. Review client-site work and any leased or shared office requirements.
- Property and portable equipment
Your equipment moves with your team.
Property and portable-equipment coverage can help with covered loss or damage to business hardware. Review equipment at home, in transit, and at client locations. Replacing a stolen laptop, recovering its data, and responding to a breach involve different coverage questions.
- Workers’ compensation
Protect employees in the office and beyond.
Workers’ compensation can provide benefits for covered work-related injuries or illnesses. Review remote employees, travel, installation work, and the states where staff work. A desk-based business still needs an accurate picture of its people and their duties.
Send us your current policies and a recent master service agreement, and we will tell you which of these you already carry.
Illustrative coverage options. Coverage must match your products, services, contracts, and data exposures. Reporting requirements, limits, deductibles, and exclusions apply.
Technology Business Insurance & Cyber Coverage for Illinois Tech Companies
A SaaS startup in Evanston, a managed service provider in Skokie, an IT consultancy in Northbrook, and a software developer anywhere on the North Shore share one core exposure: a client who says your software, advice, or outage cost them money. Insurance for tech companies starts with that claim, which a standard business policy excludes.
IT business insurance usually combines a specialty tech E&O and cyber policy with a standard package for general liability, property, and workers compensation.
What Tech Company Insurance Needs to Cover
Standard commercial policies weren’t designed for businesses whose primary assets are intellectual property, code, and data. Technology businesses need coverage that addresses professional liability for the services they deliver, the data they handle, and the digital infrastructure they depend on.
Key Coverages for Technology Businesses
- Technology Errors & Omissions: The cornerstone of tech insurance. Covers claims arising from software defects, system failures, project delays, data loss, and failure to deliver contracted services. If a client says your product or service cost them money, Tech E&O pays your defense and covered damages.
- Equipment Breakdown: Protects your servers, networking equipment, development hardware, and office technology against mechanical and electrical failure.
- Income Protection (Actual Loss Sustained): If a covered event disrupts your operations, income protection covers lost revenue after covered physical damage. A system outage without physical damage falls under cyber business interruption instead.
- Data Breach Response Expenses: Covers the immediate costs of responding to a data breach: forensic investigation, customer notification, credit monitoring, public relations, and legal counsel.
- Data Breach Liability: Covers third-party lawsuits, regulatory fines where insurable, and PCI penalties arising from a breach of data in your custody.
- Employment Practices Liability: Tech companies compete aggressively for talent, which creates exposure for claims of discrimination, wrongful termination, wage disputes, and hostile work environment.
Who We Insure
- Software development companies (SaaS, custom, mobile)
- Managed service providers (MSPs) and IT consultants
- Web design and digital marketing agencies
- Data analytics and AI companies
- Cybersecurity firms
- Cloud hosting and infrastructure providers
- Fintech and healthtech startups
- E-commerce platform providers
For a technology business insurance quote, send us your current policies and a recent client contract, or call 847.242.1040.
Serving technology companies in Wilmette, Northfield, Winnetka, Glencoe, Kenilworth, Evanston, Northbrook, Highland Park, Glenview, Skokie, and across Chicago’s North Shore.
Business Insurance Resources
Where Technology Businesses Are Exposed
For a software or IT services company, the expensive claims rarely involve property. They involve a client saying your work cost them money.
- Technology errors and omissions, often called tech E&O or tech liability insurance. Covers claims that your product or service failed to perform as promised, missed a deadline, or caused a client financial loss. General liability specifically excludes this.
- Cyber liability. Covers your own breach response and the claims that follow when client data is exposed while in your care.
- Media liability. Covers copyright and trademark claims arising from content, code, or interfaces you produce.
- General liability. Still needed for the ordinary case where a visitor is injured or you damage a client’s property on site.
- Commercial property and equipment. Laptops and hardware, including gear at employee homes, which most standard forms handle poorly for distributed teams.
Combined Tech E&O and Cyber
Most technology carriers now write errors and omissions together with cyber on one form. That matters because a single incident often triggers both. A failure in your platform that exposes a client’s customer data is simultaneously a performance failure and a breach, and separate policies from separate carriers can each argue the other should respond.
Contract Terms Drive the Coverage
Client agreements, especially with larger enterprises, specify required limits, indemnification obligations, and sometimes the exact coverage forms you must carry. Where your contract accepts liability beyond what your policy covers, you have taken on an uninsured obligation.
We read the insurance and indemnity language in your master service agreements before placing coverage. Limitation of liability clauses matter as much as your policy limits.
Claims Made and Retroactive Dates
Technology E&O is written on a claims-made basis, meaning the policy in force when the claim is filed responds, not the one in force when the work was done. Two consequences follow.
Before changing or ending coverage, compare the retroactive date, prior-acts protection, and claim-reporting deadline. An extended reporting period provides time to report qualifying claims from earlier work; it does not insure new projects. We check these details so a switch does not leave completed work behind.
Related Coverage
Erie and Specialty Technology Markets
As an appointed Erie Insurance agent we can place the general liability, office property, and workers compensation portion of a technology company’s program with Erie where it fits.
Technology errors and omissions and cyber liability generally come from specialty carriers rather than standard markets, so most technology accounts end up structured across more than one company. We build that combination and compare it against what a single-carrier program would cost and cover.