
Auto Services & Garage Insurance
Coverage at a Glance
Select a numbered marker on the illustration, or a coverage name below it, to see where each coverage applies.
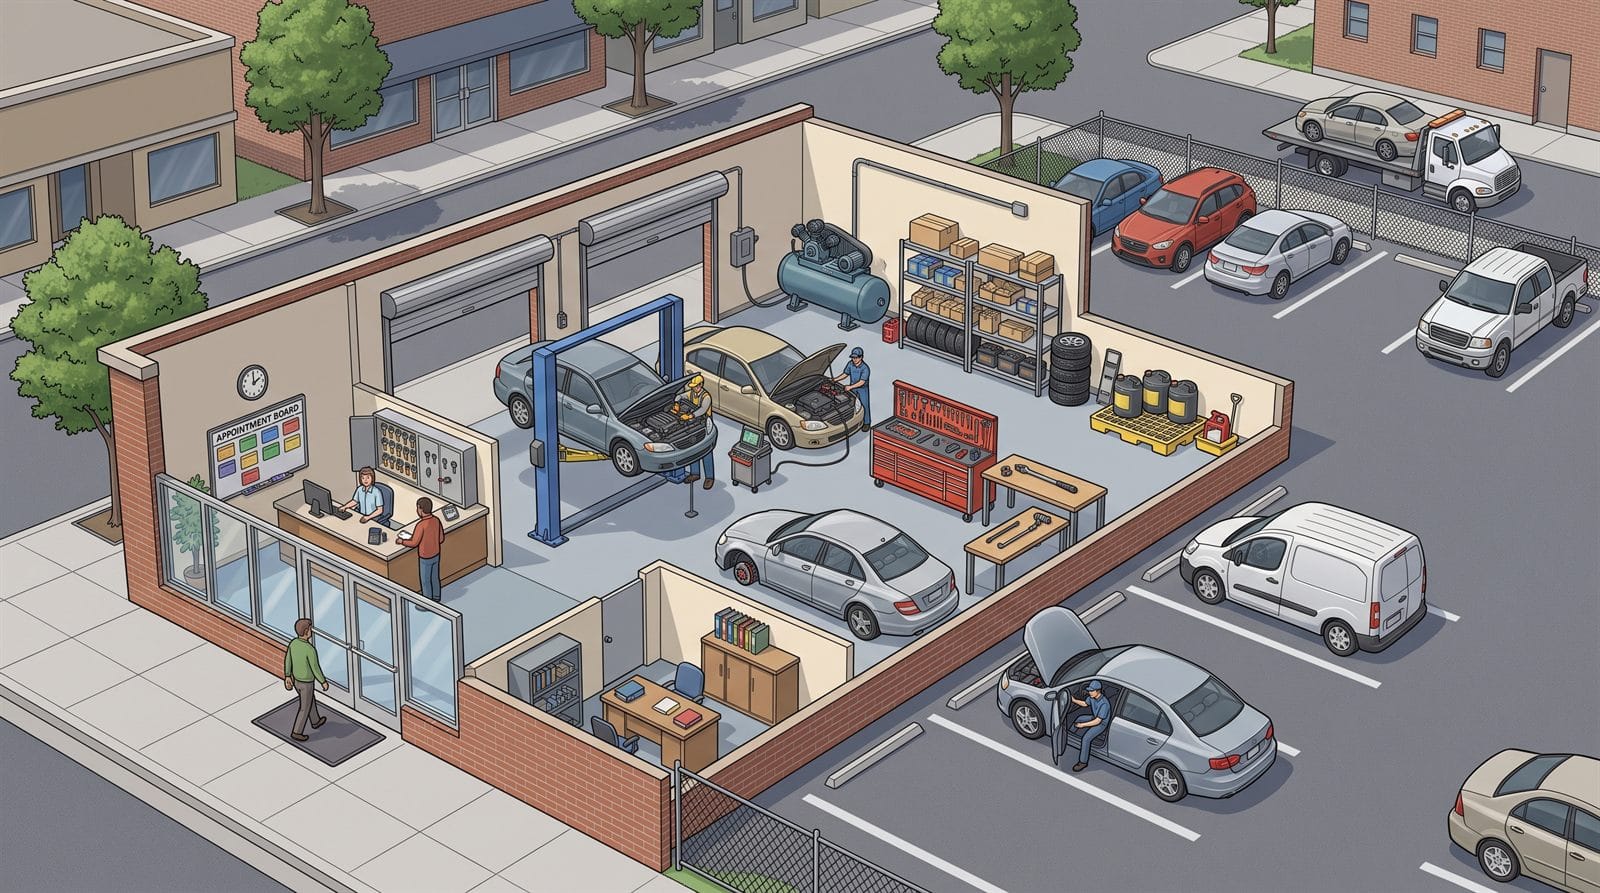
- General and garage liability
What if a customer gets hurt at your shop?
General or garage liability coverage can help with covered claims when your operations cause bodily injury or damage to someone else’s property. A customer’s slip-and-fall is one example. Damage to vehicles entrusted to you needs a separate garagekeepers coverage review.
- Garagekeepers coverage
You’re responsible for more than your own property.
Garagekeepers coverage addresses covered damage to customers’ vehicles in your care. Ask whether it applies only when you’re legally liable or offers direct coverage regardless of fault, subject to its terms. Limits should reflect the maximum value of vehicles you hold at one time.
Key cabinet: Review key security, theft conditions, and coverage for vehicles stored outside.
- Garagekeepers collision
What if a customer’s car is accidentally damaged during service?
A vehicle falling from a lift or being struck inside the shop can create a garagekeepers claim, depending on the coverage and circumstances. Review collision protection and deductibles. Accidental vehicle damage and the cost of correcting faulty work are different coverage questions.
- Test-drive liability
Your responsibility continues out on the road.
A test-drive accident can damage the customer’s car and injure someone else. Review liability protection for driving customer vehicles alongside garagekeepers coverage for the vehicle itself. Confirm authorized drivers, pickup and delivery services, and any use restrictions.
- Completed operations and faulty work
A repair can lead to a claim after the customer leaves.
Completed operations coverage may respond if your work later causes covered injury or property damage. Paying to redo an incorrect repair is a separate issue. Ask about available faulty-work coverage and its limits; ordinary liability insurance isn’t a workmanship warranty.
- Workers’ compensation
Protect the people doing the repairs.
Workers’ compensation pays medical bills and lost wages for covered work injuries and illnesses, and Illinois requires it from your first employee. Review technicians, service advisers, drivers, and any mobile work. Employee injuries generally aren’t covered by the liability protection intended for customer claims.
- Tools and equipment coverage
Could you replace the tools that keep the shop working?
Property or tools coverage can help after covered theft or damage. Include diagnostic scanners, specialty tools, and equipment taken off-site. Clarify ownership: tools personally owned by technicians may have limited protection or require a separate arrangement.
- Commercial property
A shop fire can affect your building, parts, and equipment.
Commercial property coverage can help restore insured building property, improvements, equipment, and inventory after a covered loss. Review leased-space responsibilities and peak parts values. Customers’ vehicles require their own garagekeepers protection rather than relying on ordinary property coverage.
- Equipment breakdown
One equipment failure can take bays out of service.
Equipment breakdown coverage can help with qualifying sudden mechanical or electrical failures of insured shop equipment. Review repair costs and related income-loss protection. Ordinary wear, maintenance, and replacing worn-out equipment generally aren’t covered breakdowns.
- Business income and extra expense
The appointments stop, but expenses continue.
Business income coverage replaces lost profit, plus continuing expenses like rent and payroll, while you recover from covered physical damage. Extra expense coverage may help you resume service sooner. Review waiting periods, restoration limits, and downtime from insured equipment breakdowns.
- Commercial auto
Business vehicles need their own protection.
Commercial auto insurance can cover qualifying liability claims involving shop vehicles, with separate options for vehicle damage. Tell us about parts runs, roadside service, and customer transportation. Employee-owned vehicles used for errands need a hired and non-owned auto review.
- On-hook and towing coverage
Towing creates a separate customer-vehicle exposure.
If your business tows or hauls vehicles, review on-hook or cargo protection for covered damage during transport. Garagekeepers coverage at your storage location may not cover the entire trip. Confirm loading, unloading, towing methods, and vehicle-value limits.
- Pollution liability
A fluid spill can create environmental liability.
Used oil, coolant, solvents, and other materials can create cleanup and third-party claims. Pollution coverage may address specified incidents that ordinary policies exclude. Review storage, handling, and waste-disposal arrangements, including whether off-site exposures are covered.
- Cyber insurance
Customer records and shop systems need protection, too.
Cyber insurance pays the response costs after a covered breach or ransomware attack. Review customer information, payment systems, and digital service records. Ask about income loss if a covered cyber event interrupts scheduling, diagnostics, or checkout.
- Employment practices liability
Employment disputes are separate from repair claims.
Employment practices liability insurance pays defense costs and covered damages when an employee claims discrimination, harassment, or wrongful termination. Review who is insured and whether third-party claims are included. Wage-and-hour disputes and unpaid compensation often have exclusions or limited protection.
Send us your current garage policy and we will mark which of these coverages it already includes.
Illustrative coverage options. Coverage depends on your services, vehicle custody, drivers, and policy terms. Limits, deductibles, and exclusions apply.
Garage Insurance for Auto Repair Shops on Chicago’s North Shore
An auto service business spends every day holding cars it does not own, and that custody is where standard commercial policies fall short. The exposure is the same for an independent mechanic in Wilmette, a collision center in Evanston, or a tire shop in Northbrook.
We place garage coverage with carriers that write auto service shops as a class, and we set it up around how your shop handles customer vehicles.
Why Auto Service Businesses Need Specialized Coverage
Customer cars create several separate coverage questions: damage while in your care, liability during a test drive, and a claim arising from faulty work. Review garagekeepers and garage or business-auto coverage together; paying to redo a repair is different from paying for resulting damage.
Key Coverages for Auto Repair Shops & Service Centers
- Garage Liability: Covers bodily injury and property damage arising from your garage operations: from test drives to customer interactions on your lot.
- Garagekeepers Legal Liability: Protects customers’ vehicles while they’re in your care, custody, or control, whether damaged by fire, theft, vandalism, or collision.
- Equipment Breakdown: Modern shops rely on computerized diagnostic tools, lifts, alignment machines, and paint booths. Equipment breakdown coverage protects against mechanical and electrical failure of this critical infrastructure.
- Income Protection: If a covered loss forces your shop to close temporarily, income protection covers your lost income on an actual loss sustained basis, up to the policy’s time limit.
- Data Breach Response: Today’s shops store customer payment info, vehicle data, and personal records digitally. Data breach coverage handles notification costs, credit monitoring, and forensic investigation if your systems are compromised.
- Broadened Liability for Defective Products & Faulty Work: Sometimes called Mechanic’s E&O, this covers claims arising from defective parts you installed or faulty repair work, which standard garage policies often leave out.
- Hired and Non-Owned Auto Liability: addresses qualifying rented or employee-owned vehicles used for business. Confirm customer-car test drives under the garage or business-auto coverage and review damage to the car under garagekeepers.
Who We Insure
- Independent auto repair and mechanic shops
- Collision and body repair centers
- Oil change and quick lube facilities
- Tire shops and wheel alignment centers
- Auto detailing businesses
- Transmission and specialty repair shops
- Car wash operations (with dedicated car wash enhancement endorsements available)
Getting a Garage Insurance Quote
To quote, we need the services you offer, the most customer vehicles you hold at one time, and your current declarations page.
For an auto services insurance quote, call 847.242.1040 or request one online.
We serve auto service businesses in Wilmette, Northfield, Winnetka, Glencoe, Kenilworth, Evanston, Northbrook, Highland Park, Glenview, Skokie, and across Chicago’s North Shore.
Related Resources
Garage insurance should match how vehicles move through your business
Auto repair shops, service centers, detailers, tire shops, body shops, and specialty garages do not all have the same insurance exposure. A shop that test-drives customer vehicles, stores cars overnight, loans vehicles, picks up parts, or allows employees to move cars between locations needs coverage designed around those real operations.
The key issue is care, custody, and control. Customer vehicles may be damaged by fire, theft, vandalism, collision, lift failure, employee error, or weather while they are in your possession. Garagekeepers coverage, garage liability, business auto, property, tools, equipment breakdown, workers compensation, and cyber/POS coverage should be reviewed together instead of separately.
Certificates, leases, and dealer/customer requirements
Many auto service businesses lease space, work with fleets, service dealer vehicles, or need certificates for landlords and commercial customers. Those requests may require additional insured wording, waiver of subrogation, primary/non-contributory language, specific liability limits, garagekeepers limits, and proof of workers compensation.
Longmeadow Insurance helps Chicago and North Shore auto service businesses compare those requirements against the actual policy so certificate requests do not turn into last-minute problems.
What to review before renewal
Before renewing, confirm average and maximum customer vehicle values, overnight storage, employee driving, test-drive procedures, loaner vehicles, tools and diagnostic equipment, business income needs, cyber exposure, and whether any new services have been added. A policy that worked when the shop was smaller may not fit after growth or operational changes.
Related Insurance Guides
Erie Garage Insurance and Other Markets
Auto repair and service is a class Erie Insurance writes, and we quote it as an appointed Erie agent for shops across Chicago and the North Shore. Garagekeepers coverage, general liability, commercial property, and workers compensation can sit on one program.
Garage risks are underwritten closely on the specifics: customer vehicle values in your care, whether you do towing, body work versus mechanical, and lot security. Those details move accounts between carriers, so we quote Erie against the other markets writing this class rather than defaulting to one.