
Life Insurance for North Shore Families and Business Owners
Life insurance covers the one loss property insurance cannot: the income, the parent, or the business partner a household depends on. For North Shore families with a large mortgage, children still in school, a business, or an estate plan, the amount should come from adding up what the money would have to pay for, rather than a multiple of salary off a chart. We start with that number, then compare carriers, because they class the same health history differently.
Term Life Insurance
Term life insurance provides a death benefit for a defined period, typically 10, 20, or 30 years, at a fixed annual premium. It’s the most straightforward and generally the most cost-effective way to replace income, cover a mortgage balance, or provide for dependents during the years when those needs are greatest.
For a North Shore family with a mortgage and children at home, term is usually the place to start. The key decisions are the coverage amount, the term length, and the carrier’s financial strength and claims reliability. We model these variables against each household’s actual financial obligations rather than applying a generic multiple-of-income rule.
Whole Life Insurance
Whole life insurance provides permanent death benefit coverage that does not expire after a term, and it builds cash value over time that can be accessed during the policyholder’s lifetime. Premiums are higher than term for the same death benefit, but they’re guaranteed to remain level for life, and the policy’s cash value grows on a tax-deferred basis.
Whole life is often the right structure for households with estate planning objectives, providing liquidity to cover estate taxes, funding an irrevocable life insurance trust, or making sure that a surviving spouse maintains financial position without having to liquidate other assets. It’s also used for business succession planning and key person coverage where permanence of the benefit matters. Because it costs more than term for the same death benefit, it earns its place only where the need is permanent.
Universal Life Insurance
Universal life insurance offers permanent coverage with more flexibility than whole life. Premiums and death benefit amounts can be adjusted within limits over the life of the policy, and cash value growth is tied to current interest rates or, in the case of indexed universal life, to a market index with downside protection.
Universal life can be an appropriate structure for business owners who need flexibility as their income and business value fluctuate, or for households where the life insurance need is likely to change over time in ways that make the rigidity of whole life less attractive. The trade-off is complexity. Universal life policies require more active management than term or whole life, and the projections that make them look attractive at illustration stage depend on assumptions that need to be reviewed periodically.
Start With What the Household Would Lose
For most families this is the whole question, and the specialty uses further down this page are secondary to it. Life insurance replaces income the household was counting on and clears the debts that would otherwise land on whoever is left.
Income replacement
Work out what the household actually spends in a year, subtract what would still come in, and multiply by the number of years that gap needs to be covered. For a family with young children that horizon usually runs until the youngest finishes school. This produces a more useful figure than a multiple of salary, because it reflects your obligations rather than an average household’s.
The mortgage
Clearing the balance removes the largest fixed cost a surviving spouse would carry, and on the North Shore it is often the single biggest line in the calculation. Whether to pay it off outright or fund the payments is a real choice, and it changes the amount you need.
Dependents and the non-earning spouse
Education is the obvious one. The one households skip is coverage on a spouse who does not earn a wage. Replacing childcare, household management and everything else that role absorbs is a genuine cost, and it arrives at exactly the moment the surviving parent has least capacity to take it on.
Count what already exists before buying more. Group coverage through work is real but usually ends when the job does, which is why we treat it as a supplement rather than a foundation.
Life Insurance for Business and Estate Planning
Life insurance also has business and estate planning uses. The most common ones for North Shore clients are:
- Key person insurance: protects a business against the financial impact of losing an owner, founder, or critical employee whose expertise or relationships are central to the company’s value
- Buy-sell agreement funding: provides the liquidity for a surviving business partner to purchase a deceased partner’s ownership stake at a pre-agreed value, avoiding forced sales or family involvement in the business
- Estate liquidity: provides cash to cover estate taxes and settlement costs without requiring heirs to liquidate real estate, business interests, or investment portfolios at inopportune times
- Irrevocable life insurance trusts (ILITs): removes the death benefit from the taxable estate while preserving the proceeds for heirs; we coordinate with estate attorneys on policy ownership and beneficiary structure
- Survivorship life insurance: insures two lives under a single policy, paying the benefit on the death of the second insured; often used for estate planning couples where the primary objective is wealth transfer to the next generation
How Longmeadow Approaches Life Insurance
We don’t lead with product. We start with what the money has to do: the obligations it must cover, and what would happen to the household if the main earner or a business partner died tomorrow. The product and the amount follow from that.
We also assess existing coverage, including employer group life policies, policies purchased years ago that may no longer be appropriately sized, and structures that made sense at one life stage but no longer fit the household’s current financial picture. We review life coverage with clients on a regular cadence, as their families and the insurance market change.
Where the policy is part of an estate plan or a buy-sell agreement, we work with your attorney and financial advisor so ownership and beneficiary designations match the plan.
Coverage at a Glance
These are possible uses of a life insurance death benefit, rather than separate coverages. Beneficiaries generally decide how to use the proceeds. Select a part of the home, a numbered marker, or a need listed below the picture.
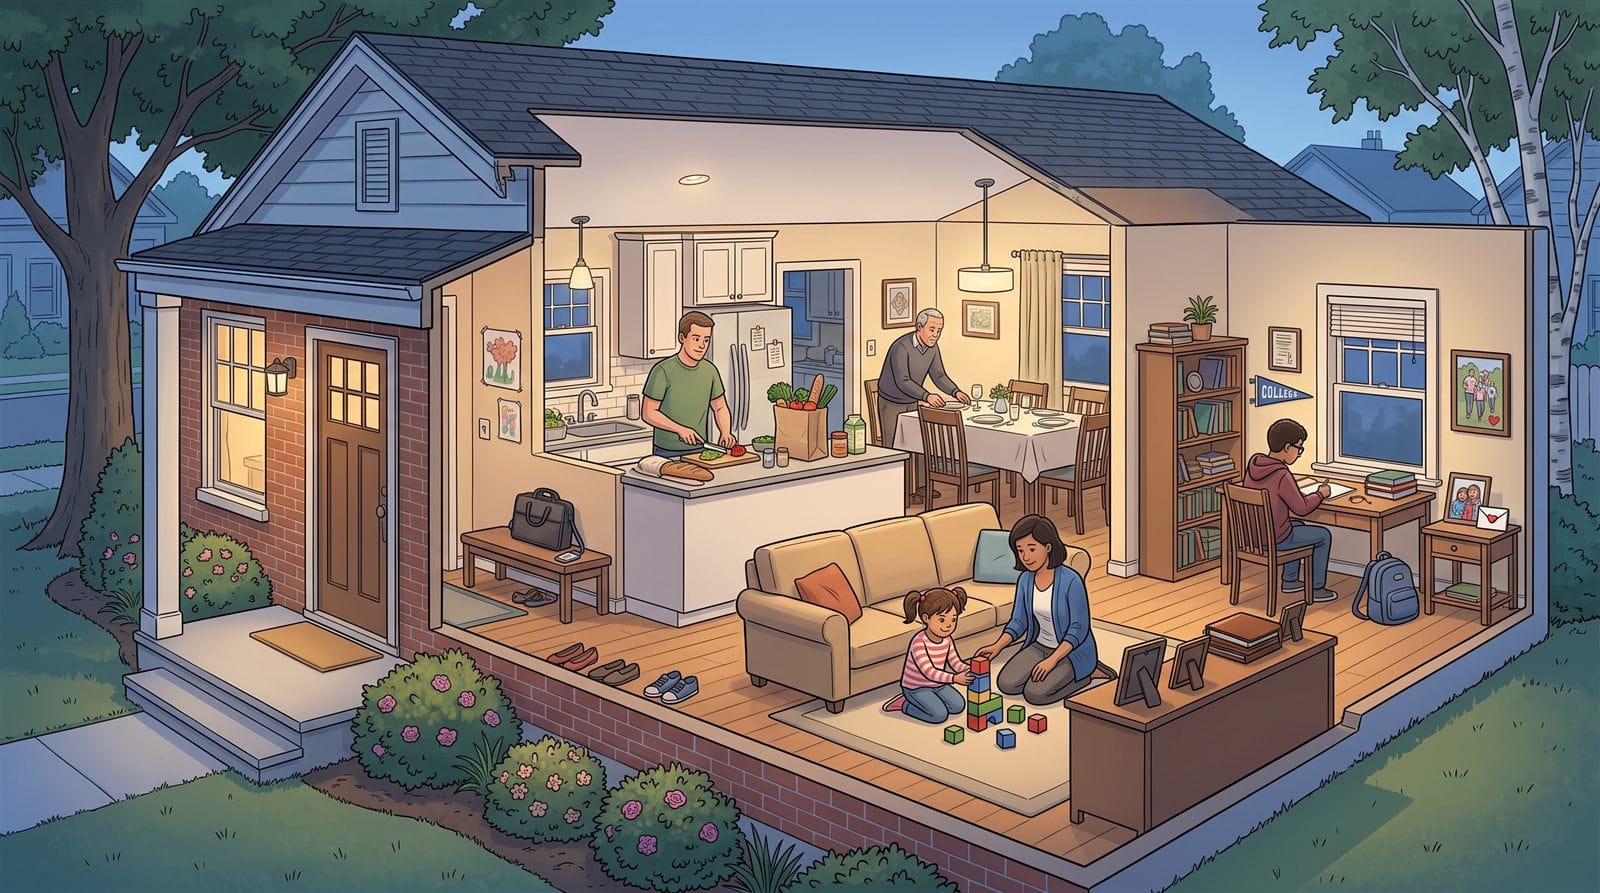
- Keeping the family home
Help them stay in the home they know.
If you died, could your family comfortably keep up with the mortgage? Life insurance proceeds could help pay down the balance or support ongoing payments, giving your family more choice about where to live.
- Everyday living expenses
Everyday bills keep coming.
Groceries, utilities, transportation, and other household expenses continue after a death. A life insurance benefit can provide funds for those everyday needs while your family adjusts and makes longer-term financial decisions.
- Childcare and household support
A parent’s contribution goes beyond a paycheck.
Childcare, school pickups, cooking, and household management have real financial value. Life insurance on a stay-at-home or working parent could help pay for additional care and support if that parent died.
- Education goals
Keep their next chapter within reach.
You may already be planning for college, vocational training, or other educational opportunities. Life insurance proceeds can help preserve those goals if you’re no longer there to contribute. Consider existing education savings when deciding how much protection your family needs.
- Replacing lost income: the overall need
Help replace the income they depend on.
Your paycheck may support years of household needs and future plans. Life insurance can provide a financial cushion after your death. Consider how long your family would need support, alongside a surviving partner’s income, savings, and existing coverage.
NoteThe other markers illustrate expenses within this overall need; they are not separate amounts to add together. - Supporting aging parents
Remember everyone who depends on you.
If you help an aging parent with housing, everyday expenses, or care, your death could leave a financial gap. Include that support in your life insurance planning, and coordinate beneficiary arrangements with the people you want to help.
- Final expenses and breathing room
Give them room to make decisions.
Funeral expenses and other immediate costs can add financial pressure during a difficult time. Life insurance proceeds can help with these expenses and provide a cushion, giving the family some room while they decide what comes next.
- Leaving a legacy
Support something that matters to you.
Life insurance can also help you leave a gift to a charity or community organization. Naming an eligible organization as a beneficiary can direct some or all of the death benefit toward a cause you value.
Tell us what the money would need to pay for, and we will size a policy around it.
Illustrative uses of life insurance proceeds. Payment depends on the policy being in force and its terms. Beneficiary designations determine who receives the benefit.
Helpful Insurance Guides
These related guides explain common coverage questions in more detail.
- When life insurance is required by a mortgage, divorce decree, or business loan
- What to expect from the life insurance application and underwriting process
- understanding life insurance rate classes
Getting a Term Life Quote
Term is the right answer for most households, and the quoting process is simpler than people expect. We need four things to price it: your age, whether you use nicotine, roughly how much coverage, and for how long. Everything after that is underwriting.
How much coverage
Rather than a multiple of income, we add up what the money has to do: pay off the mortgage, replace income for the years it is actually needed, fund education, and cover final expenses. Then we subtract what already exists, including group coverage through work, which usually ends when the job does.
How long
Match the term to the longest obligation. Years left on the mortgage, or years until the youngest child finishes school, whichever runs further. Buying a term longer than the need costs money for a risk that has already ended.
Which carrier
Carriers underwrite the same medical history differently, and a condition one company rates up, another may class standard. We shop the file rather than the applicant, which matters most for anyone with a health history worth explaining.
What the Process Looks Like
- A short conversation. Coverage amount, term, and health history. Fifteen minutes.
- Informal quotes from several carriers, so you can see the spread before applying.
- Application and underwriting path. Accelerated with no exam where you qualify, fully underwritten where it produces a better class.
- Underwriting. Days for accelerated, several weeks for fully underwritten with records.
- Offer and placement. If the class comes back worse than quoted, we take it to other carriers before you accept.
That last step is the one that gets skipped when people buy direct. A rated offer from one carrier is one company’s answer, not the market’s.
Common Questions
How much term life insurance do I need?
Add the mortgage balance, the income you would want replaced for the years it is needed, education costs, and final expenses, then subtract existing coverage and liquid assets. That figure is more useful than a multiple of salary, because it reflects the obligations your household actually has.
Is term or whole life better?
For covering a mortgage and raising children, term does the job at a fraction of the cost. Permanent coverage earns its place when the need does not expire: estate liquidity, a special needs dependent, business continuity, or funding a buy-sell agreement. Many households end up with term now and a small permanent policy alongside it.
Do I need a medical exam?
Often not. Accelerated underwriting can offer competitive rate classes without an exam for eligible applicants. Higher amounts or a more detailed health history may require records, labs, or an exam. We compare the routes available for your application.
Is the life insurance through my job enough?
Rarely, and it has a second problem: it usually ends when the employment does, often at exactly the moment a household can least absorb the loss. Group coverage is worth counting, but it is not a substitute for a policy you own.
What happens when the term ends?
Coverage stops unless you renew, and renewal rates after the level period rise steeply each year. Most level term policies include a conversion privilege that lets you convert to permanent coverage without new underwriting, usually within a defined window. That privilege is worth checking before you buy, not after.
Can I get life insurance with a health condition?
Usually yes, and the carrier you apply to matters more than most people realize. Diabetes, treated cancer history, sleep apnea, and mental health treatment are all underwritten differently across companies. This is exactly the situation where shopping several carriers changes the outcome rather than just the price.
A Life Policy Can Lower Your Home and Auto Premium
This is the part most households do not know. Several carriers, Erie among them, count a life policy toward the multi-policy discount on home and auto. Adding life to an existing account can reduce what you pay on the other lines, which offsets part of the life premium itself.
How much depends on the carrier, the state, and which policies you hold, so it is not a number we can quote in the abstract. It is worth asking about directly, because the household that assumes life insurance is purely an added cost is often looking at a smaller net figure than they expect once the discount is applied.
We run that math as part of the review. Send us your current home and auto declarations pages along with what you are considering for life, and we will show you the combined cost both ways rather than pricing life in isolation.
Erie Life Insurance
Erie writes life insurance, and as an appointed Erie Insurance agent we can quote term, whole, and universal policies alongside your home and auto coverage.
Life insurance is the line where shopping across carriers matters most, because underwriting classes differ considerably between companies for the same health profile. We quote Erie and compare it with the other life markets available to us before recommending anything.