
Veterinary & Pet Care Insurance
Coverage at a Glance
Select a numbered marker on the illustration, or a coverage name below it, to see where each coverage applies.
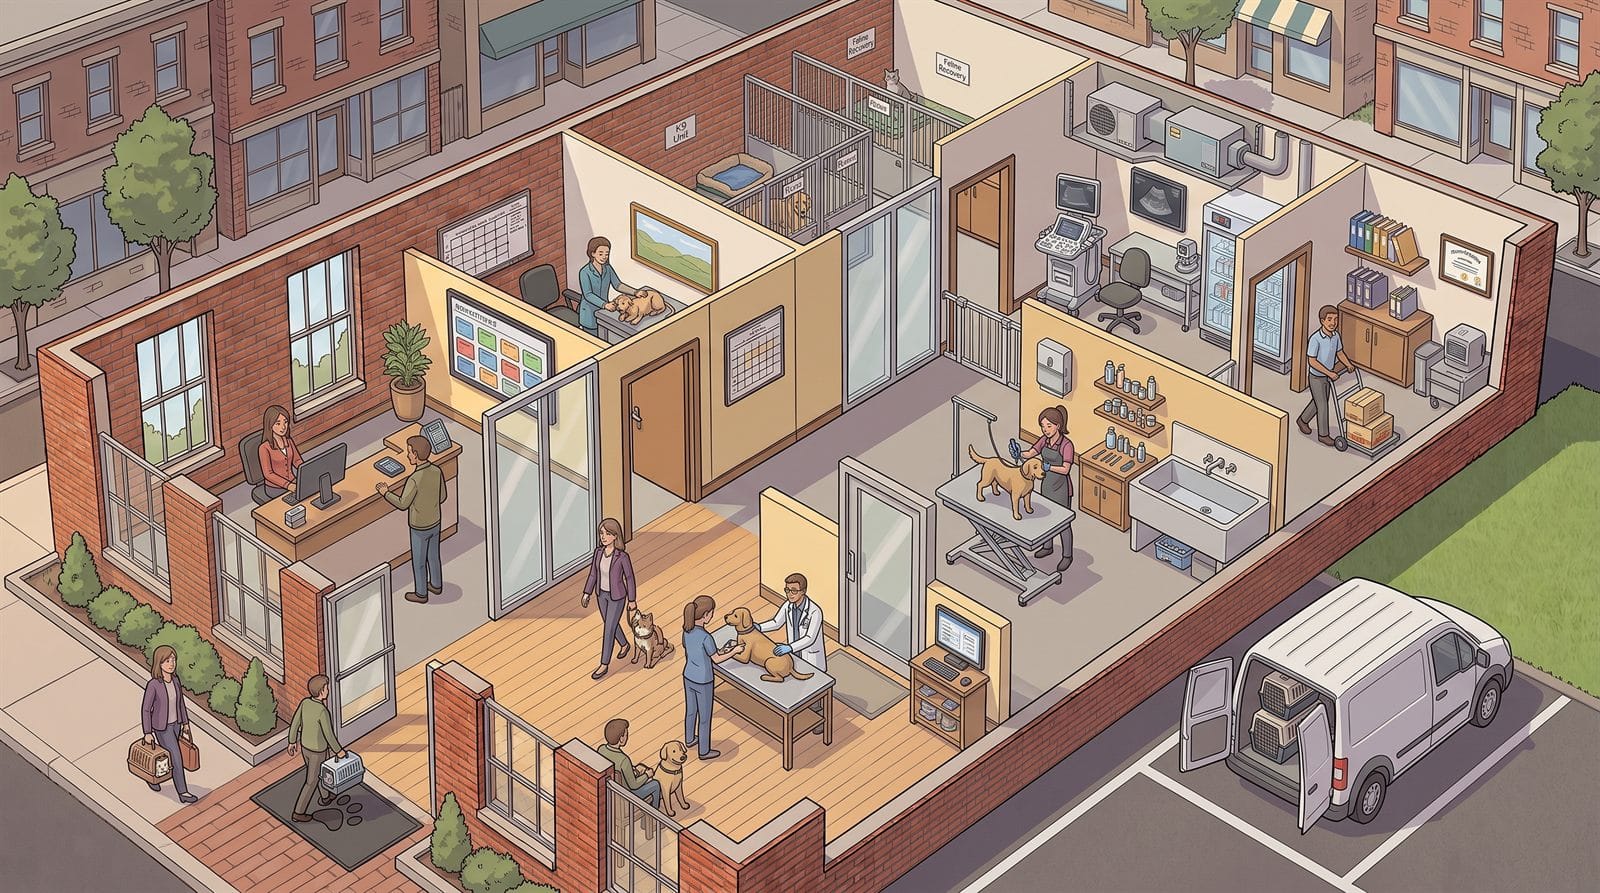
- Veterinary professional liability
What if a client alleges a treatment error?
Veterinary professional liability can help with covered allegations involving diagnosis, treatment, or other professional services. Review protection for individual veterinarians and the practice entity, including relief staff and specialized procedures. General business liability isn’t a substitute for veterinary malpractice coverage.
- Groomers’ professional liability
What if an animal is injured during grooming?
Groomers’ professional liability can help with covered claims arising from grooming services, such as an alleged clipping or handling error. Confirm the services and people insured. Review how this protection works with animal bailee coverage; the two aren’t interchangeable.
- Animal bailee coverage
Animals in your care need specific protection.
Animal bailee coverage can address qualifying injury, death, or loss of animals entrusted to your business outside professional treatment. Review per-animal and total limits against the most animals you hold at once. Overnight care, evacuation, and emergency veterinary expenses need specific attention.
- Escape and recovery (animal bailee)
What if a pet escapes?
Animal bailee protection may include qualifying escape losses and specified expenses to recover a missing animal. Ask about search costs, advertising, rewards, and applicable limits. Confirm that coverage follows the animal during handoffs, outdoor walks, and any other services you provide.
- General liability
What if a client slips and falls?
General liability insurance can help with covered claims when your business is legally responsible for a visitor’s injury or damage to someone else’s property. This protection serves a different purpose from professional liability and coverage for animals in your custody.
- Animal bites and liability
A bite can involve different policies depending on who is hurt.
If an animal injures a client or visitor, business liability coverage may respond to a qualifying claim against your business. An employee’s injury generally belongs under workers’ compensation. Injury to another animal needs a separate review of custody and professional-service coverage.
- Workers’ compensation
Protect the people doing the daily work.
Workers’ compensation pays medical bills and lost wages for covered work injuries and illnesses, and Illinois requires it from your first employee. Review bites, scratches, lifting injuries, and other duties across clinical, grooming, reception, and transport roles. Include part-time and temporary staffing arrangements in the review.
- Commercial property
Could you replace essential equipment after a loss?
Commercial property coverage can help repair or replace insured diagnostic equipment, furnishings, supplies, and improvements after a covered loss. Review replacement values, leased equipment, and anything taken off-site. The building owner’s policy doesn’t automatically protect your practice’s equipment.
- Equipment breakdown
A breakdown can affect both operations and animal care.
Equipment breakdown coverage can help with qualifying sudden mechanical or electrical failures. Review HVAC, diagnostic equipment, and other critical systems, along with related income losses. Emergency animal relocation may need separate protection; ordinary wear and maintenance generally aren’t covered.
- Spoilage coverage
Temperature-sensitive stock needs its own coverage check.
Vaccines, medications, and laboratory materials can lose value after a refrigeration failure. Ask about spoilage coverage, covered temperature changes, utility interruptions, and peak inventory limits. Repairing the refrigerator and replacing its contents are separate coverage questions.
- Business income and extra expense
What happens to income if the practice must close?
Business income coverage replaces lost profit, plus continuing expenses like rent and payroll, while you recover from covered physical damage. Extra expense coverage may help with temporary facilities or other recovery measures. Illness outbreaks and precautionary closures don’t automatically qualify.
- Cyber insurance
Client records and scheduling systems need protection, too.
Cyber insurance pays the response costs after a covered breach or ransomware attack. Review client contact details, payment information, medical records, and outside software providers. Ask about data restoration and qualifying income loss when a cyber event interrupts scheduling or treatment workflows.
- License-defense coverage
A licensing complaint is different from a malpractice lawsuit.
Veterinary license-defense coverage may help with specified legal expenses responding to a licensing-board complaint. It may require an endorsement and have its own limit. Don’t assume professional liability automatically pays for disciplinary proceedings, fines, or penalties.
- Employment practices liability
Employment disputes create a separate exposure.
Employment practices liability insurance pays defense costs and covered damages when an employee claims discrimination, harassment, or wrongful termination. Review protection for claims involving employees, applicants, and third parties. Wage-and-hour disputes and unpaid compensation often have exclusions or limited coverage.
- Commercial auto and animals in transit
Does protection follow the pets you transport?
Business vehicle liability, vehicle damage, and injury to animals in transit involve different coverage questions. Review commercial auto and animal bailee protection together, including drivers, transport limits, and loading and unloading. Mobile grooming or veterinary services need additional review of onboard operations and equipment.
Send us your current policies and tell us the most animals you hold at one time, and we will show you which of these your practice already has.
Illustrative coverage options. Coverage must match your professional services, animal custody, staffing, and transportation activities. Policy terms, limits, deductibles, and exclusions apply.
Veterinary & Pet Care Insurance for Clinics, Groomers & Boarders on the North Shore
A veterinary clinic in Wilmette, a grooming salon in Winnetka, a doggy daycare in Evanston, and a boarding kennel in Northbrook all hold animals their owners treat as family. A standard business policy treats those same animals as property, which is why pet care needs its own coverage review.
Professional liability and animal bailee coverage usually come from specialty carriers, and we pair them with the carrier that writes the property and general liability.
Key Coverages for Veterinary & Pet Care Businesses
- Veterinary Professional Liability (Malpractice): Covers claims of negligence, errors, or omissions in the diagnosis, treatment, or care of animals. It is the foundational coverage for any veterinary practice.
- Equipment Breakdown: Veterinary clinics rely on expensive diagnostic equipment: X-ray machines, ultrasound, surgical tools, laboratory instruments, and anesthesia systems. This covers mechanical and electrical failure.
- Income Protection (Actual Loss Sustained): If a covered event forces your practice to close, income protection covers your lost income for the restoration period, up to the policy’s limits.
- Dependent Properties Coverage: If a key supplier (pharmaceutical distributor, lab services provider) suffers a loss that impacts your ability to operate, this coverage protects your income.
- Data Breach Response: Veterinary practices store customer payment data, pet health records, and personal information. This covers breach notification, forensic investigation, and credit monitoring costs.
- Employment Practices Liability: Covers claims from employees alleging discrimination, harassment, or wrongful termination. Wage-and-hour disputes are usually excluded or limited.
- Data Breach Liability: Extends beyond response expenses to cover third-party lawsuits and regulatory actions arising from a data breach.
Who We Insure
- Veterinary clinics and animal hospitals
- Emergency and specialty veterinary practices
- Pet grooming salons
- Doggy daycare and pet sitting services
- Boarding kennels and catteries
- Pet training facilities
- Mobile veterinary and grooming services
For a veterinary and pet care insurance quote, send us your current policies, or call 847.242.1040.
Serving pet care businesses in Wilmette, Northfield, Winnetka, Glencoe, Kenilworth, Evanston, Northbrook, Highland Park, Glenview, Skokie, and across Chicago’s North Shore.
Pet Care Businesses Have Care, Custody, and Control Exposure
Veterinary clinics, groomers, kennels, trainers, dog daycares, mobile groomers, and pet boarding businesses are entrusted with animals that clients consider family. A standard business policy may not fully address injury, escape, illness, death, or allegations involving animals in the business’s care, custody, or control.
Coverage should be reviewed for animal bailee exposure, professional liability, general liability, property, equipment breakdown, business income, workers compensation, cyber/POS systems, and hired/non-owned auto if employees drive for business purposes.
Equipment and Interruption Risk Can Be Significant
Veterinary practices may depend on diagnostic equipment, refrigeration for medications, computer systems, phones, appointment software, and specialized buildouts. Groomers and boarding operations may depend on plumbing, HVAC, washing equipment, cages, dryers, and safety systems.
A covered loss that closes the business can create more than property damage. It can lead to canceled appointments, boarding relocation, lost revenue, client communication challenges, and temporary operating expenses.
Certificates, Leases, and Landlord Requirements
Many pet care businesses lease space and must satisfy landlord insurance requirements. Those requirements may include general liability limits, property coverage for tenant improvements, additional insured wording, waiver of subrogation, and proof of workers compensation. Longmeadow Insurance can help review those requirements before renewal or lease signing.
Related Insurance Guides
Erie and Other Veterinary Markets
We quote Erie Insurance on veterinary and pet care accounts as an appointed agent, covering the property, general liability, and workers compensation side of the practice.
Professional liability for animal care is the piece that usually needs a specialty market, since standard forms treat animals in your care as property rather than as a professional exposure. We combine those markets and compare the whole structure against alternatives rather than quoting one carrier.